


Why Medical Properties Trust Is Back On Investors’ Radar
Medical Properties Trust (MPT) just reported third quarter 2026 results that swung from a loss to net income, with higher sales and revenue compared with a year earlier, putting fresh attention on the stock.
Recent enthusiasm around Medical Properties Trust comes against a tough backdrop, with the share price down 38.1% over the past month and 55.4% across 90 days, while the 1 year total shareholder return has declined 54.5%. This suggests sentiment is still fragile despite the earnings turnaround.
Scan Medical Properties Trust’s rebound alongside other income-focused real estate plays by reviewing our curated list of 5 dividend fortresses for ideas with yields that may justify a second look.
Medical Properties Trust now reports earnings back in the black while the share price has been heavily sold off. Is this a solid hospital landlord temporarily mispriced, or is the low tag exactly what it is worth?
Most Popular Narrative: 60% Undervalued
On the most followed valuation view, Medical Properties Trust screens as meaningfully cheaper than its implied fair value of $5.13 based on a 12.54% discount rate, compared with the last close at $2.05. That gap rests on a thesis that the real estate and rental income base can support a more durable earnings profile than the current share price suggests.
Successful refinancing and extension of near term debt maturities, highlighted by a US$2.4b secured notes transaction that reduces gross debt by about US$123m and pushes large maturities out to 2032, together with actions that leave no maturities until mid 2028 apart from sterling bonds, lowers refinancing pressure and can reduce interest expense and support net margins.
See why 114 investors see Medical Properties Trust as 60% undervalued.
Result: Fair Value of $5.13 (UNDERVALUED)
Still, Medical Properties Trust carries real execution risk if recently restructured tenants struggle with rent payments or if regulatory moves disrupt hospital real estate values.
Find out about the key risks to this Medical Properties Trust narrative.
Another View: Earnings Multiple Paints A Different Picture
The DCF output flags Medical Properties Trust as overvalued at $2.05 versus an estimated future cash flow value of $1.41. Yet on a simple P/E check of 4.9x, compared with a fair ratio of 7.8x and peer averages near 18x, the stock screens as cheap. Which signal should carry more weight for you?
Before leaning too hard on either signal, it helps to see how the SWS DCF model actually gets to its number, and where assumptions on future rent, earnings and interest costs do the heavy lifting. Look into how the SWS DCF model arrives at its fair value.
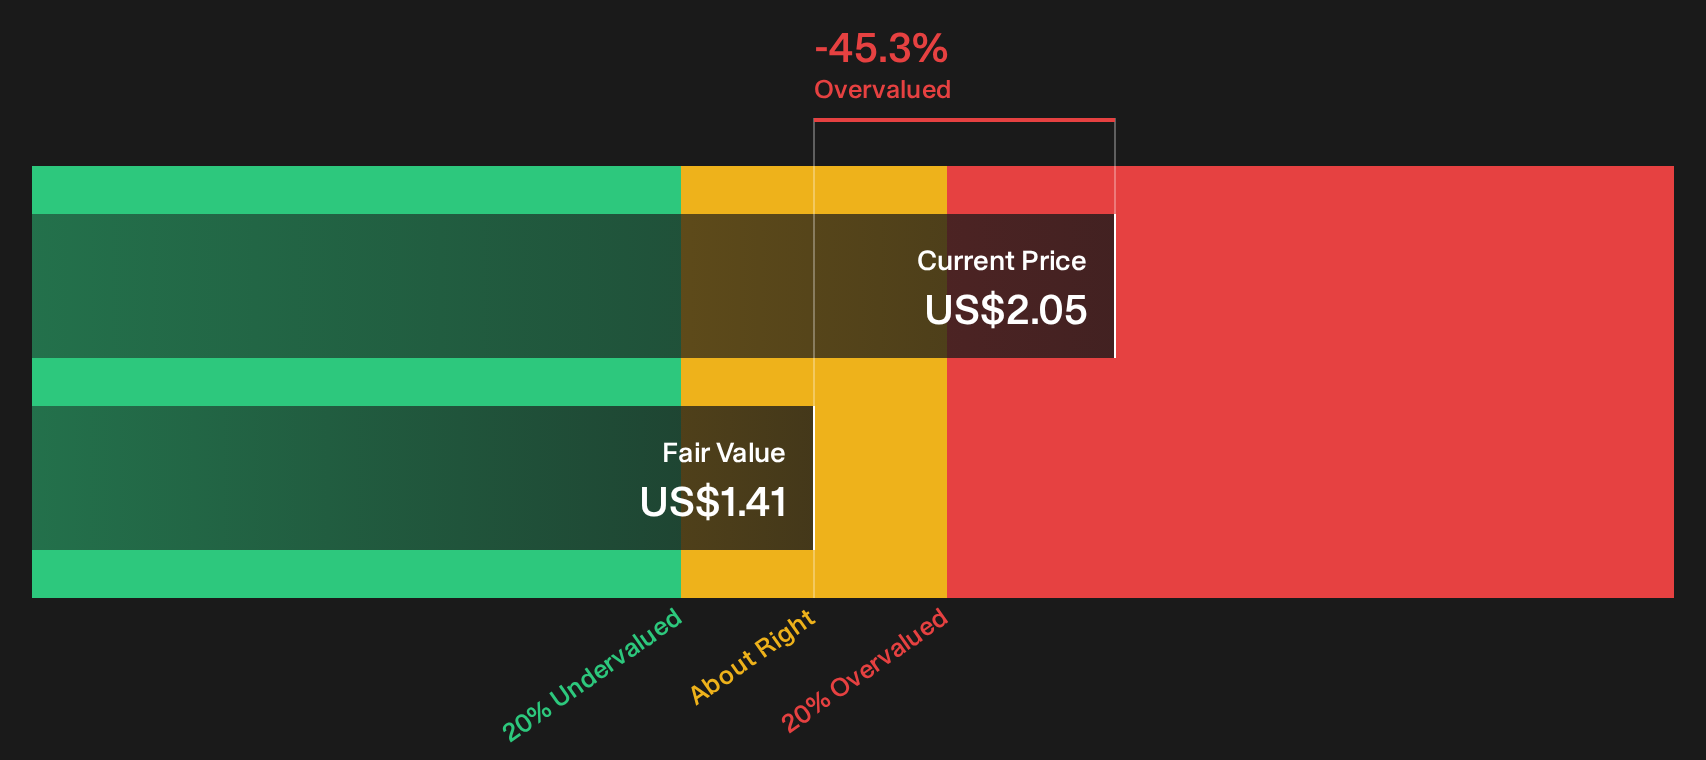
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Medical Properties Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear clue, either way Medical Properties Trust now sits in a place where the data matters more than the headlines. Move quickly, review the evidence on both sides and weigh the 3 key rewards and 4 important warning signs.
Want More Ideas Beyond Medical Properties Trust?
Do not stop with one hospital landlord. Use the Simply Wall Street Screener to quickly surface fresh opportunities that match the kind of portfolio you want to build next.
- Target potential bargains early by checking the 19 high quality undiscovered gems that combine solid fundamentals with relatively low attention from the market.
- Focus on durability first and scan a list of solid balance sheet and fundamentals (25 results) where financial strength helps support business resilience when conditions get tougher.
- Prioritise capital protection and review a 31 resilient stocks with low risk scores that groups companies with lower risk scores so you are not chasing returns blindly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com