


Williams Companies has delivered a long stretch of strong shareholder returns, so the real question now is whether the current share price still lines up with what its earnings can support. After that kind of run, you want to know if you are paying a fair earnings multiple or simply leaning on momentum and good headlines.
- Over the past 5 years, Williams Companies has returned about 200.3%, which puts real pressure on the current earnings profile to justify where the valuation sits today.
- Recent profit growth and the acquisition of Momentum Midstream may support expectations for sturdier natural gas earnings, which feeds directly into how much investors are willing to pay for each dollar of profit.
- There is a second opinion on Williams Companies worth weighing. See what analysts think Williams Companies's shares could be worth.
The issue now is whether Williams Companies' recent share price level is justified by its earnings power when set against a Fair Ratio benchmark.
If you want a broader starting point for research beyond Williams Companies' recent run and earnings focus, scan a curated list built around 31 resilient stocks with low risk scores.
Does Williams Companies Look Pricey on Earnings?
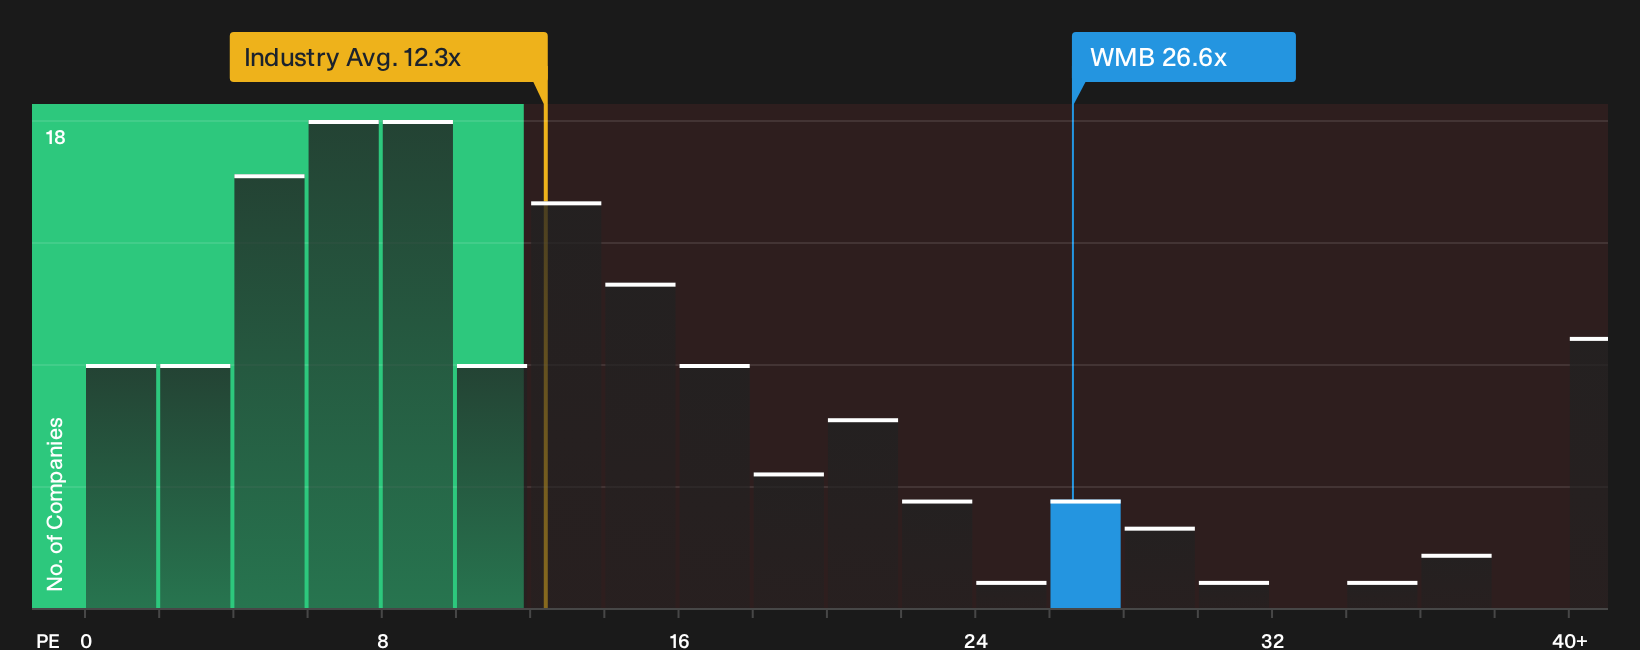
The P/E ratio is a key metric for Williams Companies because earnings per share sit at the center of how investors evaluate this pipeline operator. On that yardstick, the stock trades on roughly 26.6x earnings, which is higher than the broader Oil and Gas group at about 12.3x and also above the peer cohort near 16.2x. Relative to the Fair Ratio benchmark that weighs growth, profitability, size and risk, that premium suggests Williams Companies may be overvalued on an earnings basis.
The latest quarterly update highlighted an 8% rise in profit and a 10% lift in adjusted EPS, so the current multiple already reflects considerable optimism around the natural gas build-out and the Momentum Midstream deal. For a holder or prospective buyer, the key question is whether future results can continue to justify a double-digit premium to typical Oil and Gas valuations on this P/E measure. Explore the numbers behind Williams Companies's P/E valuation.
The Williams Companies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off for Williams Companies' stock by spelling out which paths for growth, margins and earnings would need to play out for the shares to be worth much more or much less than today, and they sit on the Community page. Rather than stopping at a single output from a ratio or model, they describe the future that figure depends on so you can watch how reality lines up with it over time.
One of the top community narratives on Williams Companies: 21% undervalued
"The current valuation implies that the market is not fully pricing in this narrative’s view that Williams Companies is undervalued relative to its contracted growth projects and Power Innovation platform…"
Discover why this Narrative puts Williams Companies at 21% undervalued.
Before acting on Williams Companies' valuation, there is one more piece to check
Numbers only tell part of the story for Williams Companies, because the people setting priorities and how they are rewarded can push results in very different directions over time. See who runs Williams Companies and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com