


Zoetis has enjoyed a sharp rebound in recent weeks after a long slide. This puts a fresh spotlight on whether the current share price lines up with what its earnings can support. With the stock trying to claw back lost ground, the key issue for you is whether that recent strength is backed by the underlying profit engine or mainly by changing sentiment.
- Over the past 5 years the share price has fallen 56.2%. This makes the current valuation conversation much more about what the earnings profile justifies today than about past highs.
- The business model depends heavily on converting animal health demand into consistent earnings. This can influence how much investors are prepared to pay for each dollar of profit if margins or cash generation shift over time.
- There is a second opinion on Zoetis worth weighing. See what analysts think Zoetis's shares could be worth.
The stock's next move may depend on whether Zoetis' recent price recovery is supported by its earnings when lined up against the Fair Ratio benchmark.
To see how Zoetis compares with other earnings driven stories, it can help to look across a wider field using 34 high quality undervalued stocks.
Does Zoetis Look Undervalued on Earnings?
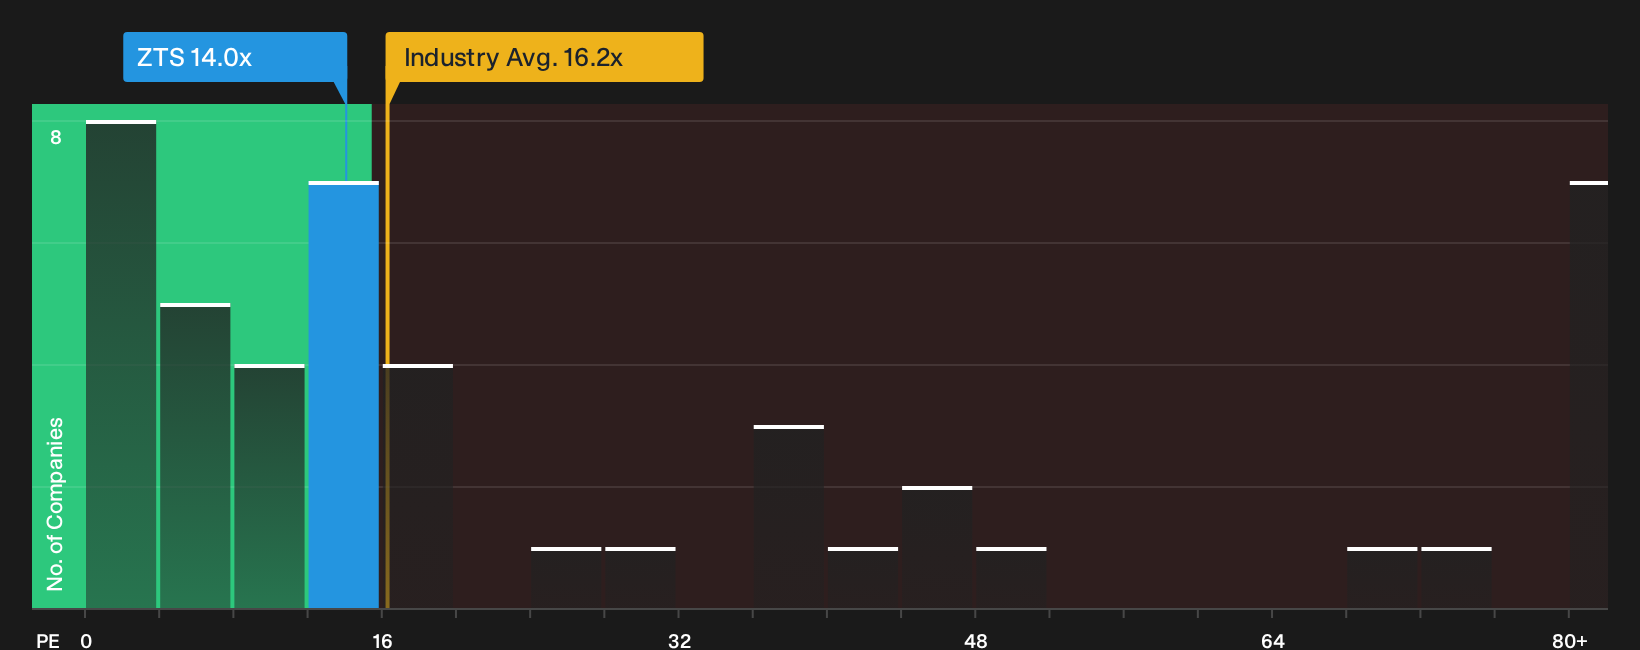
The P/E ratio is a useful lens for Zoetis because investors often look at this business through the earnings it can generate from its animal health portfolio. Zoetis currently trades on a P/E of 14.0x, which is lower than the Pharmaceuticals industry average of 16.2x and far below the wider peer group at 57.4x. For an earnings focused investor, that gap frames how cautiously the market is pricing each dollar of profit at the moment compared with many other listed drug makers.
The Fair Ratio model, which takes into account factors such as growth expectations, profitability, size and risk, points to a higher multiple than where Zoetis is trading now. That means the present 14.0x P/E sits below the level implied by those fundamentals and screens as undervalued on this earnings yardstick. For decisions, you still need to weigh how reliable those earnings are and how much volatility in cash flow you are comfortable with before treating that discount as an opportunity rather than a warning sign. Explore the numbers behind Zoetis's P/E valuation.
The Zoetis Narrative: What Would Justify Today's Price?
Zoetis' valuation puzzle only really comes into focus once you spell out what kind of future is already baked into the share price, and Simply Wall St Narratives do exactly that by turning those expectations into explicit paths for growth, margins and earnings that could justify a much higher or much lower outcome than today. Rather than relying on a single multiple or model output, each one lays out the assumptions behind its fair value view so you can compare those expectations with Zoetis' actual results as they are reported. These Narratives sit on Simply Wall St's Community page and give you a structured way to test whether the story the market is pricing still lines up with what the business delivers over time.
Community views on Zoetis pull in the same general direction on valuation, although one side clearly sees more upside in the current setup than the other.
Bull case: roughly fairly valued
"On one hand it’s not a business that’s going to grow much, and on the other hand, it’s also not likely to collapse catastrophically…"
Discover why this Narrative puts Zoetis at roughly fairly valued.
Bear case: roughly fairly valued
"The main reason for the recent collapse in the share price was because they reported that the US Companion Animal segment saw a 11% YoY decline in segment revenues…"
Explore why this Narrative puts Zoetis at roughly fairly valued.
Before you decide what Zoetis is worth, there is one more thing to check
Valuation only tells part of the Zoetis story, because Simply Wall St's broader checks have also flagged specific concerns that deserve your attention before you lean on any pricing gap. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com