


HA Sustainable Infrastructure Capital (HASI) drew fresh attention after a recent upgrade to a Zacks Rank #2, tied to an upward shift in earnings estimates that has sharpened the focus on its fundamentals.
At a latest share price of $40.38, HA Sustainable Infrastructure Capital has enjoyed a sharp run, with a 1-day share price return of 5.18%, a 30-day share price return of 11.21%, and a year-to-date share price return of 26.90%. This has occurred alongside a 1-year total shareholder return of 46.27% and a 3-year total shareholder return of 135.76%, although the 5-year total shareholder return declined 14.24%, suggesting momentum has recently strengthened as sentiment around earnings and risk has shifted in its favor.
Scan the recent momentum in HA Sustainable Infrastructure Capital against a curated 34 high quality undervalued stocks that pairs stronger fundamentals with what may be more conservative pricing.
HA Sustainable Infrastructure Capital has already rewarded investors who were in early, while recent buyers are staring at a much higher entry point. Is this surge a signal to lean in now, or a cue to wait for a reset before valuing it?
Preferred P/E of 61.6x: Is it justified?
HA Sustainable Infrastructure Capital now trades at a P/E of 61.6x, while internal fair value work points to a P/E of 16.1x and analysts currently see a price target of $48.79 against the latest close at $40.38.
The P/E ratio compares what investors are paying for each dollar of current earnings. For a specialist in sustainable infrastructure finance like HA Sustainable Infrastructure Capital, that figure effectively reflects how much confidence the market has in the durability of its profit stream and its ability to convert a growing pipeline of projects into earnings.
HASI is flagged as expensive on multiple fronts. Its 61.6x P/E is well above the estimated fair P/E of 16.1x, and it is also much richer than the peer average of 6.7x and the broader US Diversified Financial industry average of 16x. Those gaps are wide and they suggest investors are paying a premium. The fair ratio work indicates this could move closer to 16.1x if expectations or sentiment cool from current levels.
Explore the SWS fair ratio for HA Sustainable Infrastructure Capital.
Result: Price-to-Earnings of 61.6x (OVERVALUED)
Still, HA Sustainable Infrastructure Capital relies on a concentrated US sustainable infrastructure niche. As a result, weaker project economics or tighter policy support could quickly challenge today’s rich multiple.
Find out about the key risks to this HA Sustainable Infrastructure Capital narrative.
Another View: What The DCF Model Says About HA Sustainable Infrastructure Capital
The P/E looks stretched, yet the SWS DCF model points in a different direction. At $40.38, HA Sustainable Infrastructure Capital is assessed as trading about 16.4% below an estimated future cash flow value of $48.29, which frames the stock as undervalued on this metric. Which signal do you trust more when earnings expectations are doing the heavy lifting?
Look into how the SWS DCF model arrives at its fair value.
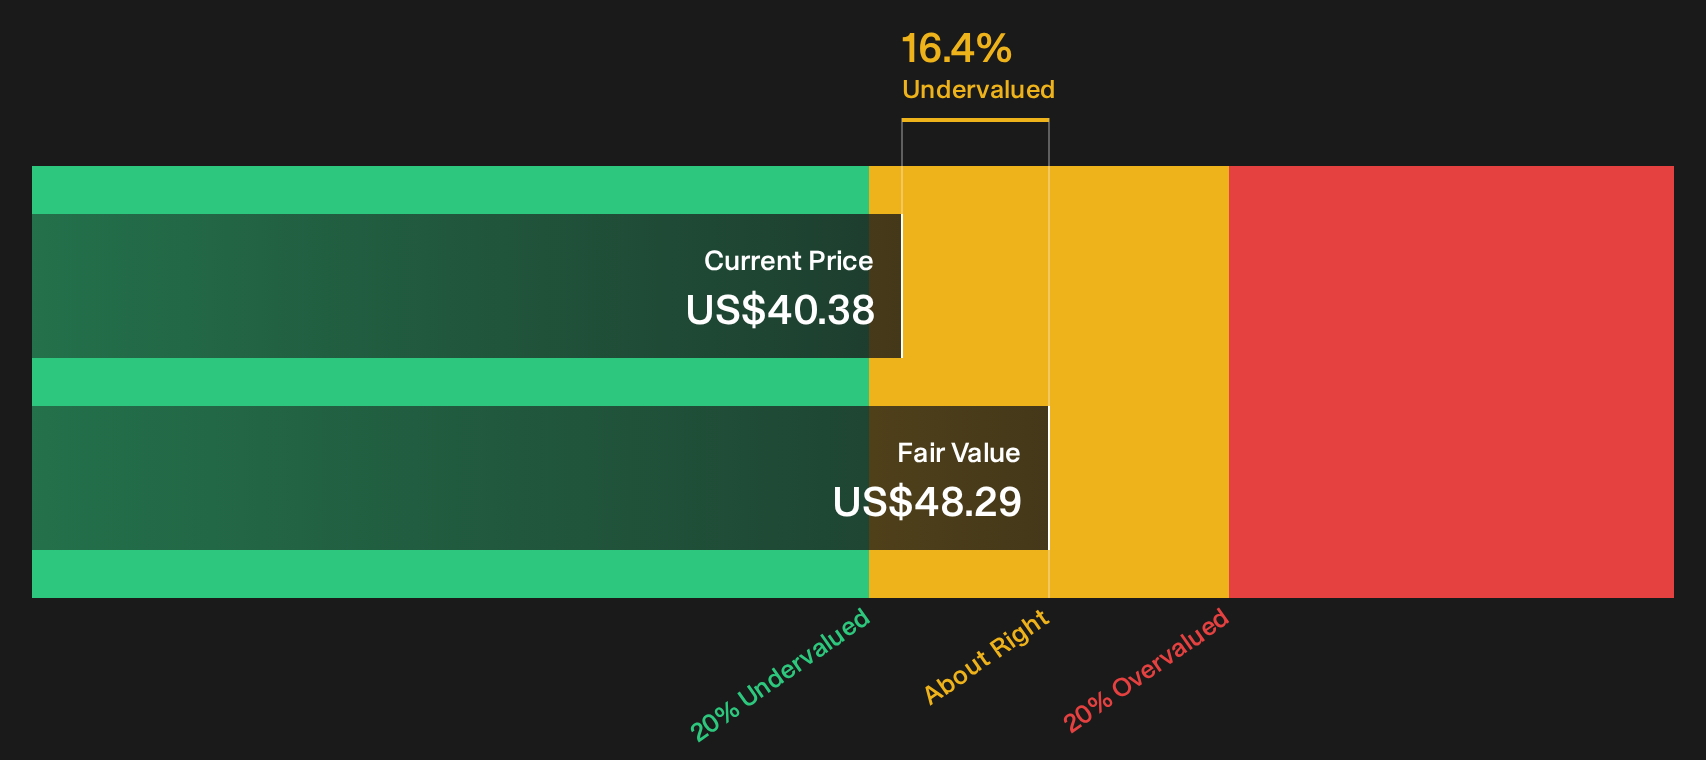
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out HA Sustainable Infrastructure Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around HA Sustainable Infrastructure Capital is clearly split, with investors weighing both meaningful risks and genuine upside. Act quickly on the data, stress test the assumptions, and weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond HA Sustainable Infrastructure Capital?
Do not stop with HA Sustainable Infrastructure Capital. Use the Simply Wall Street Screener to quickly surface other opportunities that fit the way you like to invest.
- Target higher quality potential bargains by scanning a focused 34 high quality undervalued stocks that filters for both strong fundamentals and pricing that may still be catching up.
- Strengthen your portfolio’s foundation by using a list of solid balance sheet and fundamentals (25 results) that highlights businesses with sturdier finances and fewer balance sheet surprises.
- Spot potential future leaders early by reviewing a curated 19 high quality undiscovered gems that brings lesser-known but fundamentally robust companies onto your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com