


- Tandem Diabetes Care has experienced a steep 83.1% annual decline in earnings per share over the past five years despite revenue growth, alongside negative returns on capital and a high net-debt-to-EBITDA ratio. Together, these factors point to profitability and balance sheet pressures.
- The combination of shrinking earnings, loss-making capital deployment and limited debt capacity raises questions about how Tandem Diabetes Care might fund future expansion without meaningfully diluting existing shareholders.
- We will now look at how Tandem Diabetes Care's investment narrative is challenged by weakening profitability and rising concern over its leverage.
Balance sheet pressure at Tandem Diabetes Care can be a useful reminder to refresh your watchlist with companies that pair healthier leverage with earnings momentum, using our curated 31 resilient stocks with low risk scores
Tandem Diabetes Care Investment Narrative Recap
To own Tandem Diabetes Care, you need to believe the pump and software platform can convert a large diabetes population into sticky, recurring users despite current profitability pressure. The recent evidence of steep earnings per share declines alongside revenue growth keeps the spotlight on execution. In the near term, the key swing factor remains how efficiently the business can turn existing pump placements and PAYGO pharmacy distribution into higher quality, repeat supply revenue.
The biggest risk right now is operational strain compounding with leverage. Loss-making returns on capital and a stretched net debt to EBITDA profile restrict flexibility if infusion set supply issues persist or if the mobile app recall weighs on new pump uptake. If funding needs rise while earnings stay weak, shareholders face a higher chance of dilution from fresh equity issuance.
One update that ties closely to this story is the widened PAYGO pharmacy channel, now supporting roughly 45% U.S. formulary coverage and about 10% of domestic sales. For a stock wrestling with return on equity pressure and an earnings loss of US$63.3 million on US$1.04b of revenue, that mix shift matters. Pharmacy-based supply sales can support steadier, recurring cash generation compared with one-off pump hardware cycles.
This same announcement also links directly to the key catalysts and risks investors are weighing. Better pharmacy access can blunt the impact of temporary infusion set constraints because it improves product availability and ordering convenience when supply normalizes. At the same time, if app-related issues or customer confidence problems slow new starts, the benefit of richer pharmacy margins may take longer to offset current EPS weakness, which keeps execution on PAYGO, international direct sales and Mobi rollout front and center.
Tandem Diabetes Care's current revenue base of about US$1.04b and earnings loss of US$63.3 million sit against analyst assumptions that revenue will grow by 10.7% per year and reach US$1.4b with earnings of US$61.5 million by 2029. This implies an earnings swing of roughly US$125 million from today's loss to the forecast profit.
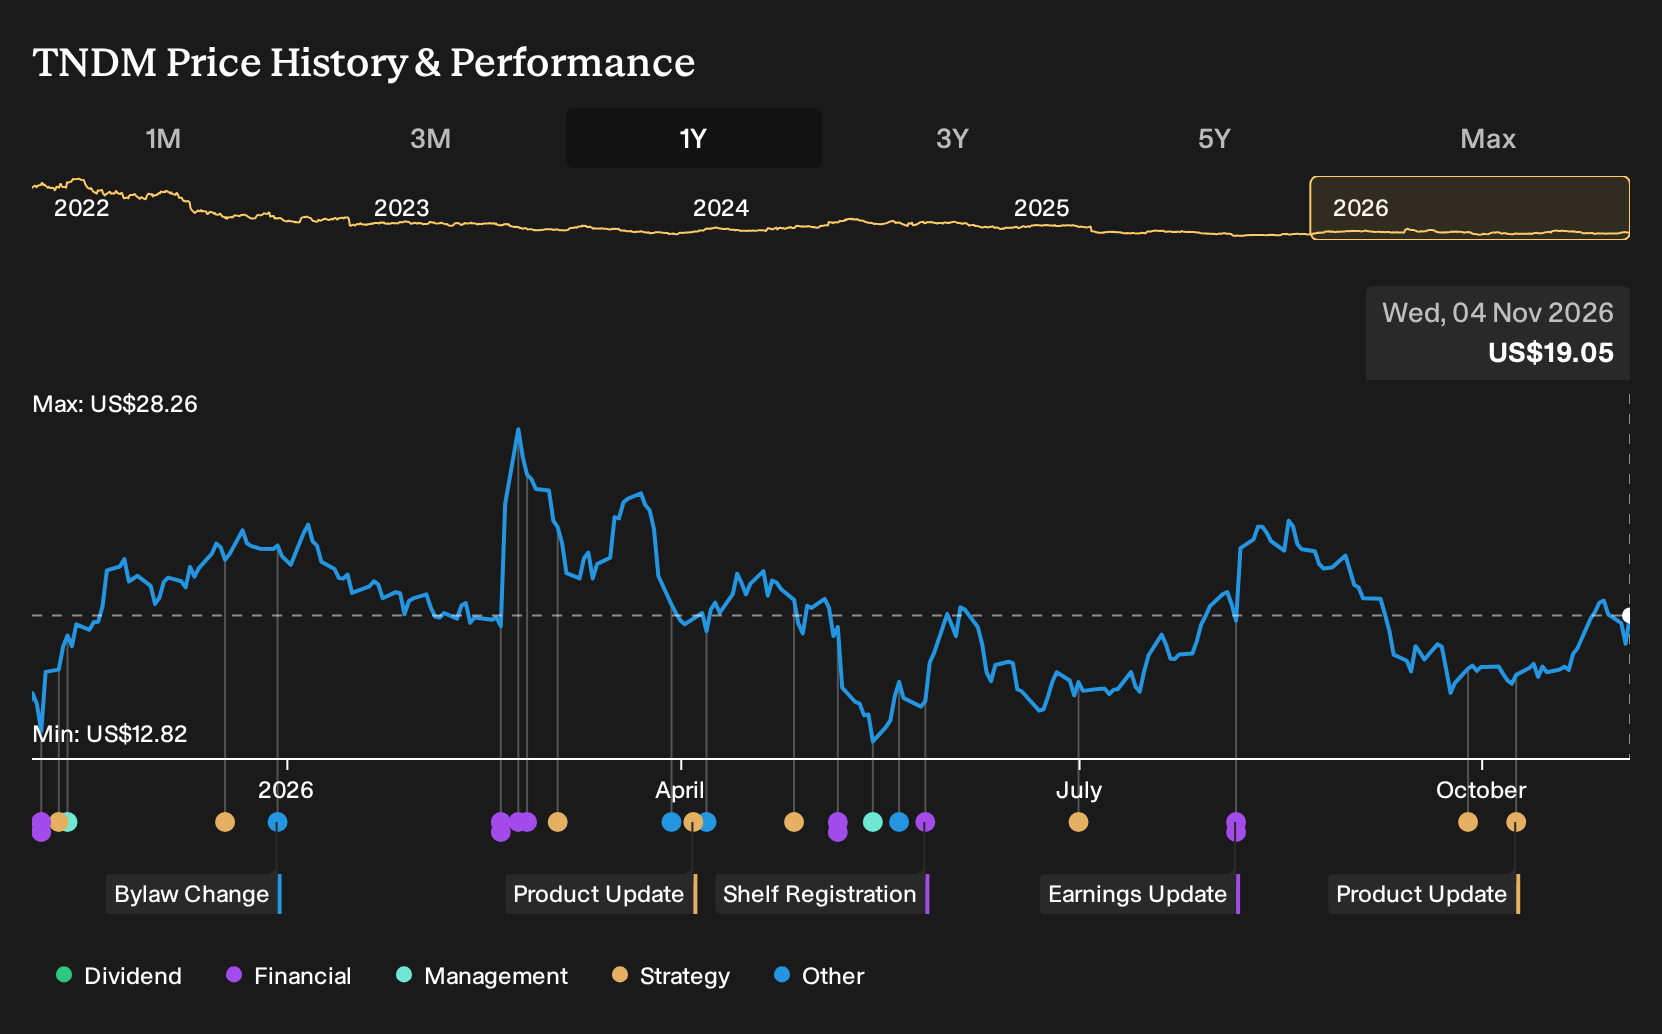
Uncover why Tandem Diabetes Care's fair value signals a 46% potential upside to its current price. This discount could narrow more quickly than many expect.
Exploring Other Perspectives
One alternate angle on Tandem Diabetes Care focuses less on PAYGO upside and more on whether the business can reach the profit levels some analysts baked in before this news. The most pessimistic voices were already pencilling in revenue of about US$1.4b and earnings near US$173.8 million by 2029, which is far more optimistic than the weakest consensus case. That spread shows how sharply opinions can differ. Treat this new information as a prompt to compare several narratives and decide which assumptions you find realistic.
Explore another Tandem Diabetes Care fair value estimate, including one that suggests it could be worth just $27.76!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Tandem Diabetes Care research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Tandem Diabetes Care. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tandem Diabetes Care's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tandem Diabetes Care?
If Tandem Diabetes Care has sharpened your focus on balance sheets, earnings quality and funding risk, it can be useful to widen your search to other businesses with different profiles and risk drivers using the Simply Wall St Screener.
- If you want potential value opportunities backed by solid fundamentals, scan through 34 high quality undervalued stocks that combine financial strength with lower implied pricing.
- If balance sheet resilience is a priority for you after reviewing Tandem Diabetes Care, filter for companies on the list of solid balance sheet and fundamentals (25 results) that emphasise robust finances and room to manoeuvre.
- If you are hunting for income ideas rather than growth stories, narrow in on reliable yield candidates using the 5 dividend fortresses to see which payouts might merit a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com