


Citigroup (C) is in the spotlight after securing approval for a wholly owned securities unit in China, and for pushing into blockchain based payments and private credit partnerships in Europe, thereby widening its global reach.
Citigroup shares trade at US$124.74, with the 1 day share price return of 1.65% and year to date share price return of 5.09% sitting against a 1 year total shareholder return of 25.20% and a very large 3 year total shareholder return of about 3.2x, which suggests that recent momentum has cooled a little even as longer term holders have seen substantial gains.
Scan how Citigroup's global push compares with other large financial players by reviewing our curated list of solid balance sheet and fundamentals (25 results) across markets and business models.
Citigroup now has fresh avenues in China, private credit and blockchain payments that speak to a broad, ambitious franchise. The real tension for investors is whether that reach is already fully reflected in today’s share price.
Most Popular Narrative: 17% Undervalued
Citigroup's most followed valuation narrative pegs fair value at about $150.71, comfortably above the recent $124.74 close. This frames the current price as a discount to that outlook.
Citigroup's global services franchise continues to scale, with Services revenue, net interest income, non interest revenue, deposits and assets under custody all rising at double digit rates in 2Q26. This supports further growth in fee and interest income as clients deepen their use of cash management, trade and securities services.
See why 207 investors see Citigroup as 17% undervalued.
Result: Fair Value of $150.71 (UNDERVALUED)
Still, this bullish Citigroup narrative can break if regulatory issues resurface in a costly way or if fintech and stablecoin rivals erode transaction banking economics.
Find out about the key risks to this Citigroup narrative.
Another View: Citigroup Through The Earnings Multiple Lens
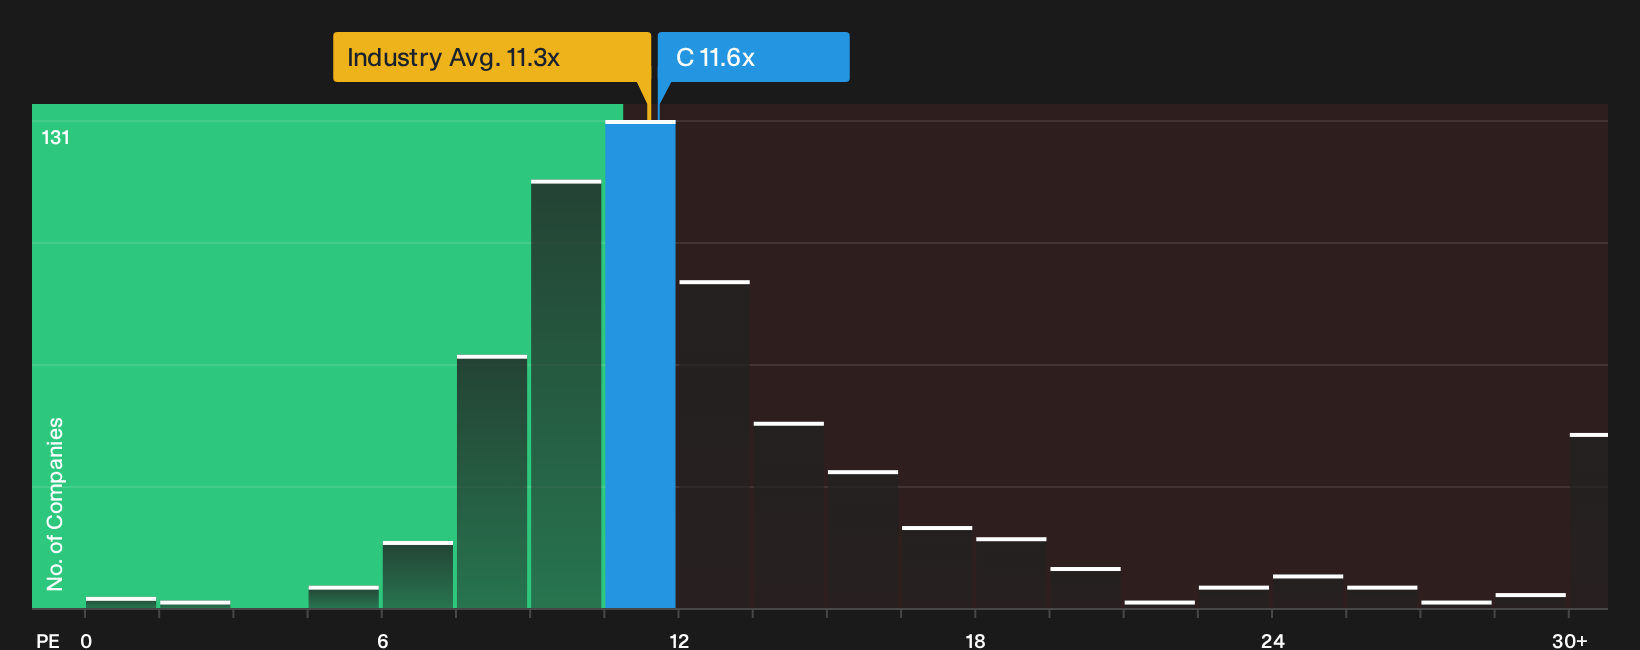
Citigroup may look cheap on some models, yet its P/E of 11.6x is slightly richer than the US Banks industry at 11.3x, while still below an estimated fair ratio of 14.3x. That mix of modest premium today and potential re rating tomorrow raises a simple question: How much valuation risk are you really willing to take for an earnings story like this?
To unpack what those earnings ratios imply in more detail, including how they stack up against peers and the fair ratio the market could move toward, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this Citigroup story feels optimistic on balance, it may be useful to quickly stress test the numbers, compare them with peers, and then decide where you stand. To see which potential upsides analysts are focused on, review the 5 key rewards.
Looking for more investment ideas beyond Citigroup?
You have a clear view on Citigroup now. Widen your opportunity set and pressure test your thinking against other quality businesses before the next move.
- Target potential upside by scanning our curated universe of quality companies trading at appealing valuations through the 34 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with stronger financial footing using the 31 resilient stocks with low risk scores.
- Get ahead of the crowd by checking a focused 19 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com