


- Ultima Genomics selected its UG200 Sequencing Platform for Phase III of Singapore's National Precision Medicine program and announced a collaboration with Lucence and Qiagen to support clinical whole genome sequencing for about 450,000 individuals across the country's public healthcare system.
- Qiagen's positioning as both a collaborator in large scale genomics programs and a key player in the growing biopreservation market highlights how its sample to insight tools increasingly sit inside real world clinical and cell therapy workflows rather than only in research labs.
- We will now look at how Qiagen's investment narrative could be influenced by its role in Singapore's National Precision Medicine initiative.
Spot opportunities riding the same precision medicine and biopreservation wave as Qiagen by scanning our hand picked 38 healthcare AI stocks shaping data driven healthcare workflows.
Qiagen Investment Narrative Recap
To own Qiagen, you need to believe that its sample to insight workflow can keep pulling more diagnostics and life sciences activity onto its platforms while funding remains uneven in research and some clinical budgets. The big near term swing factor is execution in automation, digital PCR and bioinformatics, which are expected to support margins even as QuantiFERON immigration testing stays softer.
The key risk is that cautious spending in academia and hospitals lingers, which could delay instrument upgrades and slow the absorption of new assays. The Singapore precision medicine work looks directionally helpful for visibility, but on its own does not fundamentally change those near term risks and catalysts.
The collaboration around Singapore’s National Precision Medicine program links Qiagen directly to a large scale clinical genomics rollout rather than a pure research project. That matters for the story because it shows the firm’s tools embedded in population level healthcare workflows, which is where long running consumables use and software contracts tend to build.
Set against the biopreservation market, which is estimated at US$10.7b by 2032, this type of clinical genomics deployment offers a concrete example of the kind of projects that could support Qiagen’s automation, bioinformatics and biopreservation exposure. The opportunity sits alongside ongoing risks around research funding, QuantiFERON immigration volumes and instrument upgrade timing.
Qiagen's current analyst narrative points to revenues of US$2.5b and earnings of US$557.7m by 2029, based on assumed yearly revenue growth of 6.2% and an earnings increase of about US$148m from US$409.3m today.
Uncover why Qiagen's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
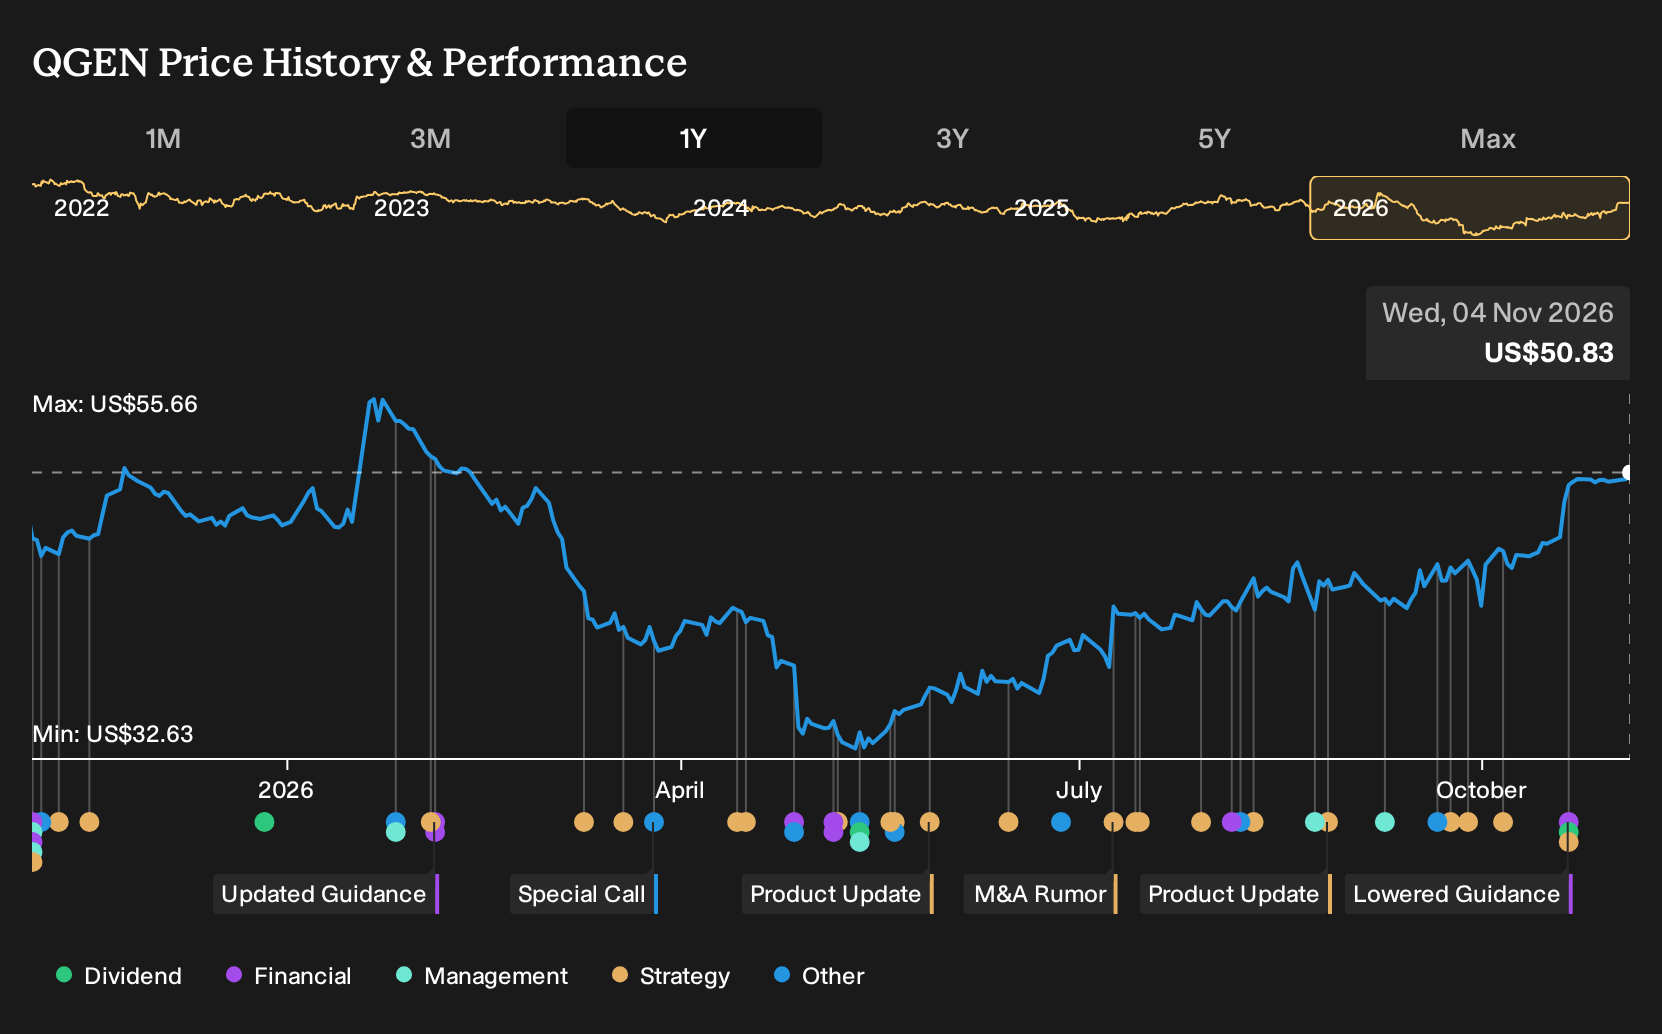
Exploring Other Perspectives
One alternate view fixates on the risk that QuantiFERON immigration testing never really recovers, even as Qiagen joins Singapore’s precision medicine rollout. The most cautious analysts were modeling only 4.9% annual revenue growth to about US$2.4b by 2029 and a lower 18.8x P/E before this news, which could prompt very different revisions.
Explore 4 other Qiagen fair value estimates, including one that suggests as much as 19% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Qiagen research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Qiagen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Qiagen's overall financial health at a glance.
Looking For More Ideas Beyond Qiagen?
Once you have a view on Qiagen, it can help to line it up against other possibilities so your portfolio is not leaning on a single story.
- If capital preservation is a priority, start with resilient businesses by checking out 31 resilient stocks with low risk scores that score well on stability metrics and risk profiles.
- If income matters more to you, scan for steady cash generators through a curated set of 5 dividend fortresses that focus on higher yields with supporting fundamentals.
- If you are hunting for mispriced opportunities, broaden your watchlist with a targeted 19 high quality undiscovered gems that surfaces financially solid companies sitting off the usual radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com