


- U.S. Physical Therapy reported third quarter 2026 results with revenue of US$222.56 million and net income of US$11.05 million, compared with US$197.13 million and US$13.14 million a year earlier.
- The mix of higher sales and lower profit highlights rising cost and margin pressure, which matters for a business built on record visit volumes and hospital affiliations.
- We will now look at how U.S. Physical Therapy's higher revenue but lower net income could reshape the existing investment narrative.
U.S. Physical Therapy Investment Narrative Recap
To own U.S. Physical Therapy, you need to believe that record visit volumes, hospital affiliations and the Industrial Injury Prevention segment can offset stubborn margin pressure. The latest quarter fits that tension. Higher revenue came with lower net income, which keeps the spotlight firmly on whether cost initiatives, technology rollouts and clinic scale can stop earnings from drifting sideways.
The key near term catalyst still sits in operational execution. Investors are watching whether clinic level efficiencies and hospital partnerships can translate visit growth into cleaner profit per visit. The main risk remains reimbursement pressure and rising labor and benefit costs, which the latest nine month figures suggest are still weighing on profitability.
The most relevant disclosure here is management’s nine month update. Revenue for the period reached US$634.9 million compared with US$578.26 million a year earlier, while net income was US$25.98 million compared with US$35.43 million. That gap between top line progress and earnings underlines how much work is left on costs, mix and clinic level productivity.
For catalysts that matter to you as a shareholder, that nine month trend keeps Industrial Injury Prevention growth, hospital affiliations and technology rollouts front and center. Those projects target efficiency and a second earnings pillar, which may help offset reimbursement and wage headwinds. The risk is that record clinic activity continues to translate into only modest profit, which would keep the margin story under strain.
U.S. Physical Therapy's narrative links analyst forecasts of US$1.0b in revenue and US$97.9 million in earnings by 2029 to an expected 8.4% yearly revenue growth rate and an earnings increase of about US$95.2 million from earnings today of US$2.7 million.
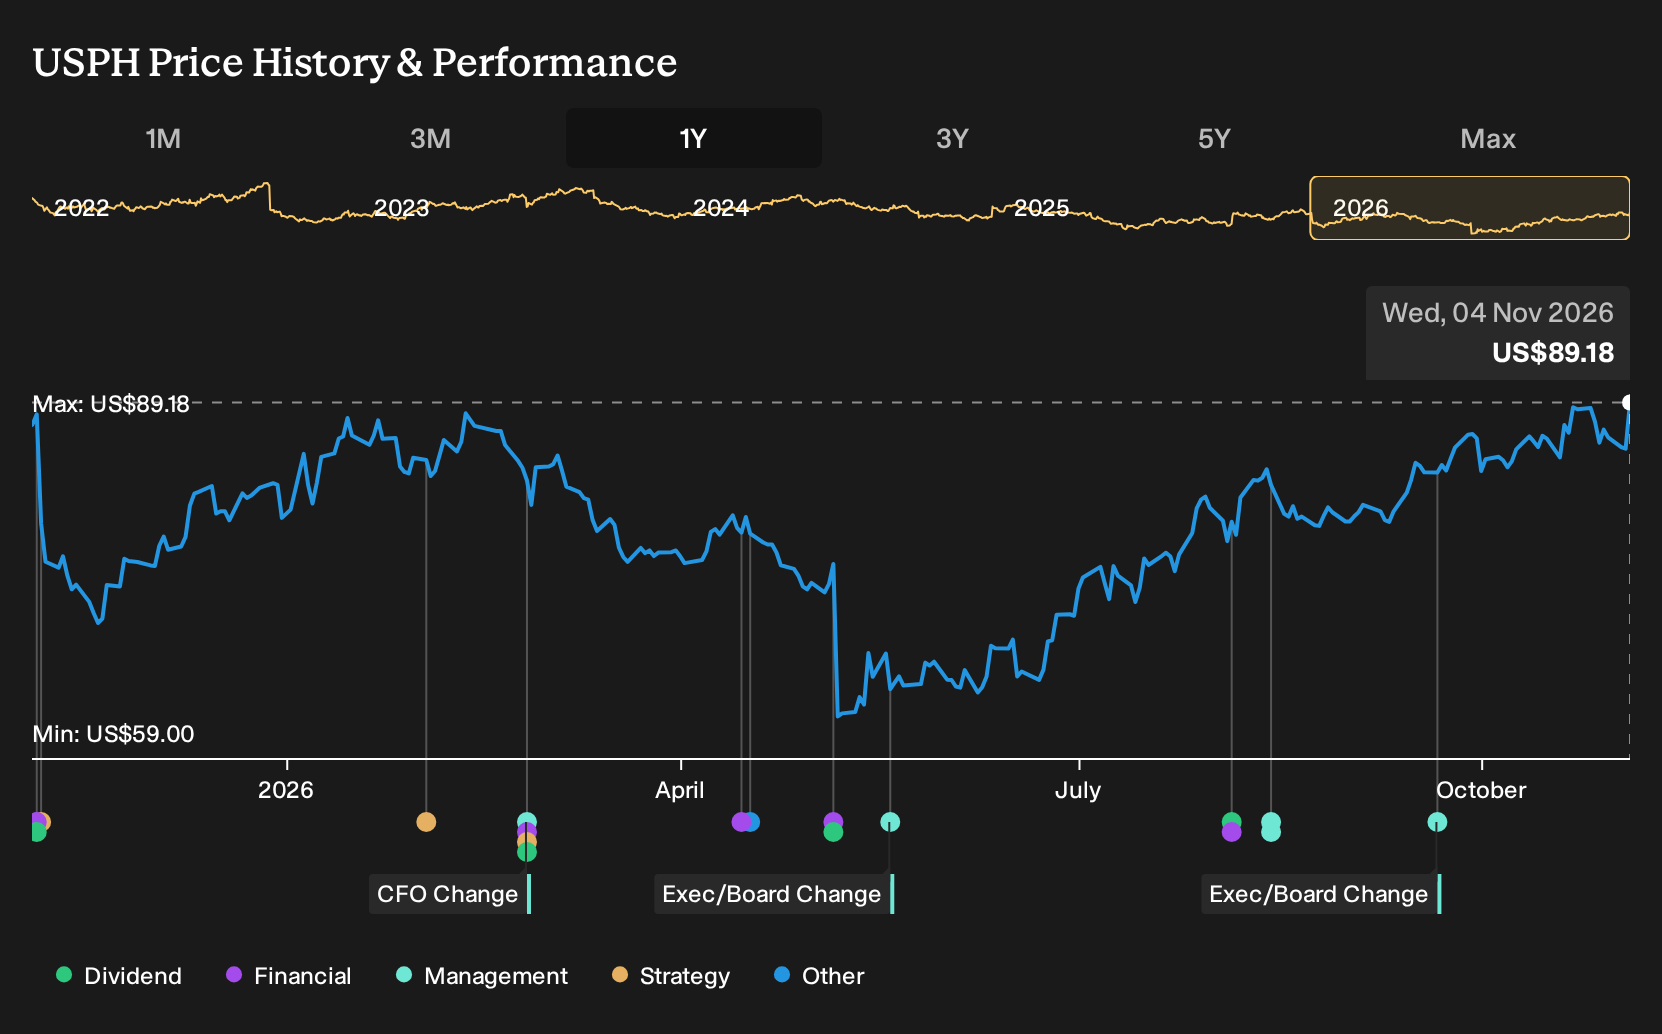
Uncover why U.S. Physical Therapy's fair value indicates a 9% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span from US$97 to about US$179.67, which already shows how far apart retail estimates on U.S. Physical Therapy can land. Compare that range with risks around reimbursement pressure and labor costs, then decide which assumptions you trust and explore more community viewpoints.
Explore another U.S. Physical Therapy fair value estimate, including one that suggests there could be as much as 101% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your U.S. Physical Therapy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for U.S. Physical Therapy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate U.S. Physical Therapy's overall financial health at a glance.
Looking For More Investment Ideas Beyond U.S. Physical Therapy?
Once you understand where U.S. Physical Therapy fits in your portfolio, it often helps to compare it with other opportunities that have different risk and income profiles. A focused screener can save time by surfacing stocks that already match the kind of financial traits you care about most.
- If you want potential value combined with quality metrics, scan for companies that look underpriced relative to fundamentals through 34 high quality undervalued stocks.
- If resilience and balance sheet strength sit high on your checklist, filter for financially sturdier businesses using the list of solid balance sheet and fundamentals (25 results).
- If you are hunting for under-the-radar ideas, broaden your watchlist through a 19 high quality undiscovered gems that surfaces lesser known stocks with solid underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com