


Australian interest rates have moved higher at home and abroad, and that puts blunt pressure on companies that rely on short term market mood. Founder led Australian businesses sit in a different camp. The person who built the company still calls the shots and often thinks in decades, not quarters. This article walks through three founder guided stocks from our screener that show how that mindset can shape long term portfolios.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is personally invested in long term outcomes. However, if you want the strongest names, these 7 top founder-led companies are the top of the list.
Flight Centre Travel Group (ASX:FLT)
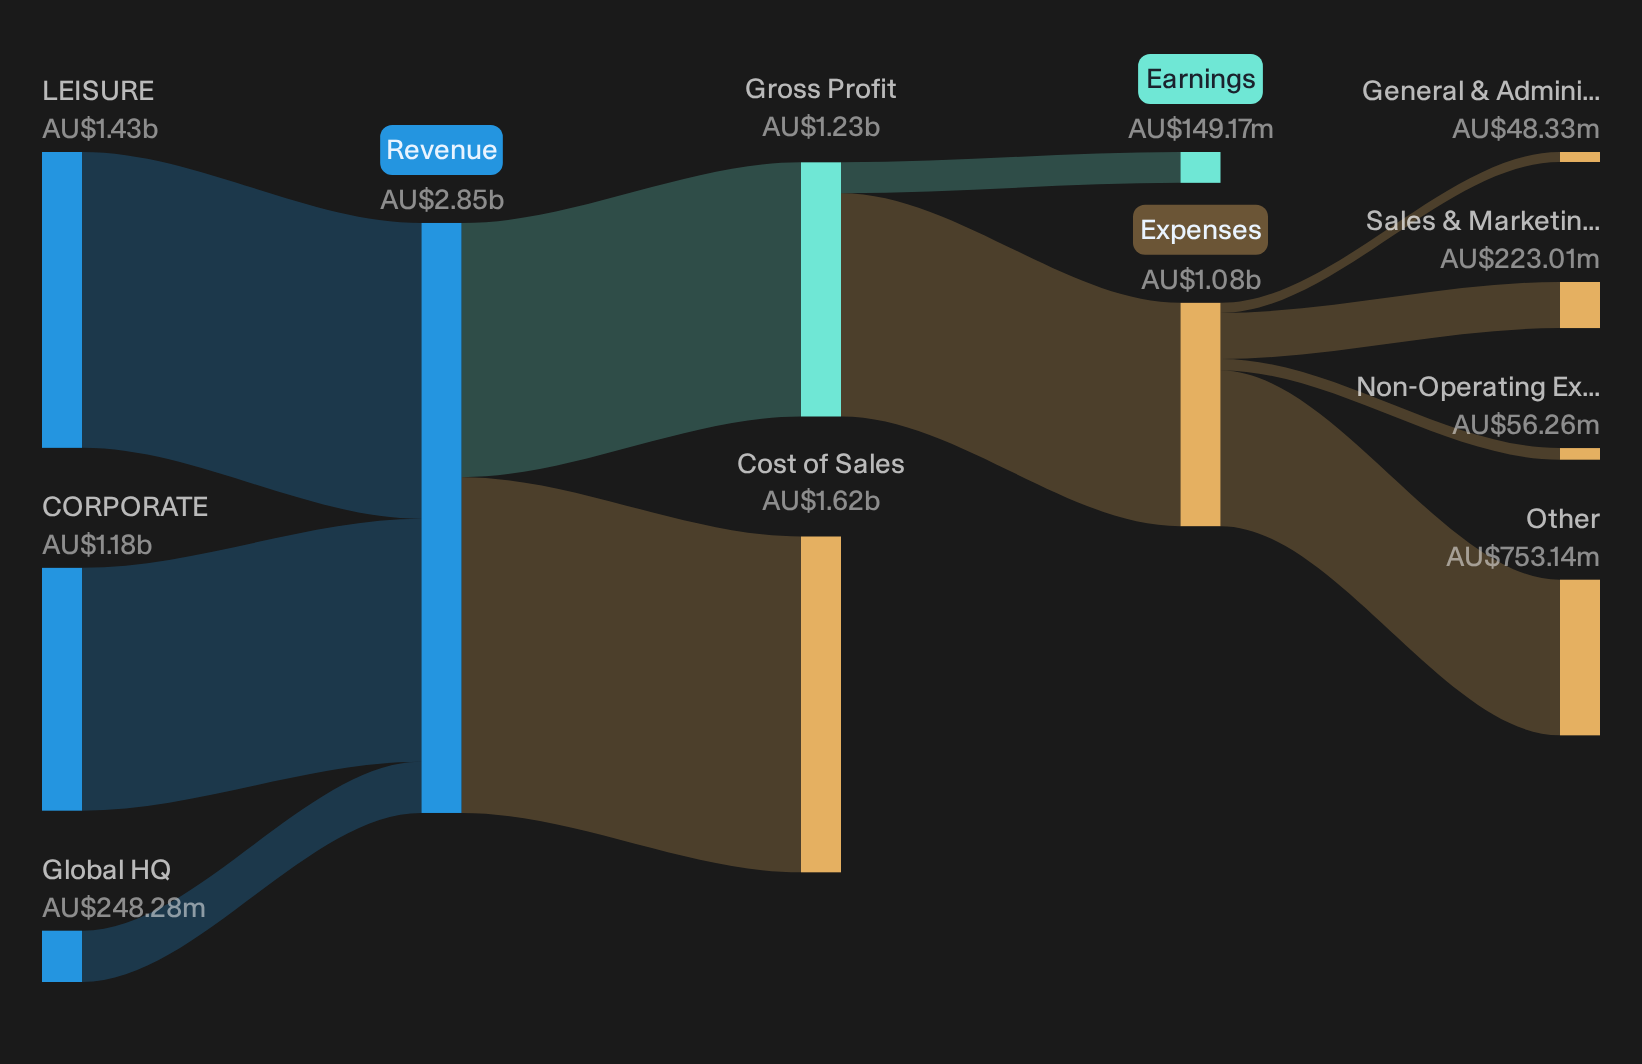
Flight Centre Travel Group is a founder-influenced travel intermediary that links leisure and corporate clients to airlines, hotels, and tours, with about A$1.4b from leisure, A$1.2b from corporate and A$248 million from global headquarters activities, and a market value near A$2.5b.
Flight Centre Travel Group taps into the founder-led theme through its long-running Flight Centre, Corporate Traveller and FCM brands, where leadership has spent decades refining how those businesses earn their keep.
"Despite the rapid customer growth in World360 Rewards, the program has already consumed about A$34 million in below the line spend in FY26 and is expected to incur up to roughly half that amount in FY27 within operating costs, which can weigh on reported EBIT and delay any earnings contribution from higher frequency or partner funded revenue."
The real swing factor now is how one quiet shift inside the broader loyalty and premium travel push ultimately filters through to margins and cash returns.
That margin question is exactly what the full narrative for Flight Centre Travel Group unpacks, showing how loyalty spend, capital discipline and founder influence could be decoupling near term noise from longer term outcomes.
Harvey Norman Holdings (ASX:HVN)
Harvey Norman Holdings is a founder-influenced retail and property group built around Gerry Harvey’s long-running franchise formula, with earnings spread across furniture, bedding, consumer electronics and in-house property investment.
Retail operations in New Zealand (about A$952 million), Ireland (around A$777 million) and Singapore and Malaysia (roughly A$787 million) sit alongside smaller regional arms and A$232 million from non-franchised outlets. Together these back a business now valued at roughly A$5.4b in market cap.
Harvey Norman matters for a founder-led screen because Gerry Harvey’s long involvement ties day-to-day franchising decisions to the same people who helped design the model in the first place. This is exactly what investors here are looking to test.
"It is worth noting, however, that just over 20% of 2025 profit can be attributed to property revaluations, non-cash gains that can be volatile and are not recurring operational earnings."
What really counts now is how one quiet shift in underlying store performance and franchise economics bends future cash returns, either way.
If that mix of franchising economics and property noise has your attention, the full narrative for Harvey Norman Holdings shows where earnings risk may be masking resilience and optionality.

GenusPlus Group (ASX:GNP)
GenusPlus Group gives this founder-led screen direct exposure to long duration grid and renewable build outs, with A$837 million from Infrastructure and A$369 million from Energy and Engineering, backed by A$152 million from Services, all inside an Australia-focused platform now worth about A$1.7b in market value.
GenusPlus Group appeals to founder-led investors because leadership is tied to long lived grid projects where reputations are built over decades, and today that means juggling established powerline work with a growing pipeline across renewables, storage and heavier engineering challenges.
"Although GenusPlus Group points to multi year opportunities in renewables and storage, the move to scale up battery, solar and substation work requires more complex engineering and project management, and the current comment that Energy & Engineering margins are a little bit low suggests execution pressures could restrain segment EBITDA if these projects prove harder to deliver profitably."
The real story now is whether one pressure point inside that expanding project mix quietly shifts the balance between growth, cash conversion and long term returns.
That balance is exactly what the full narrative for GenusPlus Group unpacks, showing how current execution risk could be masking a much stronger long term earnings engine.

Seeking Alternatives Before Others Catch On
Fresh ideas move first. Once the market catches a new story, entry points can fly or drop quickly. Scan these under the radar opportunities while it matters.
- Spot income workhorses early and review the 5 dividend fortresses that aim to keep payouts flowing while others are still chasing yesterday's yield stories.
- Review the 41 power grid technology and infrastructure stocks for potential infrastructure opportunities before momentum traders arrive and pricing fully reflects the build out narrative.
- Assess the 93 robotics and automation stocks curated for businesses wiring automation into real world production while it is still under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com