


Why Las Vegas Sands Filed A Broad Shelf Registration
Las Vegas Sands (LVS) has put a universal shelf registration in place that covers debt, preferred and common equity, warrants, depositary shares, purchase contracts and units, giving the business flexible capital-raising options.
The filing lands as investors weigh weaker profitability at Marina Bay Sands and fresh debt at Sands China, prompting closer scrutiny of how any future funding choices could intersect with cash flow and current valuation.
Recent trading has been volatile for Las Vegas Sands, with the share price jumping 6.48% in the last session and delivering a 12.48% 7 day return. However, the 1 year total shareholder return is down 33.17%, suggesting short term momentum is building after a tougher stretch for longer term holders as investors reassess risks around profitability, new debt and the fresh shelf registration at a US$40.74 share price.
Scan how Las Vegas Sands stacks up against other potential rebound stories by reviewing the curated 35 high quality undervalued stocks that currently pair solid cash flows with stronger balance sheets.
After a sharp short term pop and a tough 1 year stretch, Las Vegas Sands now trades near internal valuation estimates. Does that still leave enough upside to justify the shelf overhang and recent profitability questions?
Most Popular Narrative: 18% Undervalued
Las Vegas Sands last closed at $40.74 while the most followed narrative pegs fair value near $49.94 using a 10.32% discount rate, which frames the new shelf registration against expectations for Macau and Singapore to keep driving earnings power.
The ongoing focus on premium mass and VIP customers in Macau, supported by VIP rolling volume share of 26% and very large year on year rolling volume gains, points to a mix that could support higher gaming revenue and more resilient earnings power over time.
See why 26 investors see Las Vegas Sands as 18% undervalued.
Result: Fair Value of $49.94 (UNDERVALUED)
Still, the narrative can break if weakness in Macau gaming revenue persists and if repeated earnings misses at Las Vegas Sands continue to erode confidence in management execution.
Find out about the key risks to this Las Vegas Sands narrative.
Another View: What Our DCF Model Says About Las Vegas Sands
The narrative crowd sees Las Vegas Sands as 18% undervalued at $40.74 versus a fair value around $49.94. Our DCF model is more cautious. It puts future cash flow value near $39.77, which leaves the stock trading slightly above that estimate and raises the question of which lens you trust more.
To see how the SWS DCF model works under the hood, and what would need to change for the output to move closer to the narrative fair value, Look into how the SWS DCF model arrives at its fair value.
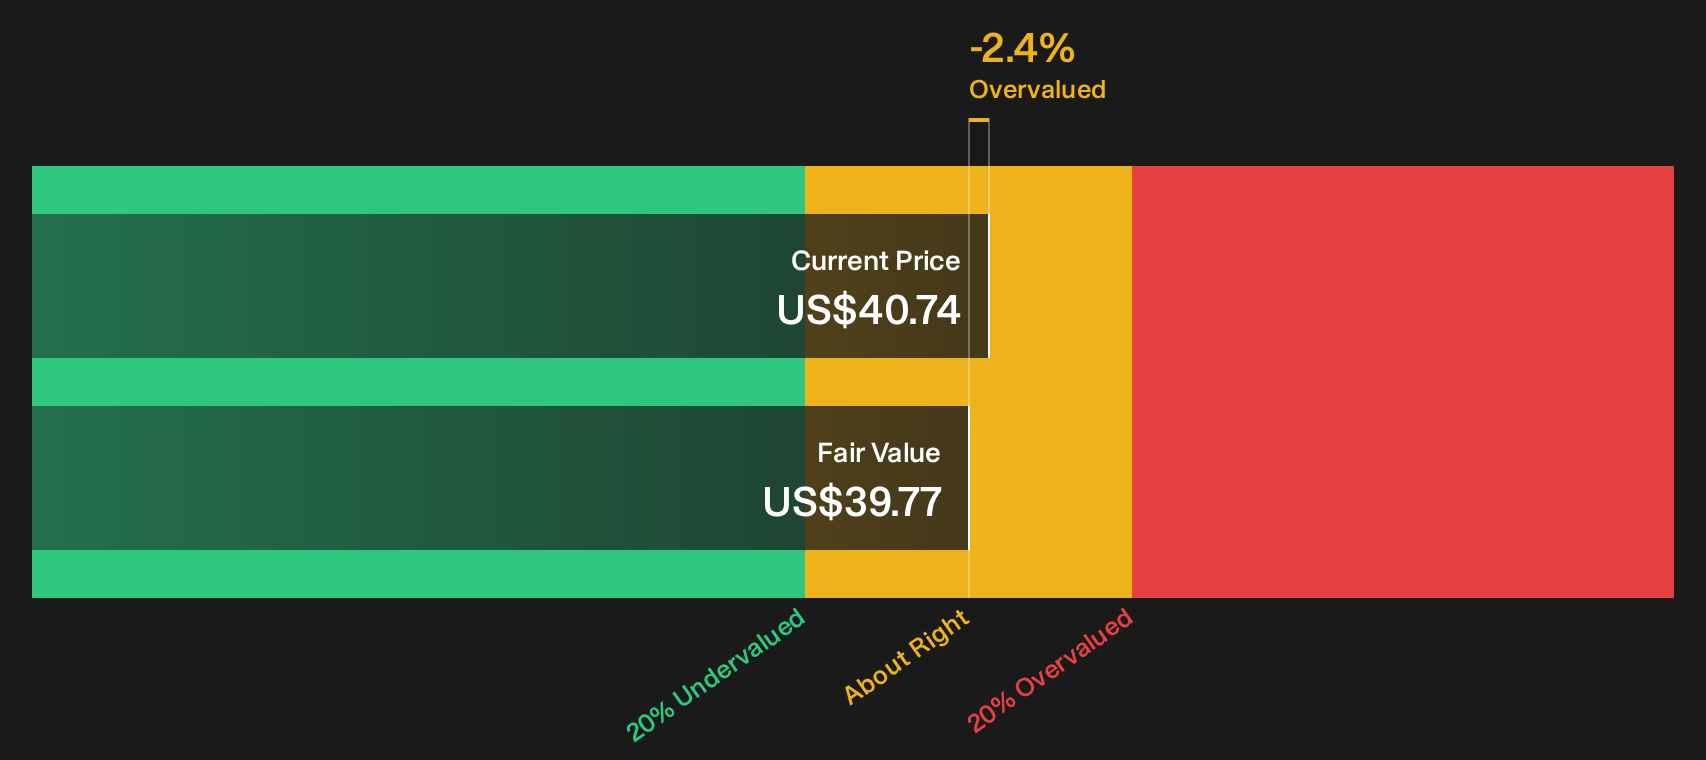
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Las Vegas Sands for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Las Vegas Sands can be confusing. Move quickly to do your own homework and weigh both sides by reviewing the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Las Vegas Sands?
If Las Vegas Sands has you thinking harder about opportunity and risk, do not stop with one ticker. Cast a wider net and pressure test your ideas.
- Target potential mispricings by scanning a curated 35 high quality undervalued stocks that filters for quality fundamentals and room for sentiment to catch up.
- Build a sturdier core in your portfolio by zeroing in on a list of solid balance sheet and fundamentals (24 results) that can better handle pressure when conditions turn.
- Get ahead of the crowd by reviewing a focused 19 high quality undiscovered gems before these quieter stories start attracting wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com