


DraftKings has seen a sharp reset in its share price over the past few years, and the stock is still drawing fresh attention as investors weigh new product launches and shifting sentiment. With the quote sitting where it is today, the live question is whether that price can be squared with the revenue the business is generating.
- Over the past 5 years the share price has fallen 43.2%. This puts the focus squarely on whether the current valuation can still lean on its sales story.
- Recent discussion about a potential profit inflection and the push into prediction markets, including crypto event contracts, can influence how much revenue investors expect DraftKings to convert into future earnings and cash generation.
- There is a second opinion on DraftKings worth weighing. See what analysts think DraftKings's shares could be worth.
For investors, the debate is whether DraftKings' current market value is properly anchored in what its sales actually support.
If you are weighing whether DraftKings' revenue story justifies today's share price, it can help to line it up against other high quality undervalued ideas from the 35 high quality undervalued stocks.
Is DraftKings Still Cheap on Sales?
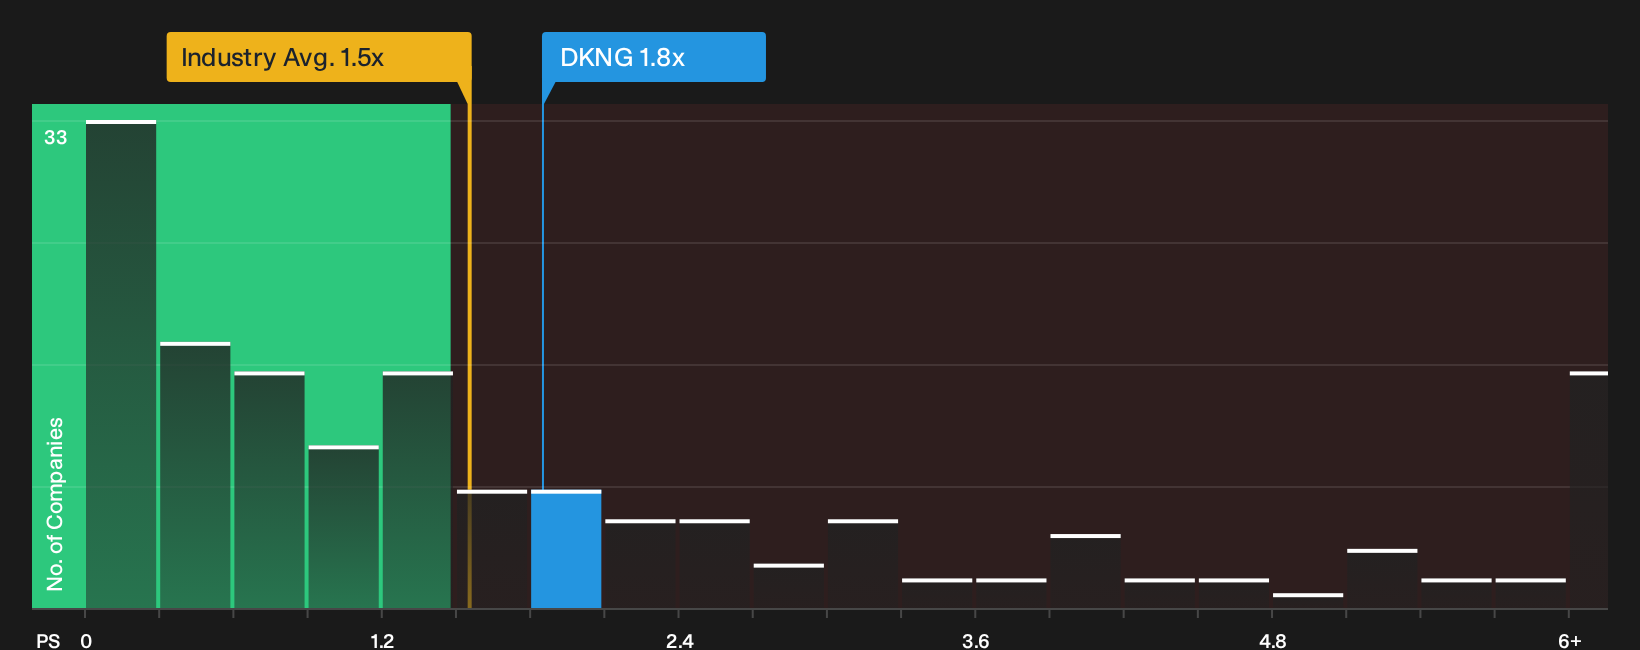
P/S is often the cleaner yardstick for DraftKings because the business is still building toward steady earnings while revenue remains the clearer anchor. On this measure, the stock trades on a P/S of 1.8x, above the Hospitality sector average of about 1.5x and also above the 1.2x peer group level. That indicates the market is willing to pay more per dollar of DraftKings' sales than it pays for a typical competitor.
Recent enthusiasm around prediction markets and potential profit inflection, highlighted by Oppenheimer and others, has not pushed the P/S to extreme territory. However, it still screens cheaper than what a tailored fair multiple model would imply given the company’s profile. Since that framework points to a higher ratio than today’s 1.8x, the shares screen undervalued on this sales lens even after the recent news-driven bounce. Explore the numbers behind DraftKings's P/S valuation.
The DraftKings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S discussion leaves off and explain which paths for DraftKings' growth, margins and earnings would need to occur for the stock to be worth meaningfully more or less than it is today. All of this is housed on the platform's Community page. Each scenario assigns a fair value estimate to a specific mix of potential catalysts and risks, so you can track over time which version of DraftKings' story is actually unfolding.
Investor narratives around DraftKings now split between those who see prediction markets and the Super App as underappreciated, and those who think structural headwinds are still underpriced.
Bull case: 30% undervalued
"Expansion of DraftKings Predictions as a vertically integrated product, with over 600,000 customers year to date 2026 and annualized traded volume rising from US$2.3b in April to US$11b in July..."
Discover why this Narrative puts DraftKings at 30% undervalued.
Bear case: 10% overvalued
"As legalization slows, competition intensifies, state tax rates rise, and new prediction market platforms such as Kalshi and Polymarket begin competing for users..."
Explore why this Narrative puts DraftKings at 10% overvalued.
Before you act on DraftKings' valuation, one more factor deserves a closer look
Price, sales and stories only go so far without asking who is steering DraftKings, how their incentives are set up, and what that means for your risk. See who runs DraftKings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com