


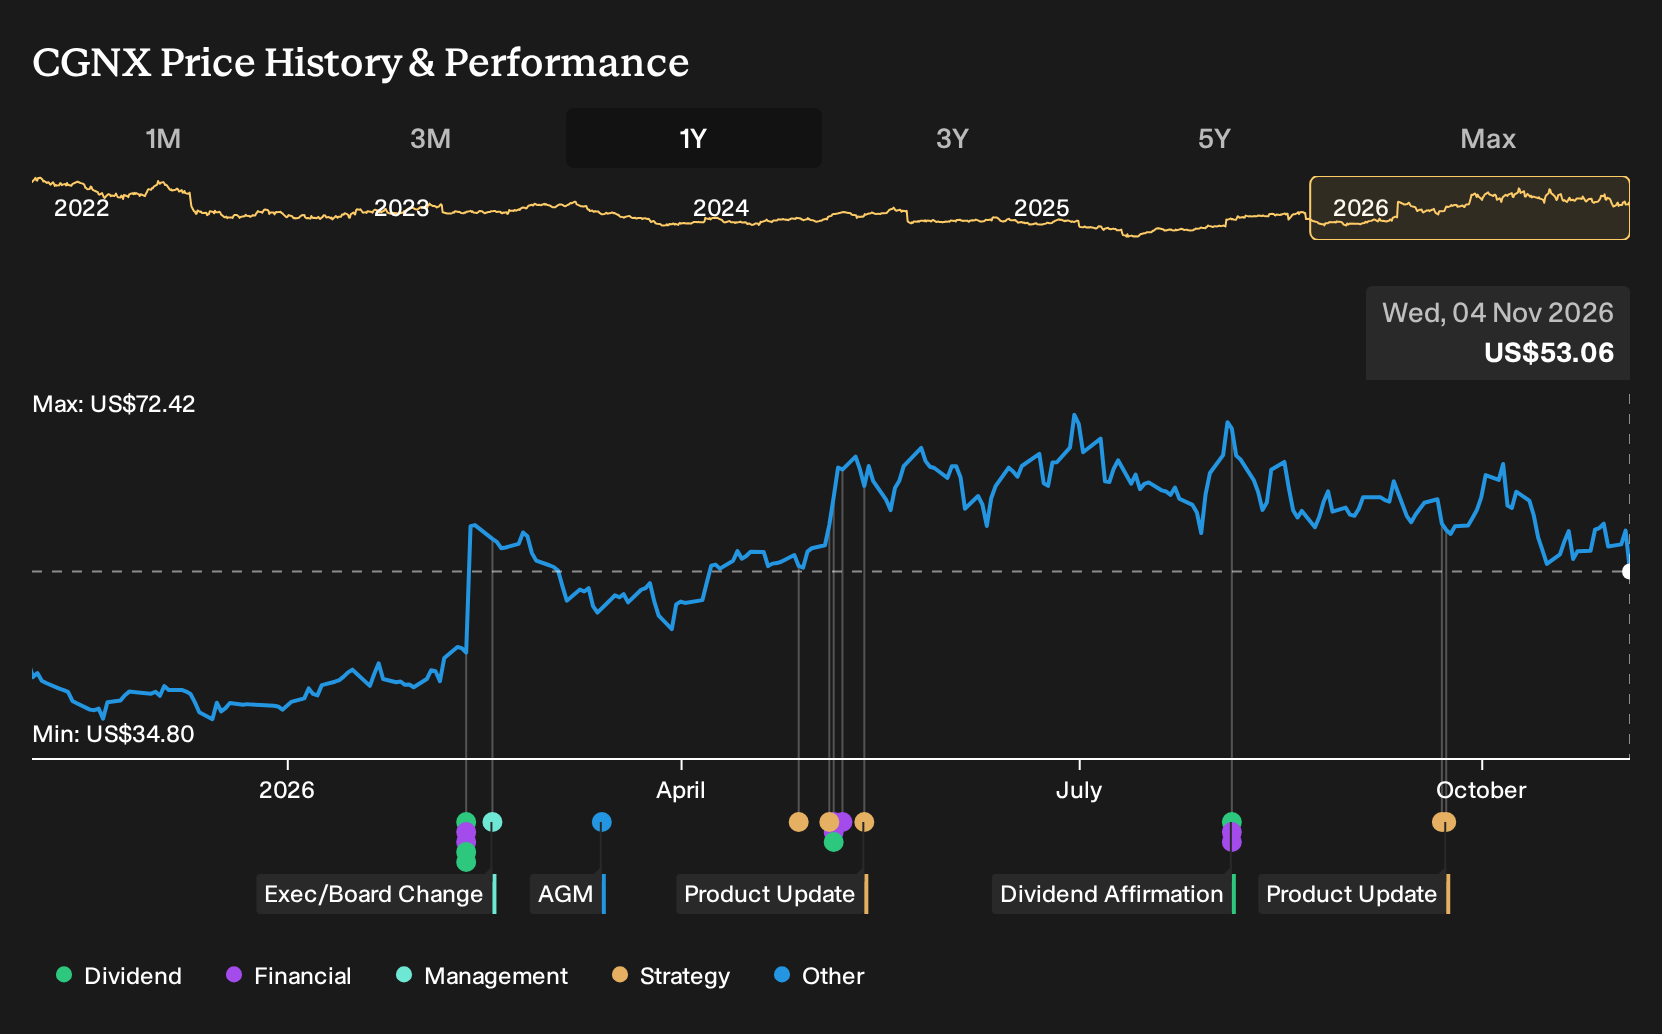
- Cognex reported Q3 2026 sales of US$313.39 million and net income of US$84.82 million, with earnings and revenue above analyst estimates and full year guidance raised.
- The planned acquisition of RealSense and management’s focus on AI powered machine vision indicate that Cognex is moving further into higher complexity vision systems and depth sensing markets.
- We will now look at how Cognex’s stronger earnings and raised outlook might reshape the investment narrative investors use to assess it.
Scan beyond Cognex and explore other robotics and automation players that may be experiencing similar earnings and AI tailwinds with our hand picked 93 robotics and automation stocks in one place.
Cognex Investment Narrative Recap
To hold Cognex, you generally need to believe that AI powered vision systems, cloud tools like OneVision, and exposure across logistics, packaging, electronics and semiconductors can support a healthier earnings profile over time. The latest quarter, with sales of US$313.39 million and net income of US$84.82 million, points to solid execution against that thesis.
In the near term, the key catalyst is operational follow through on the raised full year earnings guidance and next quarter revenue outlook. The biggest risk remains pressure on gross margin from hardware commoditization and higher component costs. The Q3 beat supports confidence in execution, but it does not remove those margin and pricing headwinds.
The most relevant update for that thesis is Cognex lifting full year adjusted EPS guidance after quarterly earnings per share from continuing operations reached US$0.50, with US$1.23 diluted EPS for the first nine months. That guidance change indicates that management views current demand and cost control as supportive of stronger profitability than previously outlined.
For catalysts, investors are likely to watch how this upgraded outlook interacts with RealSense integration and AI powered product rollout. Stronger earnings give Cognex more room to absorb RealSense’s early contribution, fund semiconductor and packaging offerings like the In Sight 1750, and still work against risks from pricing pressure and elevated memory costs.
Cognex's current analyst narrative points to revenues of US$1.5b and earnings of US$386.7 million by 2029, based on forecast revenue growth of 10.3% a year and an earnings increase of about US$212 million from US$174.8 million today.
Uncover why Cognex's fair value indicates a 50% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The biggest contrast comes from a risk focus on Cognex’s richer valuation. Before this Q3 beat, the lowest analysts were only penciling in about US$1.4b of revenue and US$313.4 million of earnings by 2029, and saw a modest US$63.07 fair value. That more cautious view may shift, so it is worth exploring both narratives before you decide.
Explore 5 other Cognex fair value estimates, including one that suggests as much as 48% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own instincts.
- A great starting point for your Cognex research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cognex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cognex's overall financial health at a glance.
Looking For More Ideas Beyond Cognex?
Once you have formed a view on Cognex, it can help to set it in context by looking at other businesses that match your risk tolerance, income needs, or preference for balance sheet strength. The Simply Wall St Screener lets you scan the market quickly using those filters so you can build a watchlist that genuinely fits how you like to invest.
- If you want income potential on your radar, start with companies that offer stronger yields and see which ones show up as 5 dividend fortresses.
- If capital preservation matters most, narrow the field to businesses with steadier fundamentals through our 31 resilient stocks with low risk scores.
- If you prefer to focus on financially robust operators, shortlist opportunities using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com