


Amdocs has seen its share price fall sharply in recent months, which puts the focus squarely on whether the current valuation can still be explained by its earnings power. With fresh contract news and a legal dispute both in play, the key issue for investors is how today’s price lines up against what the business is earning right now.
- The stock is down 45.9% over the past year, which raises a direct question about how the market is reassessing the value of Amdocs’ earnings stream.
- New long-term AI focused collaborations with telecom operators such as AT&T and Vodafone Business UK may support expectations for future earnings and cash flow, even as the dispute with T-Mobile introduces uncertainty around part of the company’s contract base.
- There is a second opinion on Amdocs worth weighing. See what analysts think Amdocs's shares could be worth.
The issue now is whether Amdocs’ current share price is appropriately aligned with its earnings, given both the recent share price decline and the mix of new contracts and legal risks.
If you are weighing Amdocs against other earnings focused tech plays after this drop, it helps to compare it with companies in 53 AI infrastructure stocks.
Is Amdocs Still Cheap on Earnings?
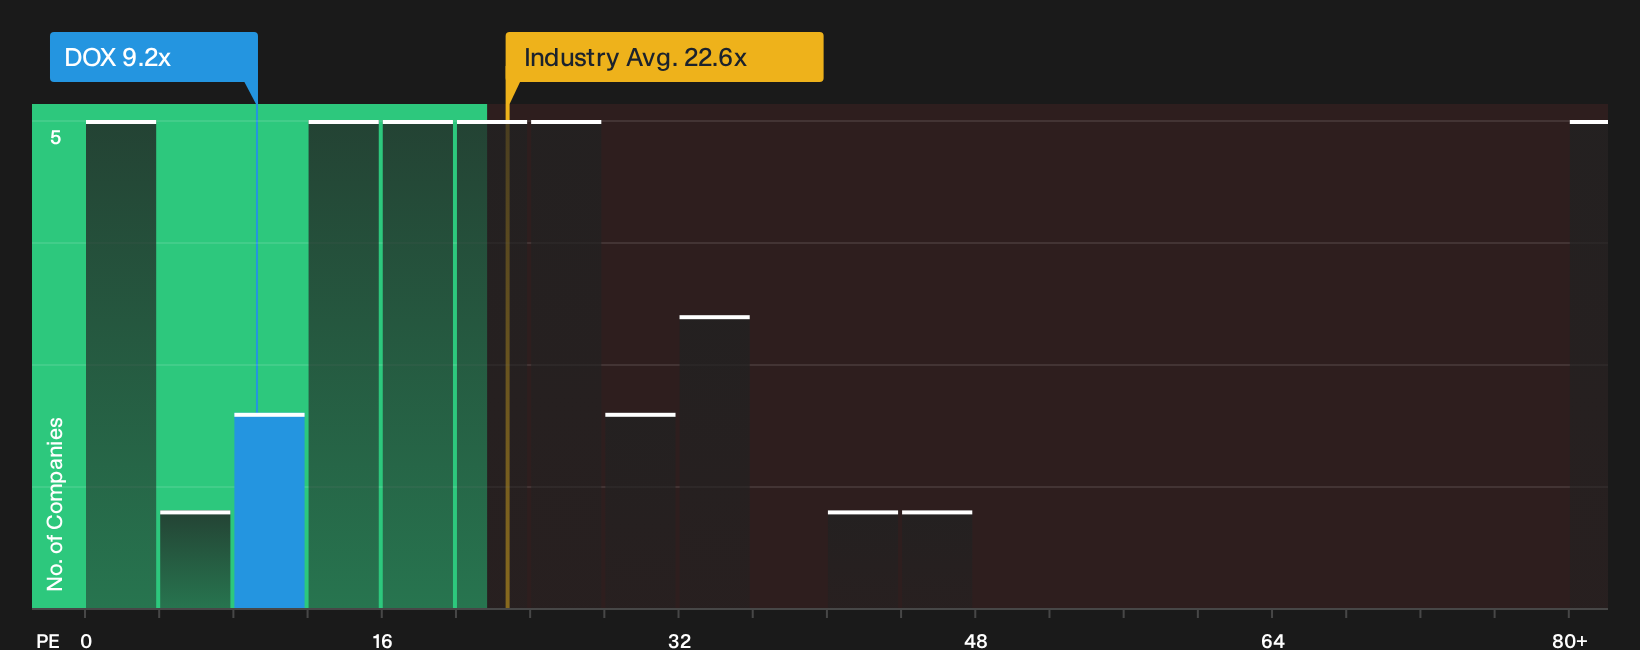
P/E is a clean way to look at Amdocs because earnings remain the main yardstick investors use for mature software and services providers. On that lens, the current P/E of about 9.2x sits well below the broader IT industry average of roughly 22.6x and a peer group closer to 24.8x. The stock is also trading under the level suggested by a more tailored fair P/E that factors in Amdocs’ size, margins, sector and risk profile. This points to a discounted earnings tag rather than a rich one.
Because the AT&T AI collaboration and other recent deals give investors more concrete revenue streams to weigh against the T Mobile dispute, this low P/E is being judged against fresh contract information rather than just sentiment. For anyone comparing earnings focused tech holdings, the key question is whether that gap to sector and peer multiples fairly reflects the legal overhang and business mix or leaves room for a re rating if those risks ease. Explore the numbers behind Amdocs's P/E valuation.
The Amdocs Narrative: What Would Justify Today's Price?
Narratives pick up where the Amdocs valuation puzzle leaves off, spelling out which growth, margin and earnings paths would need to play out for the stock to look meaningfully higher or lower than today’s price on Simply Wall St’s Community page. Rather than relying on a single multiple or model line, each narrative lays out the assumptions behind its view of fair value so you can track those against actual results as they are reported.
One of the top community narratives on Amdocs: 47% undervalued
"As a quantitative fundamental value investor, I seek out for deep value stocks, estimate their fair value, compute their intrinsic price…"
Discover why this Narrative puts Amdocs at 47% undervalued.
Amdocs valuation still leaves one big piece of the puzzle open
Current pricing tells only part of the story for Amdocs, because detailed projections from professional analysts offer a separate view of where earnings and cash flow could head over the next few years. Explore where analysts expect Amdocs to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com