


Lucid Group has seen its share price fall sharply in recent years, prompting a basic question for investors who still follow the story. Is the current US$3.37 price tag meaningfully supported by the electric vehicle maker's sales today?
- Over the past 5 years, Lucid Group's stock has declined 99.2%. This puts the focus squarely on whether the remaining equity value is adequately backed by its revenue base.
- The business model is capital intensive and depends on scaling production efficiently. This can affect how much sales translate into sustainable cash generation that equity holders rely on.
- Your read on Lucid Group is one view; the desks covering it have another. See what analysts think Lucid Group's shares could be worth.
For investors, the debate is whether Lucid Group's current market value is appropriately aligned with the sales it is producing today and what that revenue can realistically support over time.
If you are weighing Lucid Group against other ways to play this theme, it can help to compare it with a broader set of 35 high quality undervalued stocks.
Has Lucid Group Run Too Far on Sales?
P/S works better than earnings based measures for Lucid Group because the business is still loss making and investors tend to anchor on revenue for early stage manufacturers.
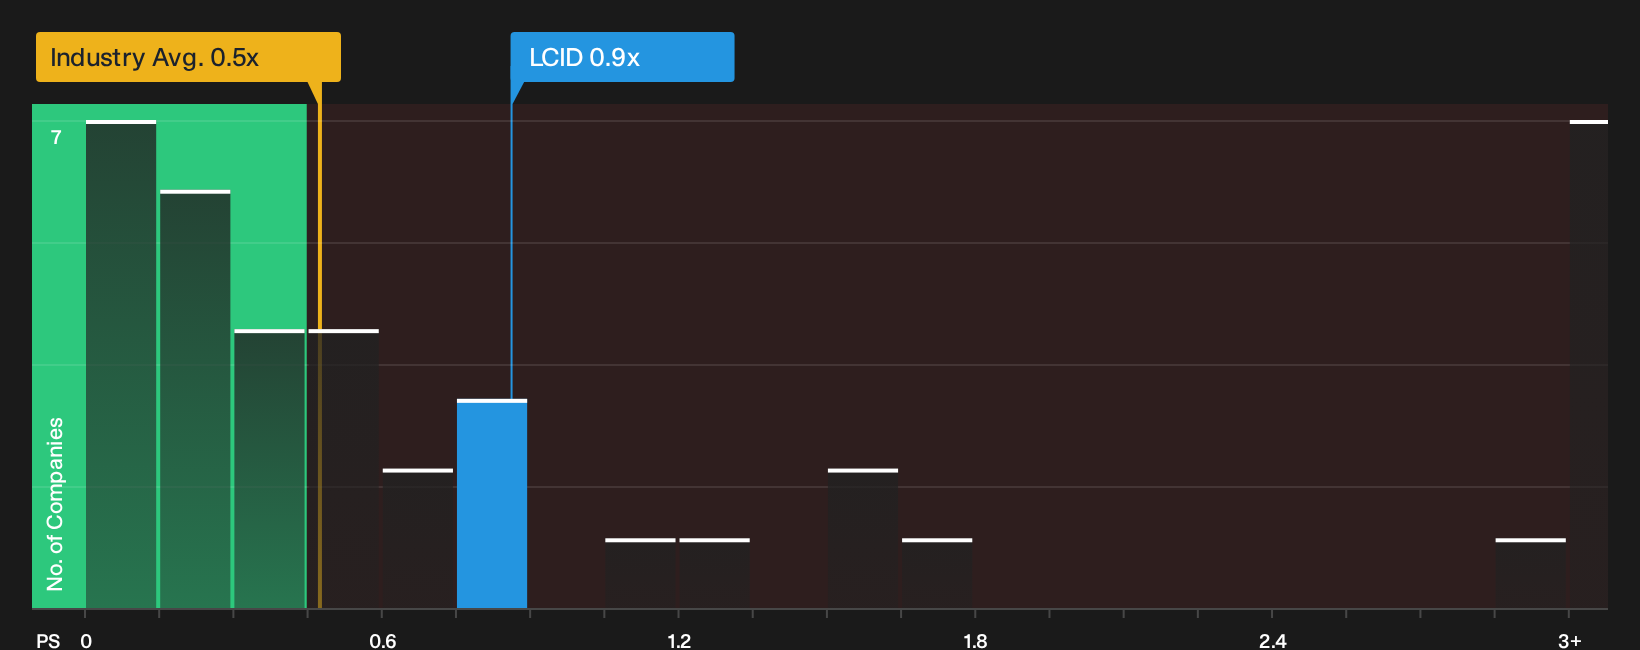
Lucid Group trades on a P/S ratio of 0.9x, compared with an Auto industry average of about 0.5x and a peer group closer to 0.4x. The fair multiple implied by the valuation model is far lower, and the gap is wide enough that the output looks less like a fine tuned target and more like a strong caution signal. The framework is heavily penalising Lucid Group for its current losses, risk profile and the quality of its revenue. This results in the stock screening as overvalued on this P/S lens even before factoring in any future execution questions. Explore the numbers behind Lucid Group's P/S valuation.
The Lucid Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Lucid Group's valuation puzzle leaves off, by spelling out what path for growth, margins and future earnings would need to play out for the stock to be worth materially more or materially less than it is today within the Community page. Rather than relying on a single multiple or model result, each narrative lays out the underlying assumptions so you can compare them with Lucid Group's actual numbers as they are reported over time.
The Lucid Group community is split between a cash discipline turnaround story and a view that demand and execution worries already cap the upside.
Bull case: 54% undervalued
"Lucid Group is executing a shift from heavy investment toward tighter capital discipline, including a planned US$1.4b cash flow improvement in 2026."
Discover why this Narrative puts Lucid Group at 54% undervalued.
Bear case: 12% overvalued
"Bearish analysts expect Lucid Group to keep struggling with weak demand, a narrow premium focus and delayed new platforms, which together maintain heavy cash burn."
Explore why this Narrative puts Lucid Group at 12% overvalued.
Lucid Group’s valuation still hinges on who is in charge
The next question is who is actually steering Lucid Group and how their pay packets line up with your interests, because incentives shape decisions long before the numbers show it. See who runs Lucid Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com