


AST SpaceMobile has seen its share price swing sharply in recent years. This puts a spotlight on a basic question for anyone looking at the stock today: how much of that market value is supported by the company’s book value.
- Over the past 3 years, AST SpaceMobile has delivered a very large share price gain of roughly 7x. This puts substantial weight on whether the current valuation still lines up with what sits on its balance sheet.
- Recent milestones with partners such as AT&T and new regulatory approvals in Brazil can influence expectations for future network build out, capital needs and the pace at which the business might convert heavy investment into assets on its books.
- There is a second opinion on AST SpaceMobile worth weighing. See what analysts think AST SpaceMobile's shares could be worth.
The issue now is whether the current AST SpaceMobile share price is adequately supported by its book value when set against the industry average.
To stress test the same book value question you are asking about AST SpaceMobile across other telecom and satellite players, scan through 41 power grid technology and infrastructure stocks
Has AST SpaceMobile Run Too Far on Book Value?
P/B fits AST SpaceMobile because investors often focus on the value of satellites, spectrum rights and ground assets on the balance sheet when earnings are still developing.
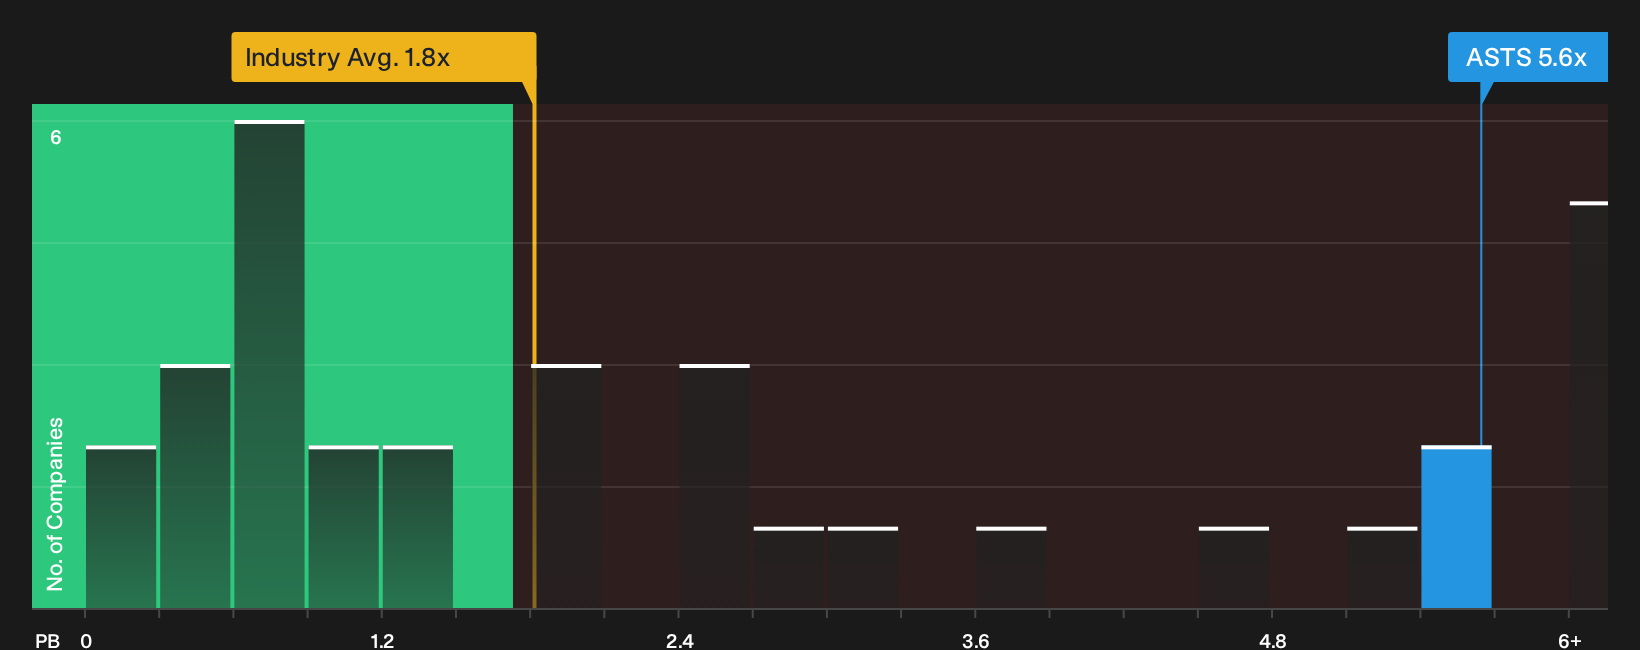
On that measure, AST SpaceMobile trades around 5.6x book value, compared with a Telecom sector average near 1.8x and a peer group that clusters around 12.8x. The stock therefore screens as overvalued against the wider industry on this metric, even though it does not look extreme against more specialised peers that already attract rich asset-based pricing.
Because the recent AT&T handoff milestone has put more attention on AST SpaceMobile’s technology and potential coverage, the current 5.6x P/B reflects a significant level of optimism that today’s heavy investment will result in high quality assets and returns over time. Anyone assessing the shares needs to judge whether that premium to the sector is justified by the company’s progress on spectrum, regulatory approvals and commercial rollout. Explore the numbers behind AST SpaceMobile's P/B valuation.
The AST SpaceMobile Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for AST SpaceMobile pick up where this price to book puzzle leaves off. They spell out which future paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than it is today on the market. Each scenario connects its number to a specific view on how AST SpaceMobile's expansion, cost structure and risk profile could evolve, giving you a reference point you can revisit as fresh information comes through.
Community views on AST SpaceMobile are sharply divided, with some seeing a moonshot opportunity and others highlighting what they view as very stretched expectations.
Bull case: 79% undervalued
"AST’s eventual business model should be a mix of carrier service revenue, gateway infrastructure revenue, government contracts, MNO consulting and integration services…"
Discover why this Narrative puts AST SpaceMobile at 79% undervalued.
Bear case: 12621% overvalued
"A high-risk/high-reward potential, ASTS needs to meet all of the 2026 launch cadence and commercial activation milestones in order for me to consider the full bull case…"
Explore why this Narrative puts AST SpaceMobile at 12621% overvalued.
One more AST SpaceMobile check that belongs beside the book value story
Valuation only tells part of the picture for AST SpaceMobile, since Simply Wall St’s broader review has also flagged specific risk signals that readers may want to weigh for themselves. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com