


ArcBest (ARCB) just put fresh numbers on the table, reporting Q3 2026 earnings that included US$1.21b in sales, US$51.66m in profit and a quarterly dividend of US$0.12 per share.
The strong Q3 release has landed while ArcBest’s share price has been on a tear, with a 1 month share price return of 8.62%, an 80.50% gain year to date, and a 1 year total shareholder return of 115.23%, pointing to powerful momentum rather than a short lived spike.
Scan ArcBest’s momentum against a curated group of logistics and transport peers by checking which companies on the 35 high quality undervalued stocks combine strong fundamentals with pricing that still looks restrained.
After a 115% one year run and a sharp Q3 beat, the question around ArcBest now is simple. Is most of the upside already captured in the share price, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 18% Undervalued
On the widely followed narrative, ArcBest is priced below an estimated fair value of about $169.77, compared with the latest close at $139.29. The gap rests on a view that a leaner network and a richer freight mix can reshape earnings power over time.
Ongoing network and cost-structure optimization, including terminal rationalization, brand consolidation and workforce reductions that are expected to reach about US$40 million in annualized savings by early 2027, positions ArcBest to convert incremental revenue into stronger net margins. The shift toward Asset-Light and Managed Solutions, which is already showing higher shipments per day, lower SG&A per shipment and improving operating income, creates mix potential for ArcBest to grow revenue and expand earnings from a more scalable segment.
See why 4 investors see ArcBest as 18% undervalued.
Result: Fair Value of $169.77 (UNDERVALUED)
Still, if muted freight demand persists or heavier shipments continue to pressure revenue per hundredweight, the bullish ArcBest margin narrative could quickly look optimistic.
Find out about the key risks to this ArcBest narrative.
Another View: ArcBest Looks Expensive On Earnings
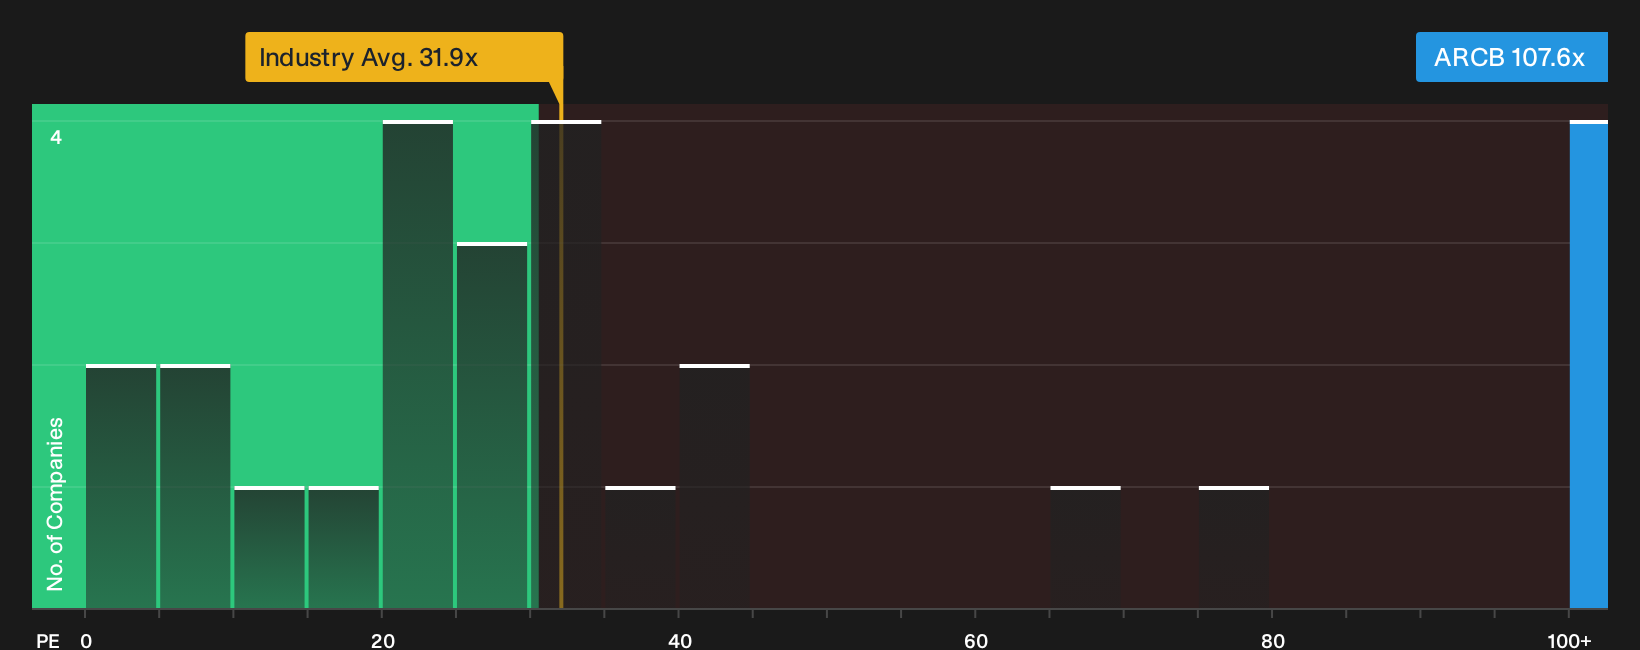
On a simple earnings lens, ArcBest tells a very different story. The stock trades on a P/E of 107.6x, far above the US Transportation industry at 31.9x and a fair ratio estimate of 54.7x, which points to a rich price if earnings do not catch up.
That kind of gap can reward investors if profits accelerate into the current tag, but it also increases the risk that any stumble is punished hard. Which lens do you trust more when both are pointing in almost opposite directions?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around ArcBest is clearly split, and that tension is exactly why the data matters more than the headlines. Move fast; review the full set of risks and potential upsides, and pressure test your own thesis using the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond ArcBest?
If ArcBest has sharpened your focus, do not stop here. Broaden your watchlist with fresh opportunities that match your risk comfort and return goals.
- Target resilient balance sheets and steadier financial profiles by scanning companies in the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricing by checking the 19 high quality undiscovered gems that pair strong fundamentals with limited market attention.
- Prioritize capital preservation and smoother ride potential by reviewing 31 resilient stocks with low risk scores that score well on resilience metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com