


- Rayonier reported third quarter 2026 net income of US$123.3 million versus US$43.2 million a year earlier, with basic and diluted earnings per share from continuing operations at US$0.41 compared with US$0.28.
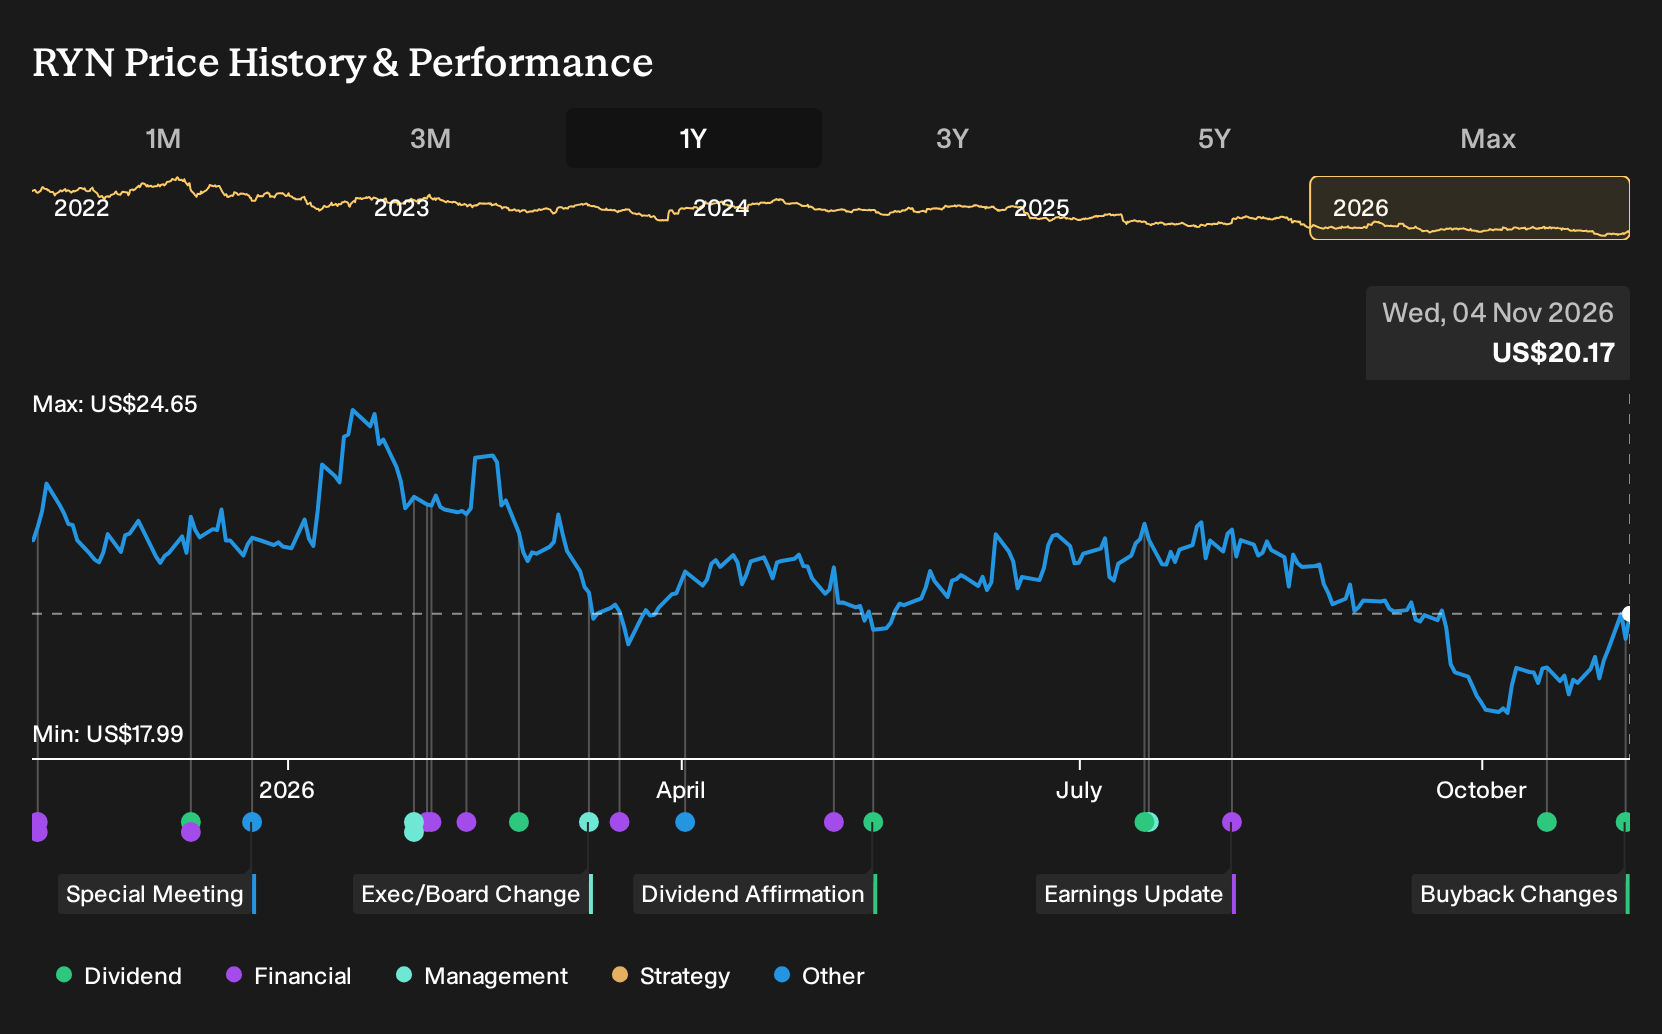
- Alongside higher quarterly profit, Rayonier completed US$233.91 million of buybacks since late 2024 and lifted its repurchase authorization to US$600 million. This reduces the share count and can reshape how future earnings and asset value are distributed among investors.
- We will now look at how Rayonier's third quarter earnings and larger repurchase plan affect its broader investment narrative.
Compare Rayonier's earnings story with a curated 35 high quality undervalued stocks that pair disciplined capital returns with balance sheets built to support future buybacks.
Rayonier Investment Narrative Recap
To own Rayonier, you need to believe its mix of timber, wood products and higher value real estate can turn a large land base into steadier earnings, even when individual years are lumpy. The third quarter result showed much stronger quarterly profit, although nine month net income of US$130 million compared with US$448.5 million a year ago underlines that volatility is still present.
The key short term swing factor remains how quickly merger synergies, real estate projects and land based solutions feed consistently into profit, while stumpage pricing and lumber markets stay choppy. The biggest risk is that pulpwood demand, lumber prices or real estate deal timing soften at the same time. That would make that earnings mix harder to deliver.
The most relevant move for investors here is Rayonier lifting its equity buyback authorization to US$600 million after repurchasing US$233.91 million of stock since late 2024. From July to September alone, it bought 2,800,000 shares for US$59.8 million, taking total completed repurchases to 10,640,511 shares, or 4.87% of the company.
This is material for the story because it intersects directly with the existing catalyst of portfolio optimization and capital allocation. A shrinking share count can amplify whatever progress Rayonier makes on cost synergies, timber economics and high value land sales. It also leans on balance sheet flexibility at a time when earnings have been affected by one off items and softer recent profit margins.
Rayonier's current analyst narrative points to US$2.0b in revenue and US$302.1 million in earnings by 2029, built on an assumed 27.0% yearly revenue growth rate and an earnings increase of about 4x from US$75.8 million today.
Uncover why Rayonier's fair value indicates a 17% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One bullish twist in the Rayonier story is how the most optimistic analysts framed land based solutions before this earnings jump. They were assuming revenue of about US$2.1b and earnings of roughly US$320.3 million by 2029, far above consensus. You can treat this quarter and the larger buyback as fresh data that might influence those narratives in either direction. It is worth comparing several viewpoints before deciding how you feel about Rayonier.
Explore 4 other Rayonier fair value estimates, including one that suggests up to 86% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Rayonier research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Rayonier. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rayonier's overall financial health at a glance.
Looking for more investment ideas beyond Rayonier?
If Rayonier has sharpened your focus on capital allocation and earnings quality, it can help to line it up against other businesses with clear financial stories and different risk profiles using the Simply Wall St Screener.
- For investors who want income that works harder than cash in the bank, scan a curated universe of higher yielding payers through 5 dividend fortresses and see which ones match your tolerance for risk.
- If resilience matters most to you, start with companies that pair sturdy finances with measured volatility by filtering through a 31 resilient stocks with low risk scores that keeps the focus on durability.
- When you want quality without the crowding effect of heavy attention, widen your watchlist using a 19 high quality undiscovered gems that highlights stocks with solid fundamentals yet limited coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com