


Dillard's (DDS) heads into its upcoming Q3 report with attention on a different kind of question. UBS expects the retailer to skip annual guidance and Q4 commentary while still pointing to improving operating trends.
Recent trading tells a mixed story for Dillard's. The share price climbed 4.71% in the last session but is down 2.91% over 30 days, even as the 1 year total shareholder return is 10.64% and the 3 year total shareholder return is about 2.5x. This suggests that long term holders have seen strong gains while short term momentum has cooled ahead of the Q3 update.
Scan for other retailers with similar long term return profiles and fresh momentum setups using our curated list of 19 high quality undiscovered gems.
Dillard's now trades near US$636 after a mixed stretch for the share price and soft recent earnings growth. Does that still leave enough upside potential to justify the risk for new buyers?
Price-to-Earnings of 14.6x: Is it justified?
On simple valuation terms, Dillard's trades on a P/E of 14.6x, which leaves the stock slightly more expensive than close peers even though it sits below the broader US market multiple. With the last close at $636.21 and analyst targets sitting below that level, the current tag assumes investors are comfortable paying up for an established department store story.
The P/E ratio tells you how many dollars investors are paying today for each dollar of current earnings. For a retailer like Dillard's, this measure often reflects expectations around future profit resilience, store productivity and how well management can hold margins in a competitive sector where pricing power can be limited.
Relative comparisons give you more context. The 14.6x P/E is higher than the 14x peer average, which suggests the market is assigning a premium compared to similar US multiline retailers. Against the global multiline retail average of 18.9x, the same multiple looks cheaper, which points to investors valuing Dillard's below the wider sector even though its own return on equity is high at 32.1% and profit margins of 10.3% are above last year. When lined up against the estimated fair P/E of 10.8x, the current valuation looks demanding, since it implies the market is pricing the equity meaningfully above a level that quantitative models indicate it could drift toward over time.
Explore the SWS fair ratio for Dillard's.
Result: Price-to-Earnings of 14.6x (OVERVALUED)
Still, Dillard's faces pressure from soft annual net income growth and a share price already above analyst targets, which leaves little room for disappointment.
Find out about the key risks to this Dillard's narrative.
Another View on Dillard's Valuation
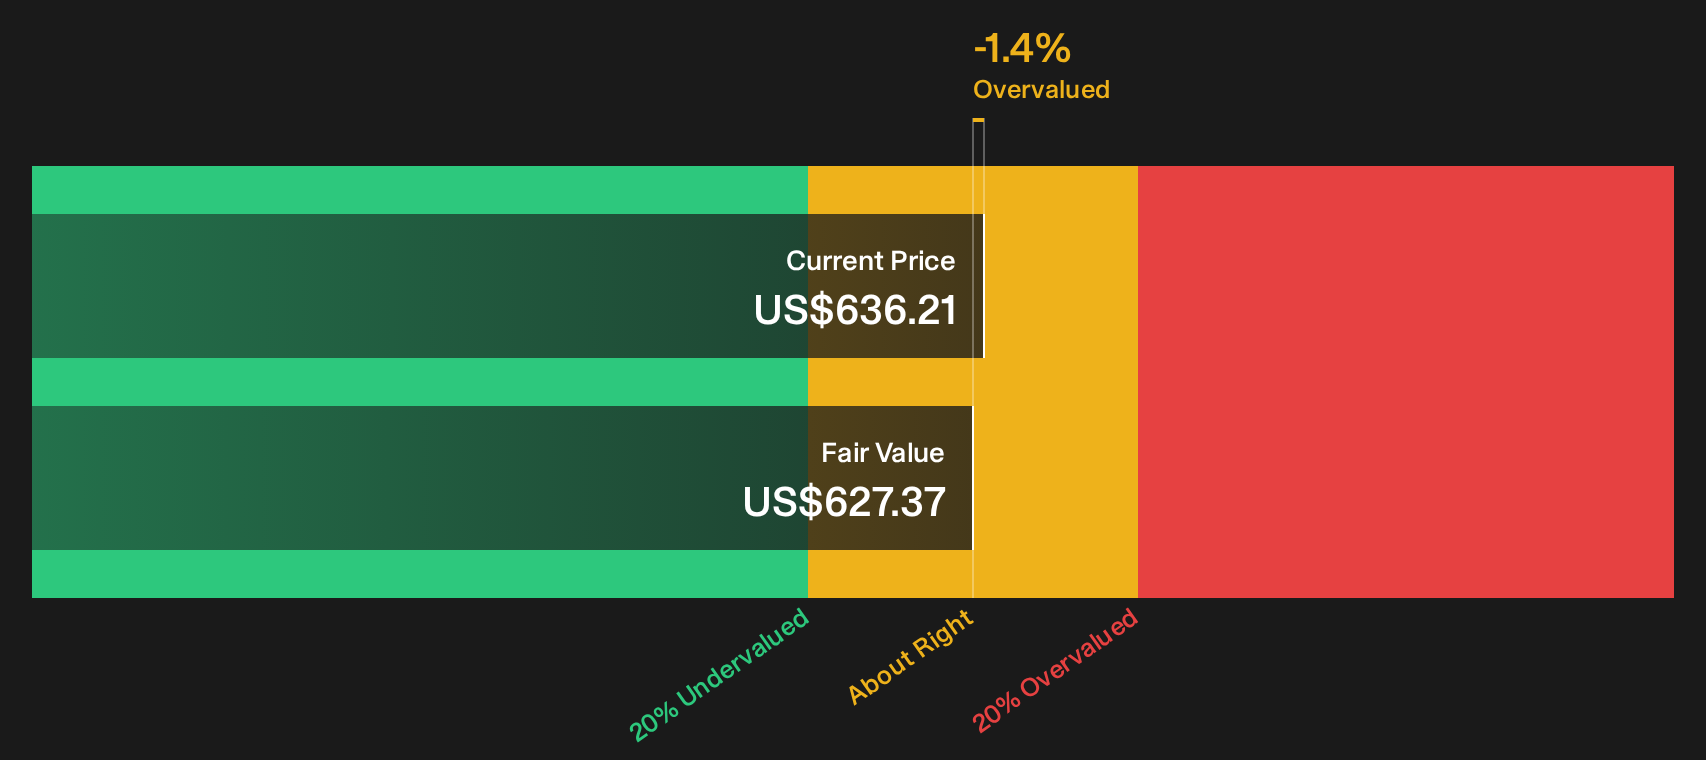
There is a different signal once the SWS DCF model is brought in. On that score, Dillard's estimated future cash flow value sits at $627.37, a touch below the current $636.21 share price. The gap is small, yet it points to a stock that screens as slightly overvalued on this method.
For investors, that kind of narrow premium can feel very different to the richer P/E mark up discussed earlier. Does a valuation that leans only modestly above the modelled fair value justify taking on the earnings and forecast risks already flagged, or does it argue for more patience before committing fresh capital to DDS?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dillard's for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Dillard's valuation can feel unsettling, especially with both pressure points and bright spots in the story right now. Act while sentiment is divided, and weigh the upside against the downside by drilling into the 2 key rewards and 2 important warning signs.
Ready for more investment ideas beyond Dillard's?
Do not stop your research at one retailer. Stretch your opportunity set and pressure test your thesis by comparing it with fresh ideas from the screener.
- Target steadier potential outcomes by checking companies that score well on balance sheet strength and fundamentals through our list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a lower entry point by scanning companies that flag as attractively priced on our value focused 35 high quality undervalued stocks.
- Build a watchlist of under-followed opportunities by scouting the curated universe in our 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com