


On October 27, Heroic Empire Acquisition Limited (HEACU), a SPAC company launched in Hong Kong, submitted an IPO application to the US SEC. It plans to issue 10 million units at $10 per unit, raise 100 million US dollars, and land on the NASDAQ.
Asset “Safety Pad”: $100 Million Trust Fund Builds Credit Endorsements
According to the prospectus, HEACU is a blank check company with no operating results so far. Therefore, a company's ability to commence operations depends on obtaining financing through a public offering of its securities. Through the “adjusted” section of the financial statements, the most notable figure is that total assets reached US$101 million. For a SPAC in the “blind box” phase, this forms the most solid financial fundamentals.
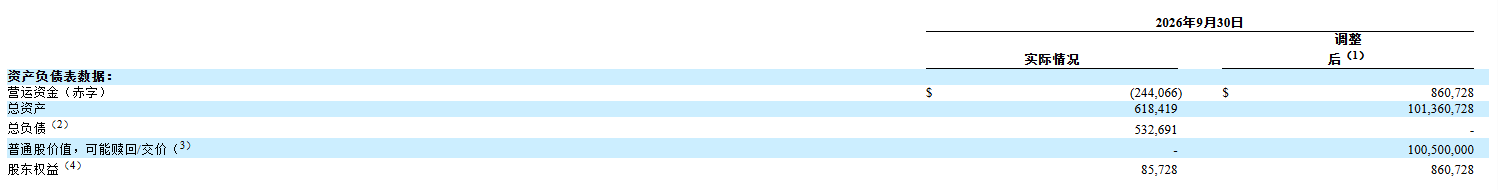
Of this $101 million, up to $100.5 million is classified as “common stock value, likely to be redeemed or traded.” This money represents the full amount of public funds raised by the IPO being held in an independent trust account. This means two core advantages: the first is extremely high downside protection. For public investors, these funds are protected by a strict trust mechanism, and the principal security is extremely high. The second is powerful merger and acquisition ammunition, with a net cash volume of 100 million US dollars. This gives HEACU sufficient bargaining chips and payment capabilities when searching for high-quality targets such as artificial intelligence and new energy in North America and Asia (excluding China).
After excluding restricted trust funds, HEACU's underlying capital structure is also reassuring.
On the one hand, the adjusted total debt of the company is actually zero. This means that after completing the IPO, the company was not burdened with any external debt and achieved a true “lightweight launch”. In the current high interest rate environment, the zero-debt capital structure not only avoids the erosion of financial expenses, but also leaves plenty of room for leverage for possible future debt mergers and acquisitions. On the other hand, the adjusted shareholders' equity was 860,700, which constituted the company's future working capital.
Stepping on the cusp of AI and new energy
As an SPAC that plans to raise 100 million US dollars and focus on mergers and acquisitions for artificial intelligence, biotechnology, TMT, new energy and advanced manufacturing, HEACU's business growth logic is to establish a closed loop of explosive macro-track+investment bank-level management teams.
First, the target industries anchored by HEACU are all in the explosion period of the world's most determined capital and highest capital demand in the next ten years, providing them with a huge pool of high-quality projects.
In the field of AI, prospectus data reveals its astonishing explosive power: global AI spending is expected to reach $2.59 trillion in 2026, surging 47% from 2025, and the core market will reach $3.5 trillion (CAGR 30.6%) by 2033. Among them, the Asia-Pacific region (excluding China) has shown strong structural dividends. Under the catalyst of massive financing in Southeast Asia (over 2.3 billion US dollars in the past year, accounting for more than 30% of total private equity), the Japanese government's public support of up to 65 billion US dollars, and the expansion of more than 4,600 megawatts of data centers, it is currently in a dividend period where infrastructure and generative AI (CAGR 59.2%) explode in both directions. A large number of growing technology companies urgently need to obtain capital and liquidity through SPACs, forming a huge reservoir of mergers and acquisitions.
In terms of new energy and advanced manufacturing, the EV and battery markets in the US and Asia Pacific (excluding China) have shown strong growth. Supported by federal incentive policies, the US is expected to increase its installed renewable energy capacity from 492 GW in 2025 to 678 GW in 2030; its EV battery manufacturing market is expected to increase from US$16.36 billion in 2025 to US$26.10 billion (CAGR 9.8%), and the CAGR for global related testing services is as high as 19%. Meanwhile, in Asia Pacific (excluding China), the region's power generation capacity is expected to increase by about 670 GW by 2030, and the electric vehicle market is also ushering in leaps and bounds, which is expected to soar from $10 billion in 2025 to $182.2 billion (CAGR 28.4%) in 2031.
These “hard technology” companies with heavy assets and high barriers are extremely in need of US dollar capital support for capacity expansion and localized factory construction. At a time when traditional IPO valuations are under pressure or private equity financing is slowing down, there is an urgent need to achieve a curve of listing through SPAC as an efficient path. HEACU uses a trust fund of 100 million US dollars as the “driving force” to accurately enter these booming racetracks, making it easy to capture high-growth assets.
As we all know, the essence of SPAC is “investors use real money to pay for the management team's resume.” HEACU's core growth logic is deeply tied to its more professional management lineup. CEO Mr. Ye Weilun has over 26 years of investment banking experience, particularly as an executive director of mergers and acquisitions at SMBC Nikko Securities (Hong Kong) for nearly nine years and is familiar with the rules of the Hong Kong Stock Exchange; CFO Mr. Mitchell Cariaga has more than 25 years of experience in international capital markets, and has served as a director and audit committee member of many NASDAQ SPACs, including Oak Grove Acquisition Company, and is familiar with SPAC governance.
In addition to “soft power,” HEACU's “hard power” also ensures the implementation of its growth logic. According to the prospectus, through 100 million US dollars of capital held in trust accounts and the ability to flexibly use cash, debt, or equity securities, HEACU can design customized liquidity events according to the target company, or strengthen the target company's balance sheet by reducing the debt ratio. Furthermore, the prospectus emphasizes that targets will be evaluated based on ESG (environmental, social, and corporate governance) requirements. This strategy is easily recognized for long-term funding in the current North American capital market, and is expected to attract more cornerstone investors during the de-SPAC (completion of merger) phase, thereby amplifying the financial benefits of existing capital.
In summary, the prospectus submitted by HEACU showed the capital market a SPAC investment target with a clear structure, a stable chassis, and a very forward-looking SPAC investment target. Judging from the basic financial situation, the “safety cushion” of fully depositing 100 million US dollars into a trust account combined with a pure capital structure with zero debt establishes extremely high downward protection for public investors, and also gives the management team sufficient ammunition for mergers and acquisitions negotiations. Judging from the business growth logic, HEACU has accurately stepped on the global AI and new energy industry explosion cycle, and has a management team with a deep background in cross-border investment banking and practical SPAC experience. Coupled with flexible payment instruments for cash, debt or equity portfolios, and the introduction of ESG standards, HEAC's subsequent target locking and value reshaping journey is worthy of continued attention from the capital market.