


CorVel (CRVL) just posted its second quarter results, reporting revenue of US$267.1 million and net income of US$34.1 million. The business highlighted momentum in workers’ compensation and liability services, along with ongoing investment in technology driven claims tools.
The latest earnings update landed alongside a sharp move in CorVel’s share price, with the stock up 5.74% on the day of the report and showing a 39.67% 90 day share price return. That shorter term momentum comes on top of a 32.92% year to date share price return and a 15.95% 1 year total shareholder return. This indicates that investors have recently been willing to pay more for CorVel’s earnings profile and technology focused claims platform.
Scan other tech-driven claims and healthcare administrators showing similar momentum to CorVel in our hand picked 38 healthcare AI stocks list.
CorVel’s business is clearly getting traction, and the share price has raced ahead to reflect that story. The real question now is whether the current valuation still leaves enough on the table for new buyers.
Price-to-Earnings of 36.3x: Is It Justified for CorVel?
CorVel’s valuation now leans heavily on what investors are willing to pay for each dollar of profit. The latest check puts the stock on a P/E of 36.3x, which the data suggests is lower than similar peers but higher than the broader US Healthcare sector, so the market is assigning a premium to the business while still pricing it below closer comparables.
The P/E ratio shows how much investors are paying today for CorVel’s current earnings. For a services focused healthcare and claims administrator that relies on profitability rather than heavy asset deployment, earnings based valuation is a common yardstick because it ties directly to how efficiently management converts revenue and technology spending into bottom line income.
Against direct peers, CorVel’s 36.3x P/E is described as good value when set against a peer average of 75.7x. That is a wide gap, which points to investors paying much less for each dollar of CorVel’s earnings than for similar companies, even though the firm records high quality earnings, a 28.2% return on equity and 14.5% annual earnings growth over the past 5 years.
Compared with the broader US Healthcare industry, the picture is different. The same 36.3x multiple is considered expensive versus an industry average of 24.8x, which means the stock trades at a clear premium to the wider sector. That kind of mark up often reflects expectations that its technology backed workers’ compensation and liability services can keep delivering stronger profitability than the average healthcare operator.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 36.3x (OVERVALUED)
Still, CorVel’s story can be knocked off course if insurance customers reduce claim volumes or if rivals replicate its technology and squeeze pricing power.
Find out about the key risks to this CorVel narrative.
Another Look at CorVel Using Cash Flows
The P/E story points one way, but the SWS DCF model pushes in the opposite direction. At a share price of $87.38, CorVel is trading above an estimated future cash flow value of $66.64, which implies the cash flow view flags the stock as overvalued.
Our DCF model depends on long term cash generation rather than earnings multiples, so it can paint a stricter picture when expectations are already high. If the cash flow lens is less generous than the P/E, which signal should carry more weight for you as an investor?
Look into how the SWS DCF model arrives at its fair value.
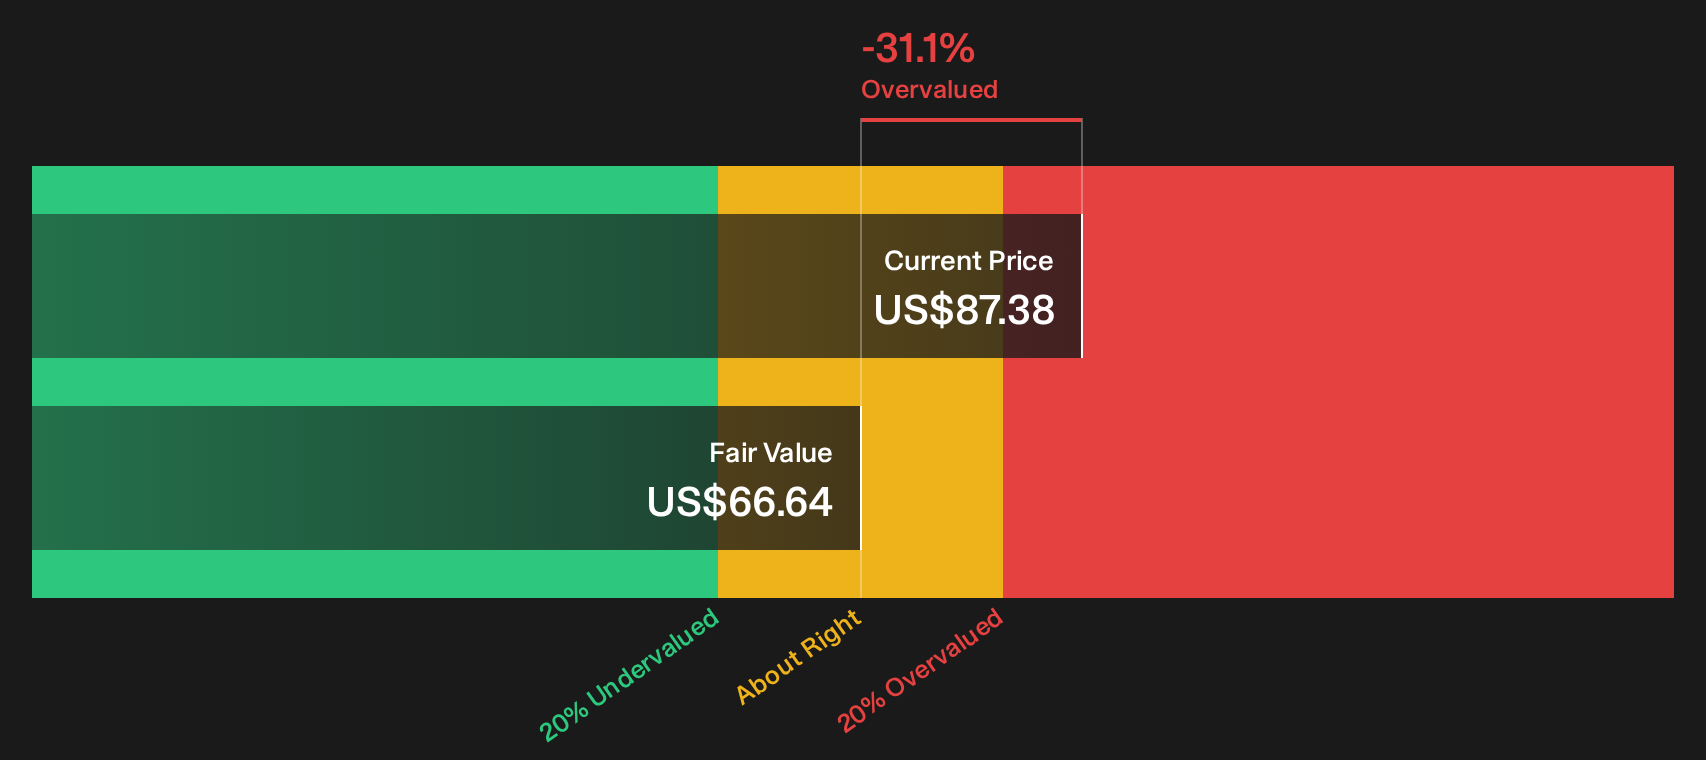
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CorVel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
So where does all this leave CorVel in your eyes? If you want to weigh the upside against the weaker spots using the same data set, start by reviewing the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond CorVel?
If CorVel has sharpened your focus on quality, do not stop here. The right watchlist can change the way you spot opportunities.
- Target potential value opportunities by scanning a 35 high quality undervalued stocks list built around strong fundamentals and pricing that still looks reasonable on current metrics.
- Prioritise resilience and aim to sleep better at night by filtering for 31 resilient stocks with low risk scores that score well on financial strength and business stability.
- Hunt for fresh opportunities before they hit the spotlight by checking a curated set of 19 high quality undiscovered gems that already show solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com