


Coherent (COHR) became a focus for investors after reporting fiscal first quarter results on 4 November, with sales of US$2.37b and net income of US$384.67m from continuing operations.
Despite the strong quarter, Coherent’s recent share price action has been rough, with the stock down 41.5% on a 30 day basis and 41.6% over 90 days. This comes even as the 1 year total shareholder return sits at 44.9% and the 3 year total shareholder return is very large at more than 5x.
Scan how Coherent’s AI infrastructure story compares with other potential breakouts in the photonics and chip supply chain by reviewing the hand picked 53 AI infrastructure stocks.
Coherent’s sharp slide after strong results raises a straightforward question: Is this a reset in how the market prices the business, or simply sentiment whiplash that has distorted the valuation of the same cash flows?
Most Popular Narrative: 50% Undervalued
Coherent last closed at $195.09 while the most widely followed narrative anchors fair value around $387.80. This framing presents the recent selloff as a valuation reset rather than a collapse in the long term story.
The ongoing expansion of AI datacenter infrastructure and high-performance computing is propelling structural growth in demand for advanced optical transceivers (800G, 1.6T, and beyond), optical circuit switches, and related photonics components, which is fueling robust sequential order growth and sustained revenue momentum in Coherent's datacom and communications business.
See why 136 investors see Coherent as 50% undervalued.
Result: Fair Value of $387.80 (UNDERVALUED)
Still, Coherent’s reliance on a few heavyweight customers and heavy capital spending on new facilities could quickly challenge the view that it is 50% undervalued if expectations slip.
Find out about the key risks to this Coherent narrative.
Another View: Coherent Looks Expensive On Earnings
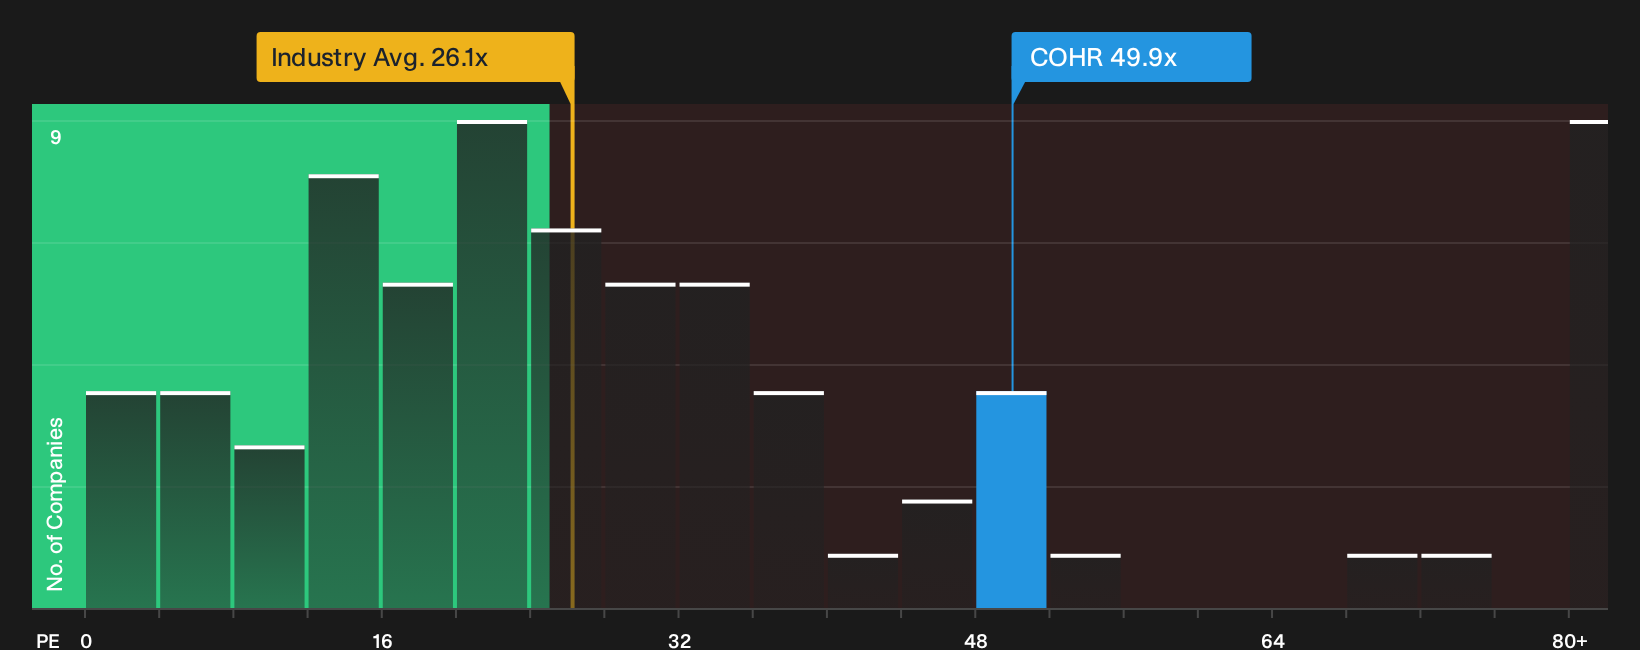
On the flip side of that 50% undervalued story, Coherent trades on a P/E of 49.9x. The US Electronic industry average is 26.1x and the fair ratio for the stock is 43.2x. That premium suggests less of a bargain and more valuation risk if sentiment weakens again.
Put simply, investors are paying much more for each dollar of current earnings than both peers and the fair ratio imply. This could cap upside if the growth narrative cools or execution stumbles. Does that rich multiple reflect justified enthusiasm or expectations that have run ahead of what the business can deliver?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Coherent’s story so far. If you want to move quickly and build your own view, start by weighing the 3 key rewards and 3 important warning signs.
Looking for more Coherent-sized opportunities?
If Coherent has your attention, do not stop with a single ticker. Use the Simply Wall Street Screener to quickly surface focused ideas that match your risk, return, and income goals.
- Target steadier candidates by scanning the 31 resilient stocks with low risk scores that may help anchor a more volatile portfolio.
- Hunt for potential mispriced opportunities using the 35 high quality undervalued stocks before other investors start paying attention.
- Strengthen your income stream and capital base by reviewing the 5 dividend fortresses that combine yield with resilient cash generation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com