


Upwork has seen its share price swing sharply in recent years, and the latest rebound has many investors asking whether the current valuation is properly grounded in its earnings power. After a long period of pressure on the stock, fresh product launches and profitability headlines are forcing a closer look at what today's price is really paying for.
- Over the past 5 years the share price has fallen 76.9%, which puts a lot of weight on whether the market is now recalibrating fairly or still reacting to past disappointments.
- Recent profit and new AI driven services such as Upwork Now, along with the planned integration of WorkMotion, can influence expectations for future margins and the timing of cash generation that feed directly into an earnings based valuation.
- The analysts covering Upwork have run their own numbers. See what analysts think Upwork's shares could be worth.
The issue now is whether Upwork's current share price around US$10.33 is appropriately supported by the earnings the business is producing today and is expected to produce in the years ahead.
If you want a wider view of how other AI focused platforms are priced on their fundamentals, a dedicated screener built around 40 profitable AI stocks that aren't just burning cash is a useful second starting point for research.
Does Upwork Look Fairly Valued on Earnings?
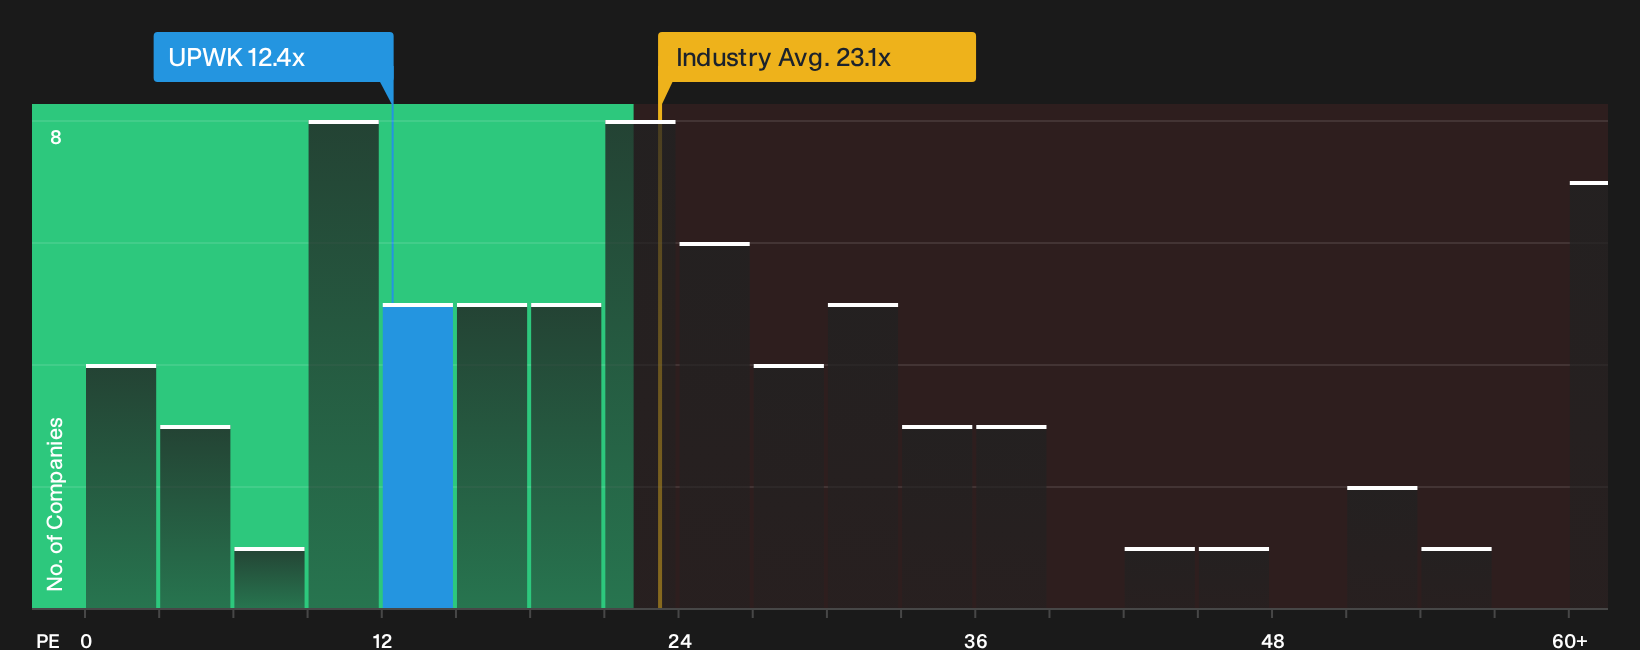
The P/E multiple suits Upwork because the market is laser focused on its shift to consistent profitability. At roughly 12.4x earnings, Upwork trades well below the wider Professional Services industry on about 23.1x and under the peer group average near 20.6x. That points to a discount rating even after the share price move investors have already seen.
Because the current P/E sits just under what a tailored fair multiple model would suggest for Upwork, the ratio hints that the stock is priced broadly in line with what its earnings profile might justify rather than being extremely cheap or expensive. Despite the strong Q3 2026 profit print and raised full year EPS guidance, the market is still valuing Upwork at a lower earnings multiple than many comparable platforms. This leaves the question of whether that gap reflects lingering concern about revenue trends or an opportunity for patient buyers who are comfortable with the risks. Explore the numbers behind Upwork's P/E valuation.
The Upwork Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E debate leaves off and explain which potential paths for Upwork's growth, margins and earnings would need to occur for the stock to appear meaningfully under or overvalued relative to today's price. Each scenario connects a fair value estimate to a specific mix of possible drivers and drawbacks, so you can track over time which storyline most closely aligns with how Upwork's business actually develops on the Community page.
On Simply Wall St, the Upwork community splits between a group that sees meaningful upside and another that thinks the price already bakes in the risks.
Bull case: 25% undervalued
"The move to embed Upwork directly into AI tools like ChatGPT and Claude, along with the MCP server that lets external AI agents trigger jobs on the platform, sets up a new distribution layer where incremental transactions can occur away from the core site yet still contribute to gross services volume and marketplace revenue…"
Discover why this Narrative puts Upwork at 25% undervalued.
Bear case: 29% overvalued
"Although Upwork is growing higher value offerings such as Business Plus and Lifted with rising GSV per active client, total GSV of US$966 million, revenue of US$191.7 million, and 763,000 active clients in Q2 2026 show that higher spend per client has not yet offset pressure from AI automation, macro softness, and weaker SEO driven acquisition…"
Explore why this Narrative puts Upwork at 29% overvalued.
Before acting on Upwork's valuation, one more factor deserves your attention
Upwork's earnings profile and community narratives tell only part of the story, as Simply Wall St's broader checks have flagged specific risk indicators that could materially shape the investment case. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com