


- Advance Auto Parts has set out a multi year turnaround plan that ties daily operational decisions to a margin roadmap. The company is targeting roughly 7% adjusted operating profitability, with guidance pointing to further expansion into 2027.
- The clearer link between distribution efficiency, merchandising moves and future operating margins gives investors more concrete checkpoints to monitor the turnaround's progress.
- We will look at how Advance Auto Parts' investment narrative intersects with this clearer margin roadmap and operational decision making focus.
Compare Advance Auto Parts' turnaround roadmap with other recovery stories and see which peers are already lining up margin expansion targets inside the 35 high quality undervalued stocks.
Advance Auto Parts Investment Narrative Recap
For a shareholder in Advance Auto Parts, the thesis is that today’s operational clean up eventually shows up in steadier margins and more predictable cash generation. The new margin roadmap ties decisions on supply chain, merchandising and store execution directly to the adjusted operating margin target near 7%, giving you clearer yardsticks to watch.
The near term swing factor is whether those operational tweaks lift profitability without further hits from one off items or restructuring costs. The biggest risk right now is that soft DIY demand and any future comp misses keep squeezing net margins, which would make the turnaround look slower rather than broken.
The most relevant update is management’s detailed guidance that links daily choices in distribution, merchandising and Pro mix to a multi year climb in adjusted operating margin, with indications of room for further expansion into 2027. This turns a broad turnaround story for Advance Auto Parts into a set of operational checkpoints.
For you, that means watching whether supply chain consolidation to 15 to 16 distribution centers, hub rollouts and product mix work keep lining up with that margin roadmap. If Pro focused initiatives and owned brand expansion stay on track, the plan retains credibility, even if quarterly results remain choppy while costs from restructuring actions flow through.
Advance Auto Parts' current analyst narrative points to revenue climbing at about 1.5% per year and reaching roughly US$9.0b by 2029, with consensus earnings at US$275.3m in that same year, up from US$109.0m today. This implies an earnings increase of about US$166m over the period.
Uncover why Advance Auto Parts' fair value is essentially in line with its current price.
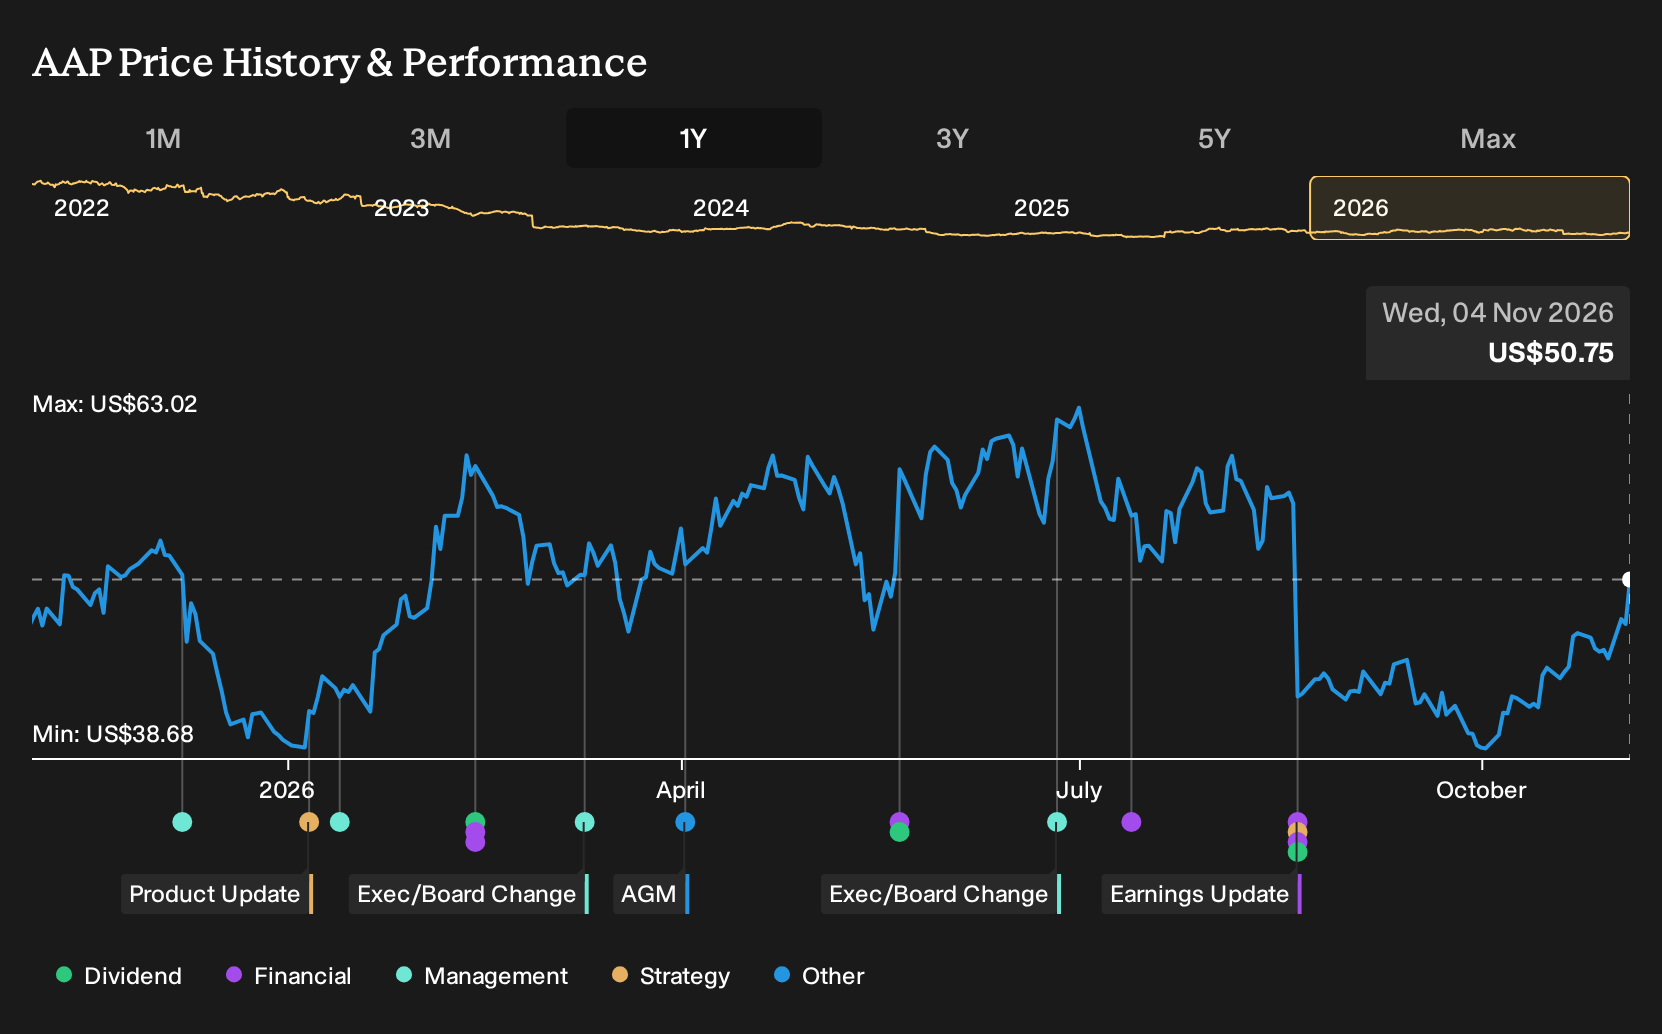
Exploring Other Perspectives
The biggest swing factor in the alternate view on Advance Auto Parts is margin potential. Bullish analysts were pencilling in revenue of about US$9.2b and earnings near US$358.5m by 2029 before this news, far above consensus. That more optimistic path could shift again once the latest margin roadmap is fully reflected in fresh forecasts.
Explore 2 other Advance Auto Parts fair value estimates, including one that suggests as much as 34% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own. Advance Auto Parts has laid out a clearer margin roadmap, and your edge comes from understanding how that plan lines up with risks, rewards and the latest fundamentals.
- A great starting point for your Advance Auto Parts research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Advance Auto Parts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advance Auto Parts' overall financial health at a glance.
Looking For More Investment Ideas Beyond Advance Auto Parts?
Once you have a view on Advance Auto Parts, it can help to put that thesis beside other opportunities so you can judge risk and reward in context. The Simply Wall St Screener is a quick way to build that wider watchlist without wading through hundreds of tickers by hand.
- If you want resilience to be the starting point, focus your research on 31 resilient stocks with low risk scores that combine more defensive profiles with measured exposure to the market cycle.
- For income focused portfolios, compare potential cash return streams across a range of 5 dividend fortresses that may suit different yield and stability preferences.
- If you are hunting for mispriced opportunities with stronger fundamentals, widen your net with a 19 high quality undiscovered gems that might not yet be on every investor’s radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com