


Veeco Instruments (VECO) just released third quarter 2026 results, giving investors fresh detail on how this semiconductor equipment supplier is tracking after a bumpy share price pattern earlier in the year.
Despite the solid third quarter report, Veeco Instruments’ share price has come under pressure recently, with the stock falling 36.1% on a 30 day share price return basis and 30.3% over 90 days. This points to fading short term momentum, even though the year to date share price return of 17.9% and a 1 year total shareholder return of 22.2% still leave longer term holders in positive territory.
Compare Veeco Instruments’ recent pullback with other chip equipment players by scanning our hand picked 53 AI infrastructure stocks, which are exposed to the same long term demand for advanced fabrication capacity.
Veeco Instruments now trades well below its recent highs despite a fresh quarterly update on the table. Is this pullback enough to warrant stepping in now, or does patience lead to a better entry later?
Most Popular Narrative: 41% Undervalued
Veeco Instruments closed at $36.00 while the most widely followed narrative pegs fair value at $61.33. This presents a very different picture of what the shares could be worth if its big projects land as planned.
Ongoing AI and high performance computing build outs are feeding multi year demand for Veeco Instruments annealing and advanced packaging tools. Management points to served markets that they size at about US$1.3b for annealing and about US$1b for advanced packaging by 2030, which directly targets future equipment revenue and earnings.
See why 10 investors see Veeco Instruments as 41% undervalued.
Result: Fair Value of $61.33 (UNDERVALUED)
Still, the Veeco Instruments thesis depends on capacity expansion paying off, and on export controls not stretching out delivery schedules or order timing.
Find out about the key risks to this Veeco Instruments narrative.
Another View: Veeco Instruments On Earnings-Based Valuation
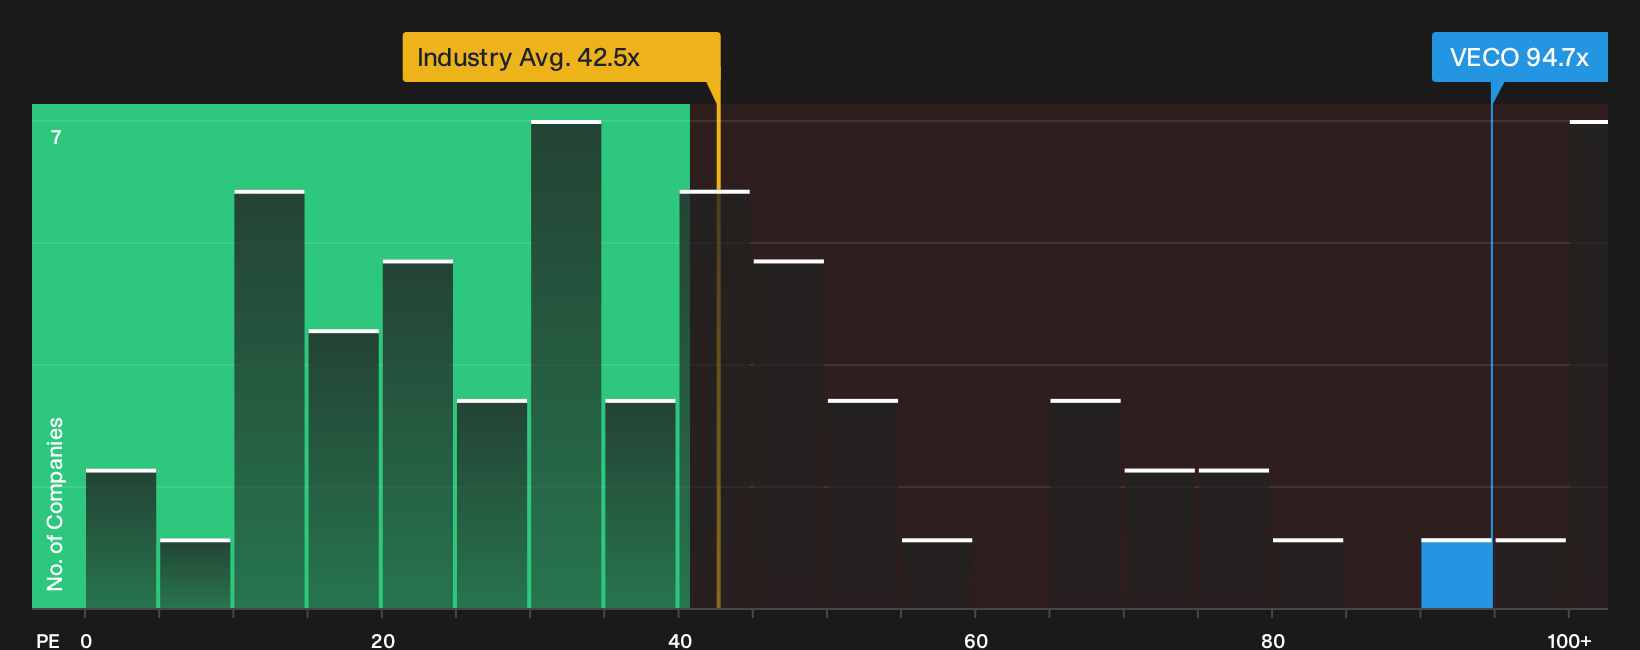
The fair value narrative leans heavily on future earnings potential, yet Veeco Instruments currently trades on a steep P/E of 94.7x. That is higher than the US Semiconductor industry at 43.5x, above peers at 37.7x, and ahead of a fair ratio of 88.5x that the market could move toward.
This gap points to valuation risk. If sentiment cools or forecasts reset, the share price could drift toward that lower fair ratio long before any longer term growth story has time to play out.
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Veeco Instruments is split, with enthusiasm for the AI build out story sitting alongside clear worries about valuation and execution risk. Act while the data is fresh and decide where you stand by weighing its 2 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Veeco Instruments?
If Veeco Instruments has your attention, do not stop here. Broader context often reveals better risk reward trade offs and fresh opportunities others overlook.
- Target resilient cash generators and filter for sturdier balance sheets using a focused list of solid balance sheet and fundamentals (24 results) that keeps fragile businesses off your radar.
- Hunt for potential mispricings and compare Veeco Instruments with a curated 35 high quality undervalued stocks that highlights financially stronger candidates the market may be overlooking.
- Prioritise steadier sleep at night potential and scan a 31 resilient stocks with low risk scores tailored to investors who want fewer surprises in their portfolios.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com