


- Cirrus Logic reported fiscal Q2 2027 sales of US$559.46 million with net income of US$114.74 million, along with an expanded buyback authorization that takes total capacity to US$1b.
- The business paired earnings that exceeded analyst expectations with softer Q3 revenue guidance of US$510 million to US$570 million. This highlights near term demand uncertainty despite sizable share repurchases.
- We will look at how Cirrus Logic's cautious revenue outlook sits alongside its cash returns and affects the broader investment narrative.
Compare Cirrus Logic's buyback-fueled story with other chip designers returning cash to shareholders by scanning the list of solid balance sheet and fundamentals (24 results) for potential peers facing similar guidance trade offs.
Cirrus Logic Investment Narrative Recap
To own Cirrus Logic, you need to be comfortable with a story built on high performance mixed signal products tied closely to flagship smartphones, while diversification into PCs and industrial uses builds in the background. The latest quarter keeps that thesis intact. Revenue of US$559.46 million and net income of US$114.74 million were broadly steady year on year, so the core engine is still working.
The near term swing factor is demand from a small set of large handset customers. Management’s Q3 revenue outlook of US$510 million to US$570 million underlines that visibility is not perfect, yet it does not radically alter the bigger catalyst of broader mixed signal adoption. Customer concentration remains the main risk if any large account trims volumes.
The most immediate announcement tied to this earnings release is the expansion of Cirrus Logic’s equity buyback authorization to US$1 billion. From June 28 to October 30, 2026, the firm retired 1,162,757 shares for US$144.1 million, completing 3,258,573 shares or 6.39% under the prior plan. That is a meaningful reduction in share count over a relatively short stretch.
For you as a shareholder, that capital return only matters if the business keeps executing on its product roadmap and manages revenue swings from the smartphone segment. The enlarged authorization signals the board’s willingness to keep using cash flow for repurchases alongside ongoing investment in audio, camera controllers and industrial mixed signal products that tie into the next leg of catalysts.
Cirrus Logic's analyst narrative indicates forecast revenue of US$2.2b and earnings of US$385.2 million by 2029, based on an assumed 2.1% yearly increase in sales and an earnings decline of about US$45.4 million from US$430.6 million today.
Uncover why Cirrus Logic's fair value indicates a 22% potential upside to its current price, which could narrow quickly.
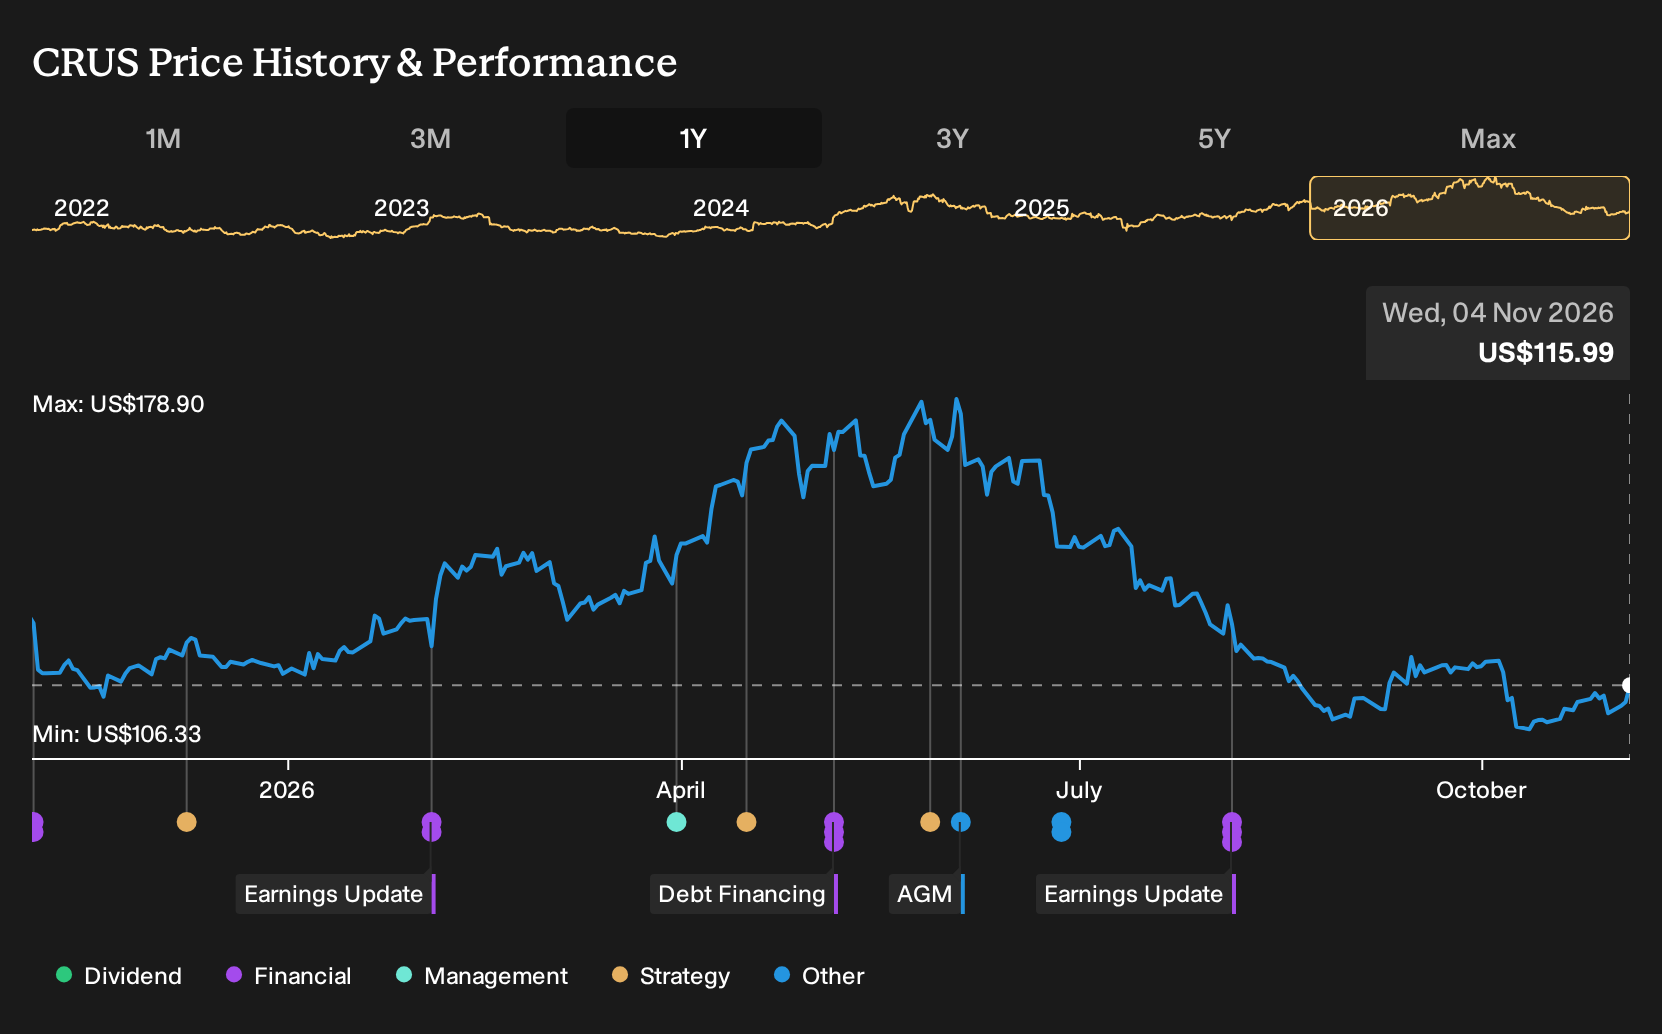
Exploring Other Perspectives
One alternate view on Cirrus Logic leans heavily on the buyback and cash position as the real catalyst. The most optimistic analysts were working off expectations of about US$2.3b in revenue and US$425 million in earnings by 2029, before this earnings miss on Q3 guidance, so their upbeat story may shift as new information beds in.
Explore 7 other Cirrus Logic fair value estimates, including one that suggests as much as 118% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cirrus Logic research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cirrus Logic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cirrus Logic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cirrus Logic?
If the Cirrus Logic story has sharpened your thinking about risk, cash returns and forecasts, use that same framework to scan a wider opportunity set with the Simply Wall St Screener.
- For investors hunting for potential mispricings backed by solid fundamentals, start by reviewing the 35 high quality undervalued stocks that fit those tighter quality filters.
- If capital preservation and smoother ride matter most to you, focus on companies in the 31 resilient stocks with low risk scores and compare how their risk profiles stack up against Cirrus Logic.
- When you want to broaden the watchlist with fresh ideas that are not heavily followed, scan the 19 high quality undiscovered gems and see which businesses merit a deeper look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com