


Why Hamilton Lane’s latest earnings and dividend move matter
Hamilton Lane (HLNE) just packed three key developments into one week, with fresh quarterly earnings, a higher dividend, and a new data partnership with FactSet giving investors more to unpack around the stock.
Recent trading shows how quickly sentiment around Hamilton Lane can shift. The 1-day share price return of 7.18% and 7-day gain of 14.83% followed the earnings beat, dividend increase and FactSet agreement. However, the share price remains down 30.49% year to date and the 1-year total shareholder return is still lower by 21.55%. The 3-year total shareholder return of 10.86% points to a more resilient longer-term record.
Scan how Hamilton Lane’s earnings momentum, dividend signal and data partnership compare with a hand-picked 35 high quality undervalued stocks that shows similar quality traits at different price points.
Hamilton Lane now trades at a steep discount to both analyst targets and some estimates of fair value after a sharp bounce. Is that a market overreaction, or a warning that the caution is warranted?
Most Popular Narrative: 45.9% Undervalued
Against a last close of $94.99, the most followed valuation narrative for Hamilton Lane points to a fair value of $175.64 and describes the recent rebound as only a partial catch-up in a wider reset.
The market is staring at the second clock, the unpredictable one, and pricing the whole machine as unreliable. Meanwhile assets under management and advisement have crossed $1.1 trillion, free cash flow is up 45%, and annual capex remains almost comically small relative to the cash this business throws off.
See why 2 investors see Hamilton Lane as 46% undervalued.
Result: Fair Value of $175.64 (UNDERVALUED)
Still, the Hamilton Lane story can change quickly if incentive fees slow sharply again or if fundraising pressure starts to affect fee-based revenue.
Find out about the key risks to this Hamilton Lane narrative.
Another View: What Hamilton Lane’s P/E Is Really Saying
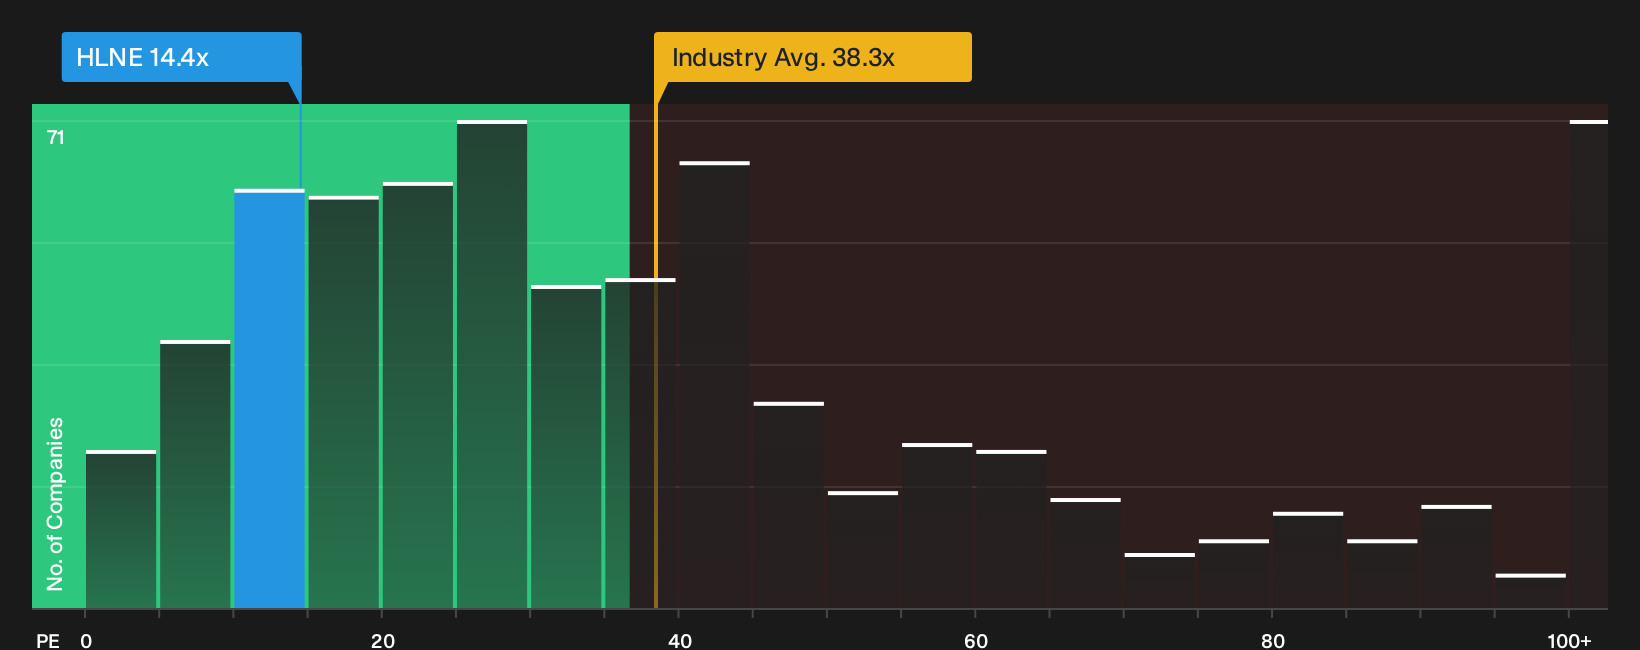
Valuation based on future cash flows paints one picture for Hamilton Lane. The simple P/E ratio tells a more mixed story. The stock trades at 14.4x earnings, below the US Capital Markets industry on 37.1x and below peers on 18.3x, yet slightly above its own fair ratio of 14.1x.
That mix suggests investors are paying a small premium to the fair ratio for Hamilton Lane, while still getting a discount to the wider group. The question is whether that gap reflects a margin of safety or lingering concern about how lumpy earnings and one off items could reshape those multiples over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Hamilton Lane can either paralyze you or push you to test the numbers yourself and decide what really matters. If you want a quick way to size up both the bright spots and the pressure points in one place, start with the 3 key rewards and 1 important warning sign.
Looking for more Hamilton Lane sized investing ideas?
If Hamilton Lane has sharpened your focus, do not stop here. The next opportunities often sit just outside the names you already know best.
- Chase value by lining up Hamilton Lane against a curated 35 high quality undervalued stocks that share strong fundamentals at very different price tags.
- Strengthen your defensive side by checking a list of solid balance sheet and fundamentals (24 results) where resilient finances help companies stay prepared for tougher conditions.
- Spot earlier opportunities by scanning a 19 high quality undiscovered gems that combine quality metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com