


Envista Holdings (NVST) is back in focus after reporting third quarter 2026 results that showed sales of US$691.5 million and a shift from a net loss to US$508.3 million in profit.
The earnings release helped reignite interest in Envista Holdings, with the share price jumping 9.77% on the day and delivering a 13.58% 7 day share price return. The 1 year total shareholder return of 34.94% contrasts with a 5 year total shareholder return that is still down 36.91%.
Scan beyond Envista Holdings' earnings rebound and explore other potential healthcare opportunities through a curated list of 38 healthcare AI stocks with AI exposure in the sector.
The sharp move in Envista Holdings after the earnings swing has already rewarded anyone who was in early. The real tension now is whether to commit at this new level or wait for a more forgiving valuation entry.
Most Popular Narrative: 8% Undervalued
Envista Holdings closed at $27.19 versus a widely followed fair value estimate of $29.69. This frames the latest earnings rebound as only part of a bigger story driven by long term cash flow assumptions and capital returns.
Ongoing cost reductions (notably 15% G&A reduction in the first half), coupled with operational optimization and unit cost reductions (especially within Spark), are catalysts for sustained margin improvement and future EPS growth, as scale and digital adoption continue.
See why 3 investors see Envista Holdings as 8% undervalued.
Result: Fair Value of $29.69 (UNDERVALUED)
Still, Envista Holdings faces pressure from China volume-based procurement and ongoing tariff costs, which could limit the margin progress that underpins the undervaluation narrative.
Find out about the key risks to this Envista Holdings narrative.
Another View On Envista Holdings Valuation
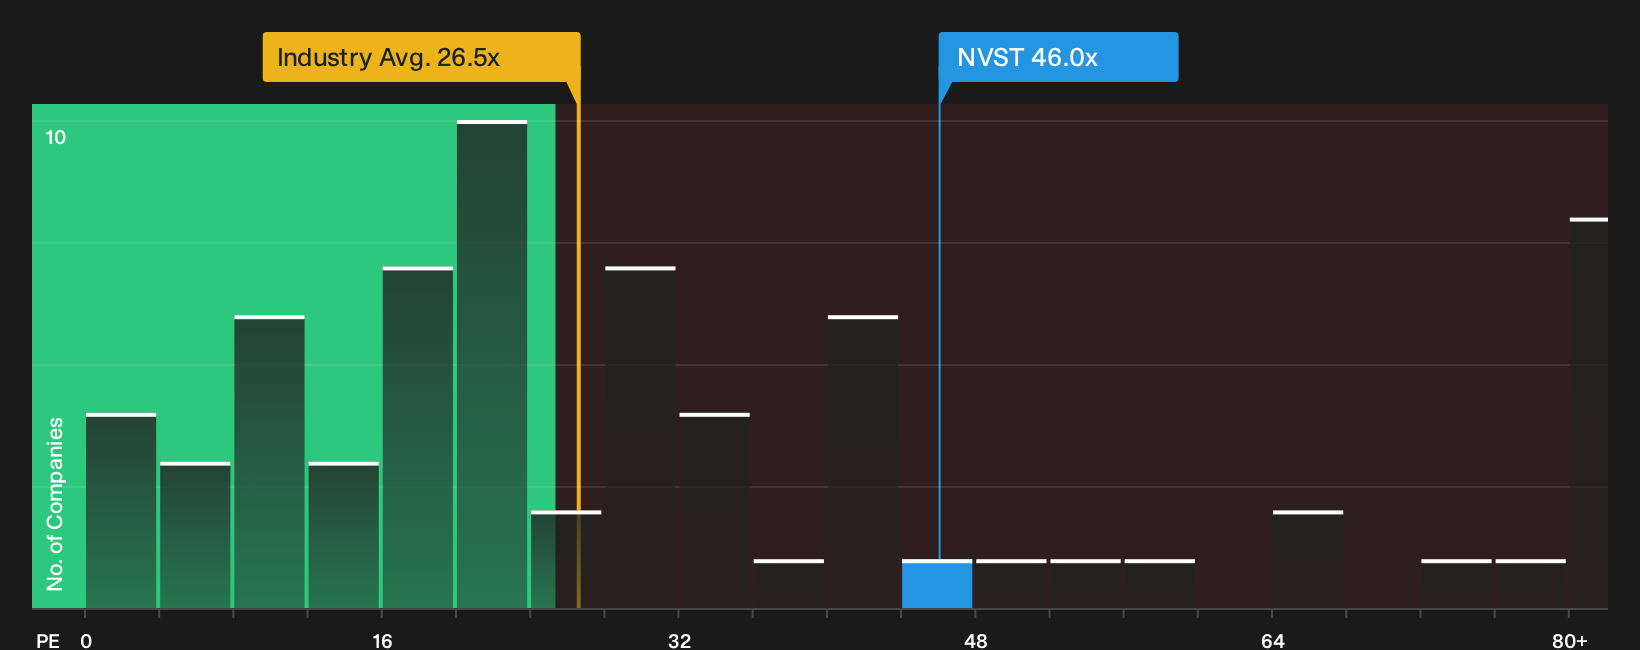
On the flip side of that fair value of $29.69, Envista Holdings trades on a P/E of 46x, versus 34.7x for peers, 23.9x for the wider US Medical Equipment group, and a fair ratio of 28x. That premium loads more execution risk onto anyone buying this story.
This raises a simple question: Is Envista Holdings priced for a smooth margin ramp, or are expectations already running ahead of what the business can reasonably deliver?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment split on Envista Holdings after this rebound, now is a useful moment to move fast, test the numbers, and shape your own thesis. To see what the optimism is built on, start with the 3 key rewards.
Looking for more investment ideas beyond Envista Holdings?
If Envista Holdings has sharpened your thinking, do not stop here. Use the Simply Wall St Screener to quickly scan fresh opportunities that fit your style.
- Target higher potential upside by reviewing a curated set of under-the-radar bargains through the 35 high quality undervalued stocks.
- Shield your portfolio from shocks by filtering for sturdier balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Spot overlooked opportunities early by tracking companies with strong fundamentals via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com