


CF Industries Holdings has nearly doubled shareholders' money over the past five years, yet the core question now is whether the current share price still lines up with what its earnings can justify. After a strong multi‑year run and a softer recent patch, the stock invites a closer look at how much of its profit power may already be reflected in today's valuation.
- Over 5 years, CF Industries Holdings has returned 97.0%, which puts real weight on whether its current earnings base can support that kind of re-rating.
- The new Front-End Engineering Design study in Ontario for a diesel exhaust fluid expansion may support expectations for longer term earnings from better use of existing assets and added capacity, while also implying future capital spending commitments.
- Your read on CF Industries Holdings is one view; the desks covering it have another. See what analysts think CF Industries Holdings's shares could be worth.
The issue now is whether CF Industries Holdings' current share price is adequately supported by the earnings that investors are paying for today.
If you are weighing CF Industries Holdings against other businesses where earnings power is central to the story, it can help to compare it with companies surfaced by 35 high quality undervalued stocks.
Is CF Industries Holdings a Bargain on Earnings?
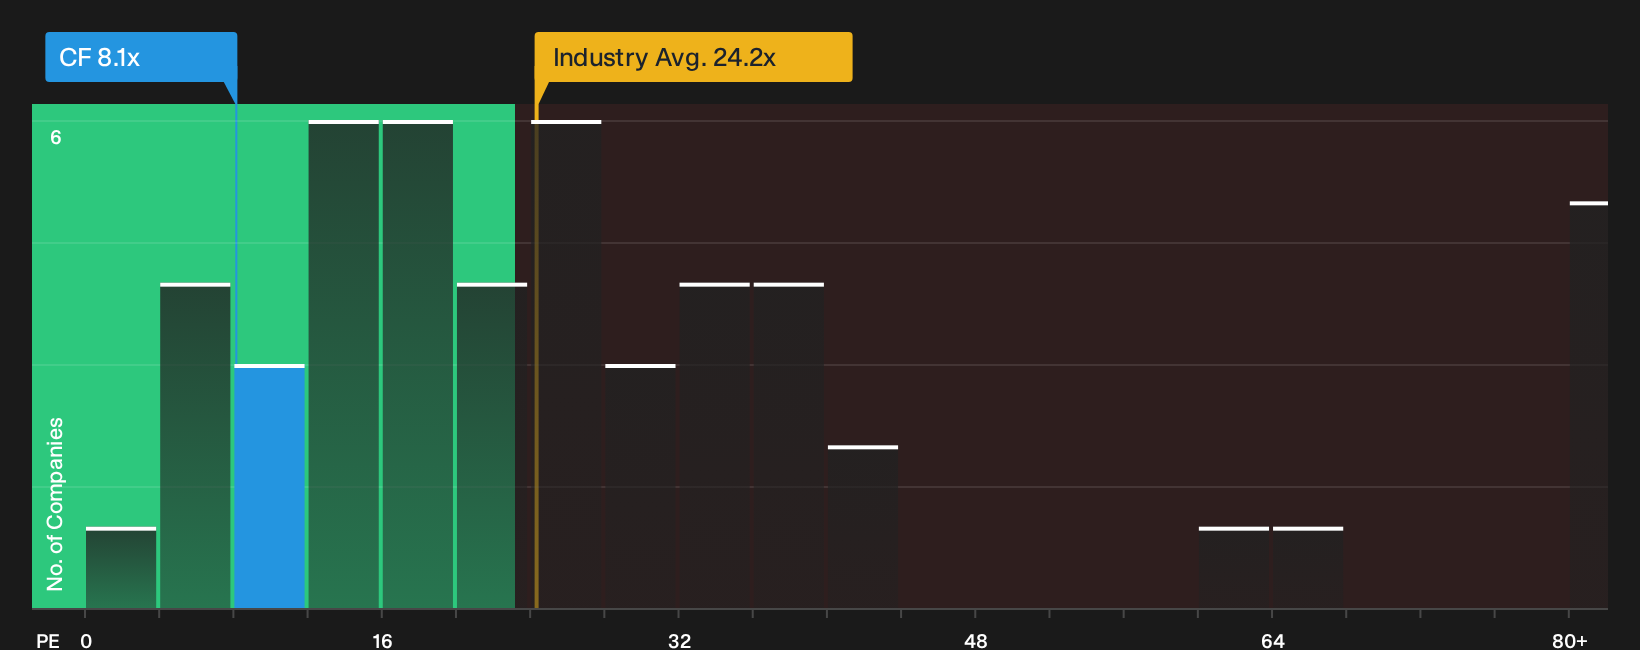
The P/E ratio fits CF Industries Holdings because earnings are a key driver for a mature, capital intensive fertilizer producer. The stock currently trades on a P/E of 8.1x, which is well below the Chemicals sector average of 24.2x and the broader peer group at about 28.9x. On the modelled fair benchmark for a business with CF Industries Holdings' profile, that level screens as undervalued rather than fully priced.
Because the new diesel exhaust fluid expansion study highlights potential capital commitments, the low earnings multiple suggests the market is not paying up for that future optionality yet. For an investor weighing CF Industries Holdings against higher multiple chemical producers, the gap on P/E raises the question of whether the discount reflects caution on the cycle or an opportunity if earnings stay resilient. Explore the numbers behind CF Industries Holdings's P/E valuation.
The CF Industries Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for CF Industries Holdings leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the current valuation to look either too low or too rich. Rather than rely on a single multiple or model output, each narrative lays out the assumptions behind its own view of fair value, so you can track those inputs against reported results over time on the Community page.
CF Industries Holdings draws a split crowd, with some investors seeing more upside left in the nitrogen story while others argue most of the good news is already reflected in the price.
Bull case: 13% undervalued
"The build out of higher margin offerings such as low carbon ammonia volumes that already carry premiums of more than US$20 per ton..."
Discover why this Narrative puts CF Industries Holdings at 13% undervalued.
Bear case: 6% overvalued
"Expansion of low carbon ammonia projects such as Blue Point depends on contract for difference support, long term carbon policy in markets like Europe and Japan..."
Explore why this Narrative puts CF Industries Holdings at 6% overvalued.
Before acting on CF Industries Holdings' valuation, there is one more piece to check
Numbers only tell part of the story, since the people setting priorities and the way their pay is structured can heavily influence how CF Industries Holdings is run over time. See who runs CF Industries Holdings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com