


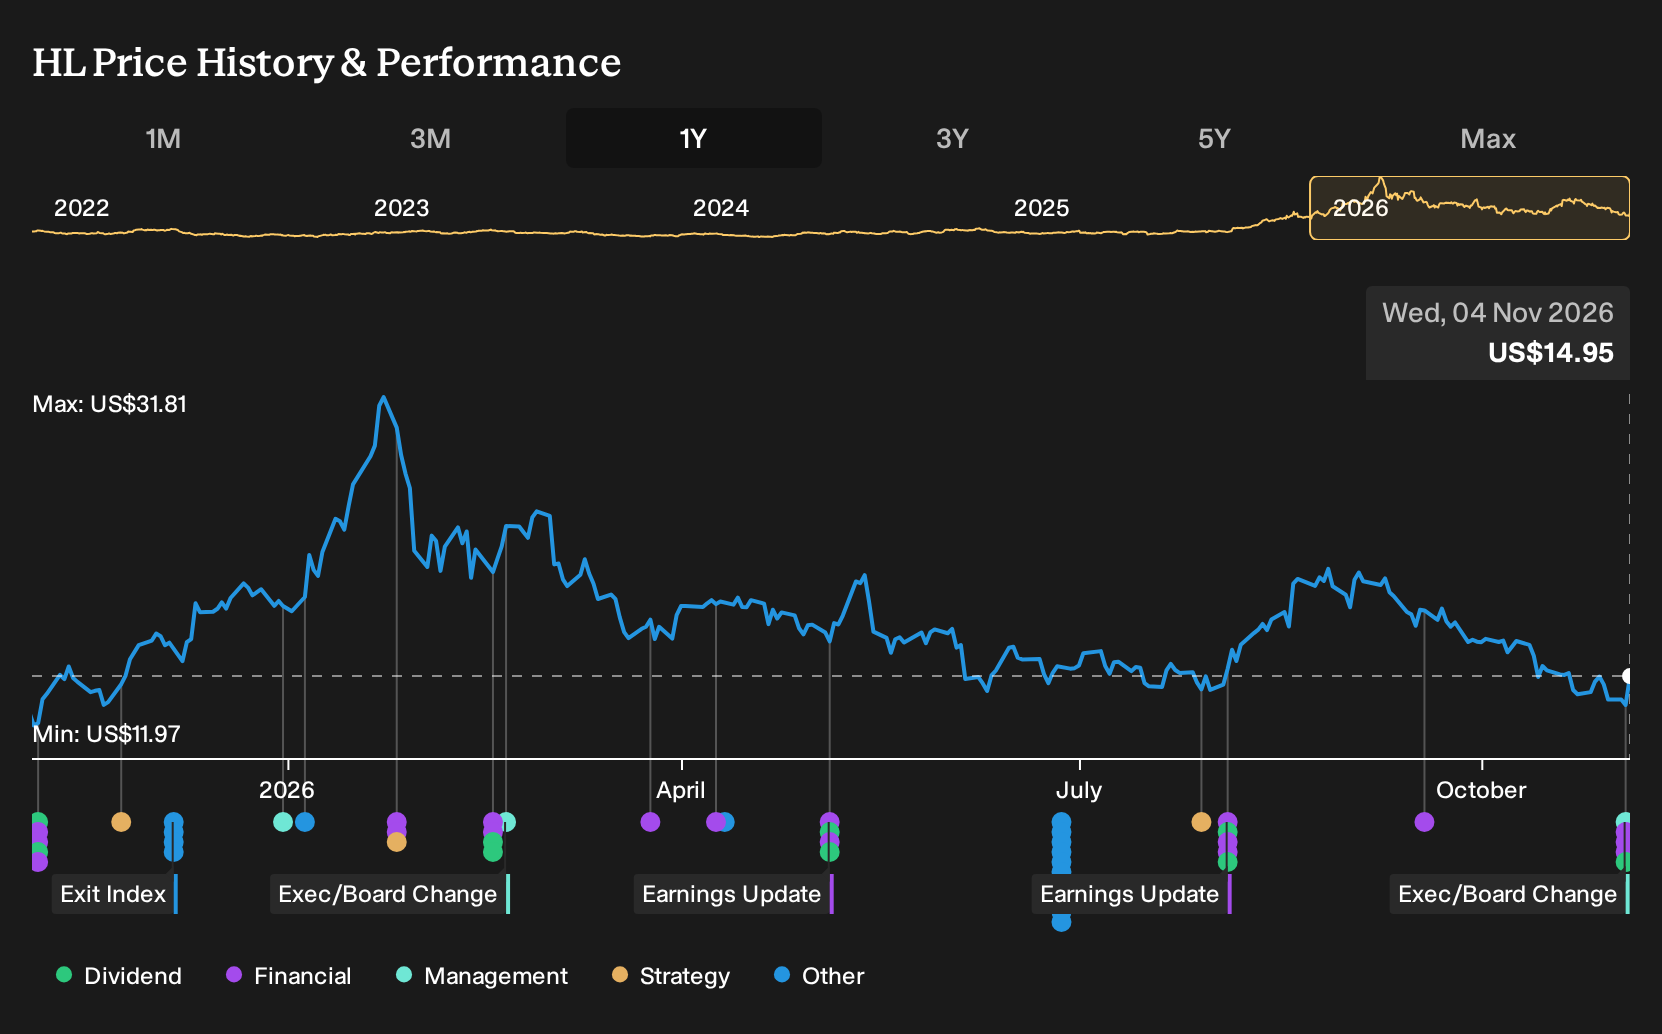
- Hecla Mining reported third quarter 2026 sales of US$394.82 million and net income of US$149.6 million, along with record free cash flow from continuing operations of US$151 million and reaffirmed dividends.
- Management raised the low end of 2026 silver production guidance and reduced capital investment plans, which suggests tighter cost control and more confident planning around future output.
- The next step is to examine how Hecla Mining's stronger free cash flow profile could reshape the investment narrative that existed before this update.
Hecla Mining Investment Narrative Recap
To own Hecla Mining, you need to believe the business can keep turning a silver weighted portfolio into consistent free cash flow even as individual mines mature and regulatory demands rise. The latest quarter points to that possibility. Record free cash flow and reaffirmed dividends suggest the current asset base is paying its own way rather than leaning heavily on external funding.
The near term swing factor is whether Hecla can sustain cash generation while managing ore grade pressures and future capital needs at projects like Keno Hill and Casa Berardi. Management raising the low end of silver guidance and trimming capex helps that story. The key operational risk remains higher future permitting, environmental and tailings costs, which could eat into that cash cushion.
The most relevant move for this earnings beat is Hecla Mining raising the low end of its 2026 silver production guidance to 15.3 million ounces while keeping the top end at 16.1 million ounces. That sits alongside reiterated gold guidance from Greens Creek and comes in the same breath as lower capital spending plans. The combination ties production expectations more tightly to the current asset base and mine plans.
For you as a shareholder, that guidance update matters because it frames the next few quarters of catalysts. Execution now hinges on delivering that silver range while preserving unit costs and keeping Keno Hill investment from creeping higher than planned. Any slippage in tonnage, grades or regulatory timing would directly affect how durable this stronger free cash flow profile really is.
Hecla Mining's current analyst narrative points to forecast revenue of US$1.6b and earnings of US$449.7 million by 2029, based on an assumed yearly revenue decline of 3.3%. That outlook implies earnings falling by about US$102.8 million from US$552.5 million today, rather than growing over the forecast period.
Discover how Hecla Mining's fair value indicates a 48% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view leans heavily on valuation risk. Before this earnings surprise, the most optimistic analysts were already working off revenue of about US$1.7b and earnings of US$481.0 million by 2029, paired with a P/E of 55.7x. However, opinions differ widely and may shift again as the latest Hecla Mining results are digested.
Explore 4 other Hecla Mining fair value estimates, including one that suggests as much as 106% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hecla Mining research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hecla Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hecla Mining's overall financial health at a glance.
Looking for more Hecla Mining style ideas?
If the Hecla Mining update has you rethinking where free cash flow, balance sheet resilience and income potential fit in your portfolio, it can help to line this story up against peers and completely different sectors using the Simply Wall St Screener.
- For investors who want potential mispricing backed by fundamentals, scan a focused set of 35 high quality undervalued stocks that pair quality metrics with a discount to intrinsic value estimates.
- If capital preservation sits high on your checklist, filter for companies with sturdier finances through our list of solid balance sheet and fundamentals (24 results) and compare how their leverage and liquidity stack up.
- For those hunting ideas that are not already crowded trades, cast a wider net across 19 high quality undiscovered gems where underlying business quality is supported by cleaner financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com