


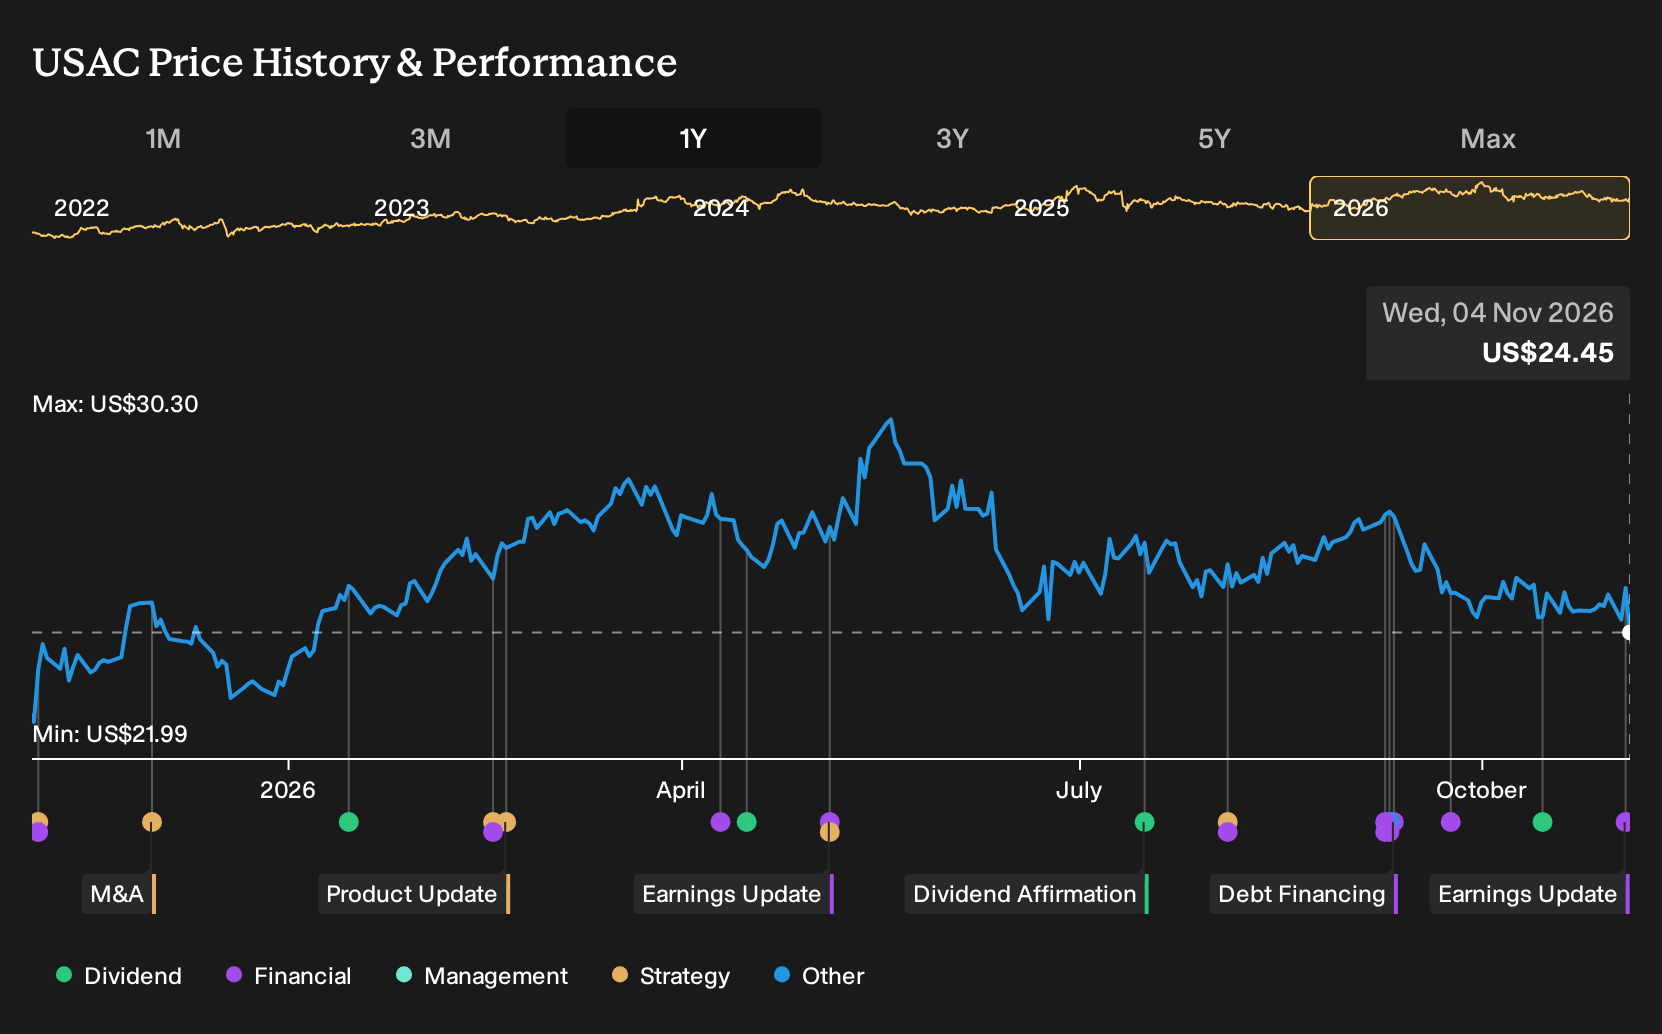
- USA Compression Partners reported third quarter 2026 revenue of US$357.19 million, net income of US$47.35 million, and earnings per unit of US$0.33, alongside record operational metrics and updated full year guidance for adjusted EBITDA of US$770 million to US$780 million.
- The partnership combined record revenue generating horsepower and revenue per horsepower with a US$600 million senior notes issuance and an unchanged US$0.525 cash distribution, indicating management focus on capacity, liquidity, and payout stability while contracting a significant share of 2027 horsepower in advance.
- We will now look at how USA Compression Partners' record revenue generating horsepower and stronger earnings influence the existing investment narrative.
Scan beyond USA Compression Partners and line up other income-focused infrastructure plays using the hand picked 5 dividend fortresses as a starting universe for your watchlist.
USA Compression Partners Investment Narrative Recap
Owning USA Compression Partners is essentially a bet that tight large horsepower markets and steady U.S. gas demand keep its fleet highly utilized, and that technology and scale offset rising costs. The latest quarter supports that view, with record revenue generating horsepower, higher revenue, and stronger earnings putting more weight behind the existing operating thesis.
The near term swing factor is still whether USAC can convert strong demand and pricing into durable free cash flow while capex, lube oil, and labor costs stay elevated. The biggest risk remains leverage and distribution coverage, so even with better earnings, interest expense and payout sustainability stay central to the story.
The most relevant piece of recent news is the US$600 million senior notes due 2035 at 6.75%, paired with roughly US$1.06 billion of remaining availability on the ABL facility. This combination gives USA Compression Partners room to fund new horsepower, support the J W integration, and keep units working in a tight compression market.
That extra funding capacity does not remove risk. It leans harder into the existing concern that higher debt and interest costs could pressure coverage if margins compress or distributable cash flow underperforms guidance. For you, the key question is whether this balance sheet structure supports the catalysts you care about more than it magnifies the downside if conditions soften.
USA Compression Partners' current analyst narrative points to forecast revenue of US$1.6b and projected earnings of US$297.7 million by 2029, based on an assumed 9.9% yearly increase in revenue and an earnings increase of about US$153.4 million from US$144.3 million today.
Discover how USA Compression Partners' fair value indicates a 23% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$26.20 and US$30 per unit, so even a tiny sample already shows how far opinions on USA Compression Partners can spread. Those views were set before the latest earnings, higher horsepower deployment, rising lube oil costs, and a larger debt stack. Use that gap as a prompt to compare multiple approaches before deciding how this income story fits your portfolio.
Explore another USA Compression Partners fair value estimate, including one that suggests it could be worth just $26.20.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your USA Compression Partners research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for USA Compression Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate USA Compression Partners' overall financial health at a glance.
Looking For More Investment Ideas Beyond USA Compression Partners?
Once you have a view on USA Compression Partners, widen the lens. Diversifying the income stream and risk profile across a few different businesses can help you avoid relying on a single story working exactly as planned.
The Simply Wall St Screener is built for that kind of broad, idea-first search. You can filter for balance sheet strength, cash generation, yield and more, then narrow down to a focused watchlist that fits your goals.
- For investors who care most about dependable balance sheets and steady fundamentals, start building your shortlist with the list of solid balance sheet and fundamentals (24 results).
- If potential mispricing is your priority and you want candidates with quality metrics at what may be restrained valuations, scan through the 35 high quality undervalued stocks.
- Income focused readers who like the idea of strong payouts backed by resilient businesses can source fresh watchlist ideas from the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com