


Mirum Pharmaceuticals has seen its stock climb sharply over recent years, which puts fresh attention on a simple question for investors who care about fundamentals: Is the current share price adequately supported by the company’s sales today and what those sales may reasonably lead to over time?
- Over the past 5 years the stock has delivered a very large total return of about 7x, so anyone buying now is effectively leaning on how well its revenue base justifies that kind of rerating.
- Recent clinical and regulatory progress across Mirum Pharmaceuticals' rare disease portfolio, along with higher reported product sales, can shape how investors think about future revenue scale and the profitability that might eventually be earned on those sales.
- The analysts covering Mirum Pharmaceuticals have run their own numbers. See what analysts think Mirum Pharmaceuticals's shares could be worth.
The stock's next move may depend on whether Mirum Pharmaceuticals' current market value is reasonable when set against its sales and the Fair Ratio benchmark.
If Mirum Pharmaceuticals has put rare disease sales on your radar, it can also help to compare that theme against a wider field of companies screened for 38 healthcare AI stocks.
Where Does Mirum Pharmaceuticals Sit on Sales?
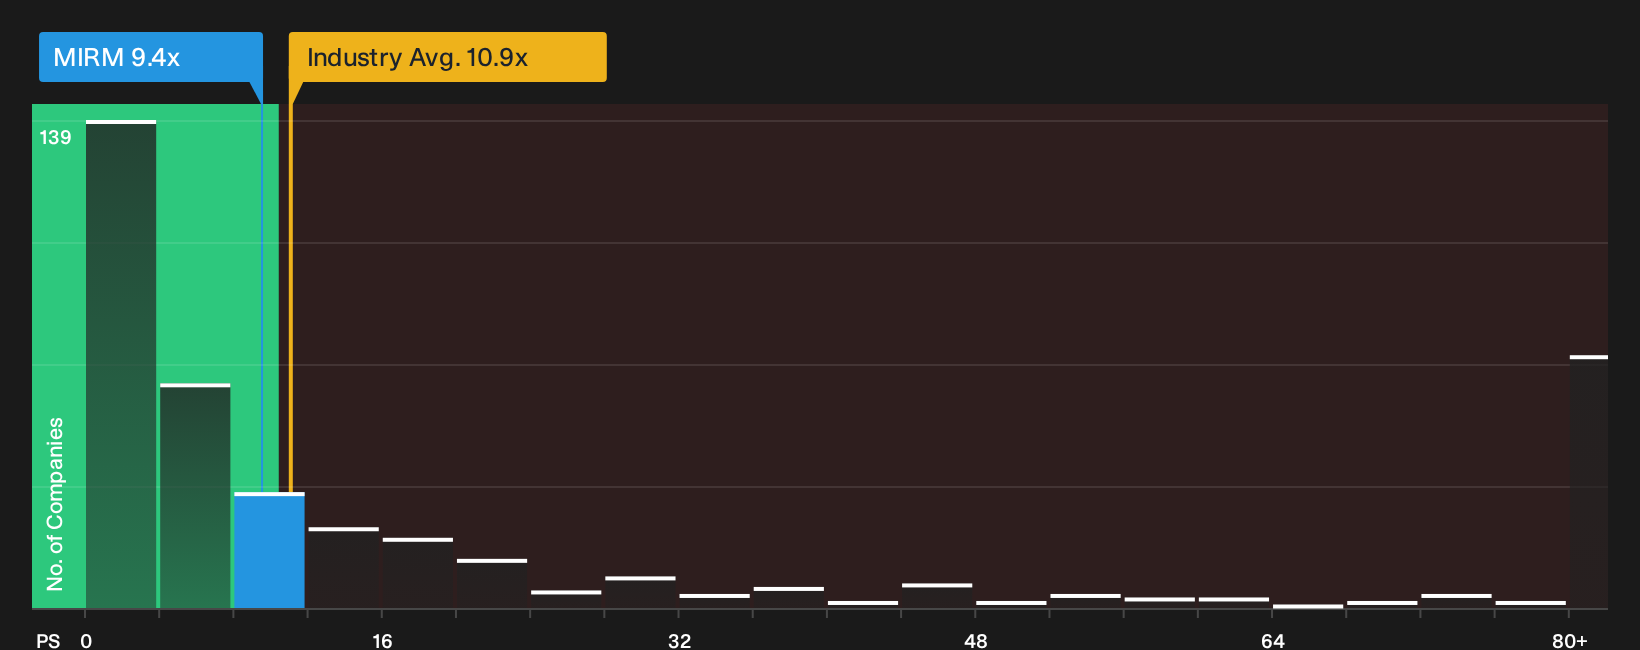
P/S works well for Mirum Pharmaceuticals because investors are focusing on revenue traction while the business is still loss making on earnings. The stock trades on a P/S of 9.4x, which is below both the biotech industry average of 10.9x and the peer group at 13.4x. That means the market is currently paying less for each dollar of Mirum’s sales than it is for many comparable biopharma stocks.
The Fair Ratio model, which estimates the multiple you might expect given Mirum Pharmaceuticals' growth profile, margins, size and risk, places the current 9.4x slightly under that tailored benchmark and points to a valuation that is about right on this framework. Because strong rare liver disease data and upgraded 2026 sales guidance have already attracted attention, the current P/S suggests investors are neither paying a fire sale price nor a clear premium for that progress, and instead need to decide whether the quality and durability of future revenue justify this level. Explore the numbers behind Mirum Pharmaceuticals's P/S valuation.
The Mirum Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Mirum Pharmaceuticals pick up exactly where that P/S question leaves you. They spell out which paths for revenue growth, margins and eventual earnings would need to play out for Mirum Pharmaceuticals' share price to look meaningfully higher or lower than today. Rather than relying on a single multiple or model output, each scenario breaks its fair value into explicit building blocks so you can later compare those assumptions with the company’s reported results on the Community page.
One of the top community narratives on Mirum Pharmaceuticals: 37% undervalued
"Broader patient identification, international expansion, and supportive reimbursement environments are driving sustained revenue growth and improving margins for Mirum's portfolio..."
Discover why this Narrative puts Mirum Pharmaceuticals at 37% undervalued.
One more Mirum Pharmaceuticals check that belongs beside the price tag
Valuation is only one lens on Mirum Pharmaceuticals, and the research flag on this stock points to specific concerns that some investors may want to weigh before getting comfortable with the story. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com