


- AL Sydbank reported third quarter 2026 net income of DKK 1,072 million and nine month net income of DKK 2,833 million. Earnings per share from continuing operations were DKK 12.4 for the quarter and DKK 32.4 for the nine month period.
- The bank is combining higher net income with an ongoing share buyback that has taken own shareholdings to 1.66% of share capital. This tightens the share base and sharpens focus on how current earnings support that reduced pool of equity.
- Focus now turns to how AL Sydbank’s investment narrative incorporates stronger net income alongside an active capital return program.
Compare AL Sydbank’s earnings story with other banks returning capital to shareholders by scanning our curated list of list of solid balance sheet and fundamentals (196 results).
What Is AL Sydbank's Investment Narrative?
To own AL Sydbank, you need to be comfortable with a fairly straightforward banking story. The group leans on classic lending, deposit gathering and fee businesses across Denmark, with earnings growth supported by higher net income rather than rapid, capital heavy expansion. The latest quarter fits that picture. Profit is higher year on year, while earnings per share are held back by a larger share count and ongoing buybacks. That mix keeps attention on how effectively management converts headline profit into per share value for you as a shareholder.
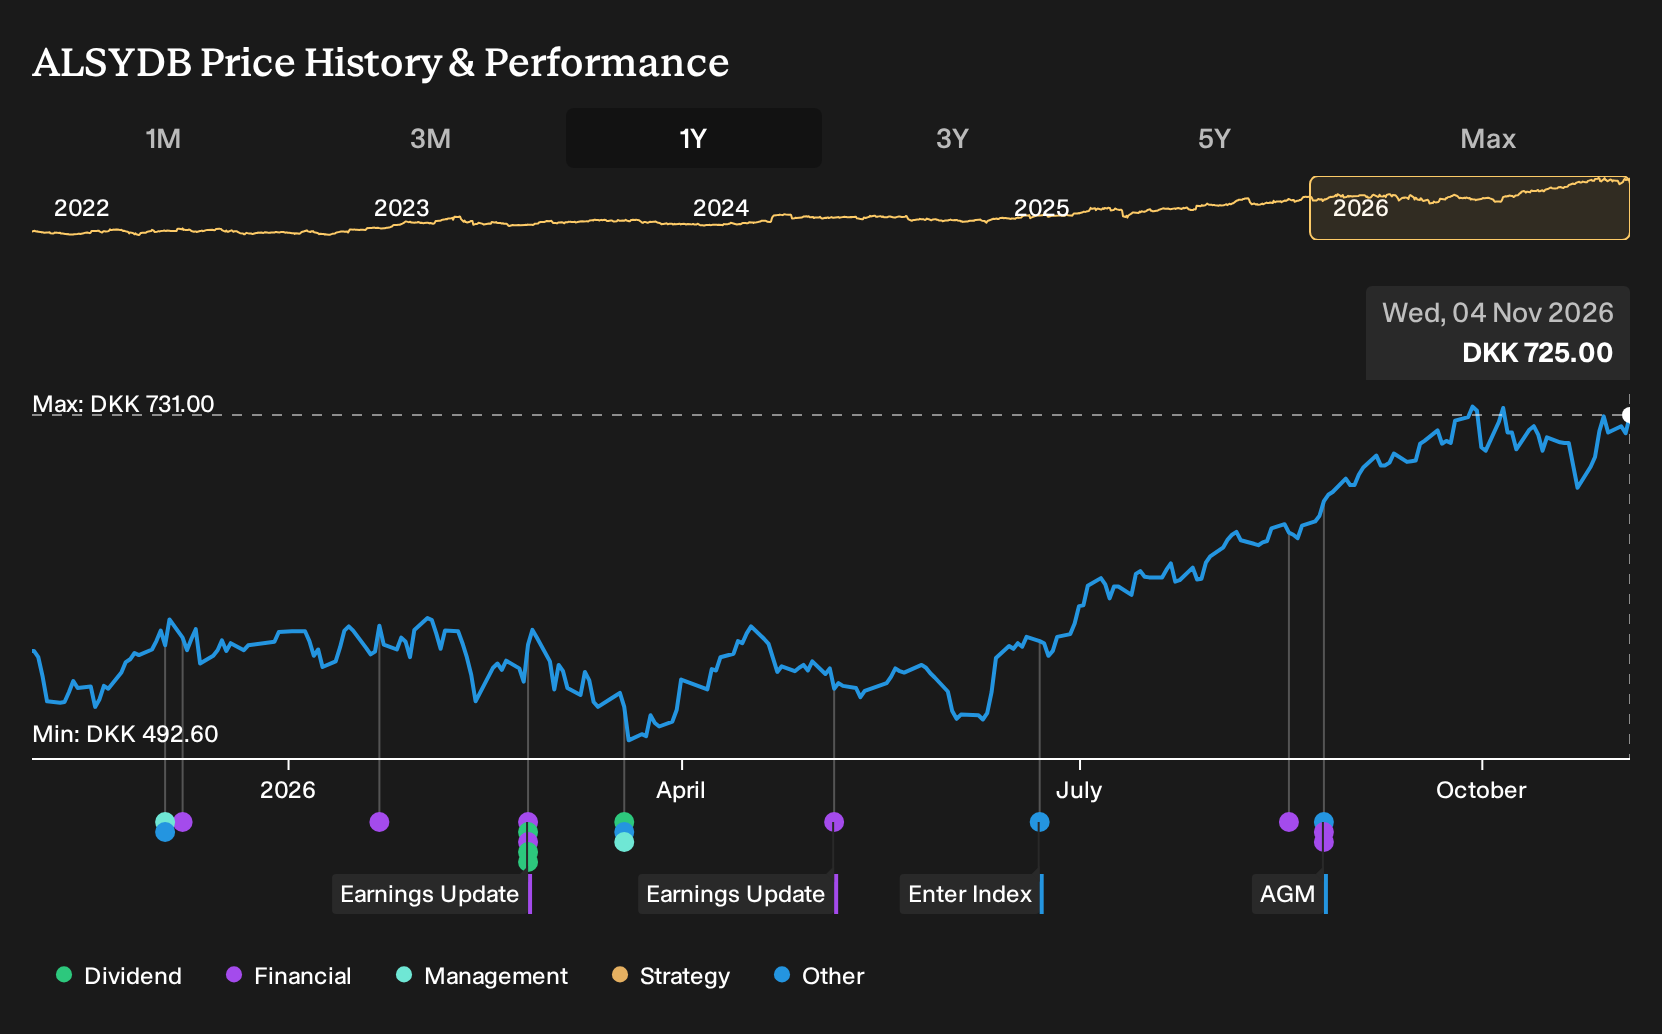
The near term hinges on three things: execution on credit risk, including a bad loan ratio of 2.6% and a 58% allowance; discipline on one off items after a DKK 2.6b loss earlier in 2026; and pricing power in core banking as the balance sheet grows. Against that, the stock trades on a P/E of 25.9x, well above peer and industry averages, while recent returns have been strong. The fresh earnings print and buyback progress reinforce the current investment narrative rather than transform it, so the key question is whether that higher multiple still looks sensible if growth or asset quality wobbles.
That said, there is one pressure point in the AL Sydbank story that is easy to gloss over until you realise that ...
There's only one way to know the right time to buy, sell or hold AL Sydbank. Head to Simply Wall St's company report for the latest analysis of AL Sydbank's Fair Value.
Exploring Other Perspectives
Community fair value estimates for AL Sydbank from two Simply Wall St Community members range from DKK 792 to about DKK 1,252, so you are looking at a wide personal valuation band. These views pre date the latest earnings and buyback progress, so treat them as a starting point and explore several alternative viewpoints before forming your own stance.
Explore another AL Sydbank fair value estimate, including one that suggests as much as 73% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AL Sydbank research is our analysis highlighting 3 key rewards and 6 important warning signs that could impact your investment decision.
- See our latest analysis for AL Sydbank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AL Sydbank's overall financial health at a glance.
Looking For More Investment Ideas Beyond AL Sydbank?
If AL Sydbank has sharpened your focus on quality, capital returns and valuation, it can be useful to set it alongside a wider watchlist of potential opportunities using the Simply Wall St Screener.
- For investors who want strong fundamentals without stretching for speculative stories, compare AL Sydbank with a list of solid balance sheet and fundamentals (196 results) that may offer sturdier financial footing.
- If you prefer a margin of safety on price, weigh this bank against a 195 high quality undervalued stocks that might line up better with your required return profile.
- Income focused investors can balance AL Sydbank with a 208 dividend fortresses that could better match long term cash flow goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com