


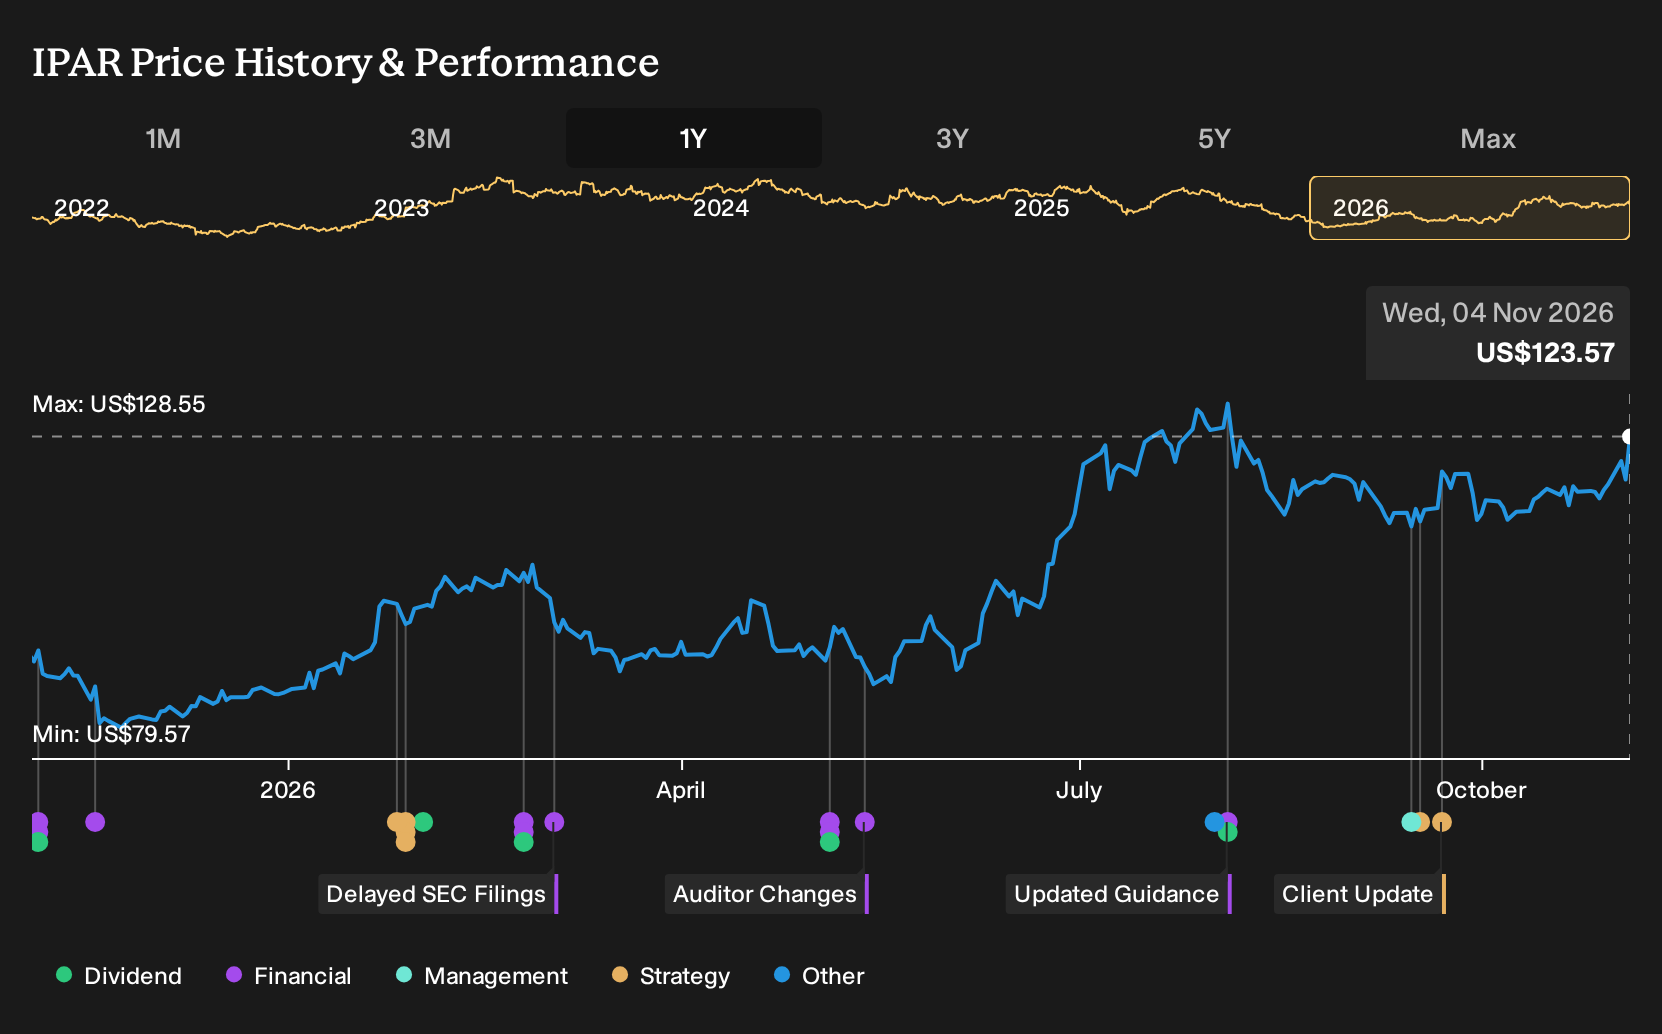
- Interparfums reported third quarter 2026 sales of US$429.51 million with net income of US$68.2 million and diluted EPS of US$2.13, alongside nine month sales of US$1.12 billion and net income of US$142.06 million.
- The earnings release points to broadly steady performance, with modest year on year gains in net income and earnings per share. This can inform how investors think about Interparfums' ability to fund its heavier advertising and product launch plans.
- We will now look at how Interparfums' slight EPS uptick in this quarterly report interacts with the existing long term investment narrative.
Interparfums Investment Narrative Recap
Owning Interparfums means believing that a portfolio of licensed fragrance brands can keep turning steady demand into consistent earnings, even with uneven regional trends and heavier marketing. The slight EPS uptick in the third quarter, to US$2.13, supports the idea that current spending on advertising and distribution is not derailing profitability in the near term.
The key short term swing factor is whether elevated SG&A, including higher advertising and logistics, starts to squeeze operating margins more meaningfully. The main risk still sits in license concentration and war affected regions like the Middle East and Africa. This quarter's largely stable results do not materially change either catalyst or risk.
For context around this print, the earlier decision to make 2026 an off cycle year focused on line extensions matters most. Interparfums is using this period to prepare a denser launch schedule in 2027 and 2028, supported by higher advertising and promotion that management guided toward about 21% of sales for 2026.
This setup frames how to read the modest third quarter EPS increase and nine month net income of US$142.06 million. Execution on digital and e commerce programs, along with long dated licenses like Puma and Roberto Cavalli, will determine whether this heavier 2026 spend converts into a stronger product cycle and more resilient earnings power later in the decade.
Interparfums' current analyst narrative points to revenues of US$1.8b and earnings of US$184.4 million by 2029, based on forecast annual revenue growth of 5.7% and a shift from earnings today of US$167.8 million to that 2029 consensus. This implies an earnings increase of about US$16.6 million.
Uncover why Interparfums' fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts product launch risk front and center for Interparfums. You might see this third quarter steadiness and feel reassured, while the lowest analysts were already assuming only 3.5% annual revenue growth and earnings of about US$188.6 million by 2029. Those expectations predate this report, so their storyline may shift from here.
Explore 4 other Interparfums fair value estimates, including one that suggests as much as 72% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Interparfums research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Interparfums. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interparfums' overall financial health at a glance.
Looking for more investment ideas beyond Interparfums?
If Interparfums raises useful questions about earnings resilience and balance sheet strength for you, then casting a wider net can round out your watchlist and help you compare business quality side by side.
- For investors who want mispriced quality, scan for companies that combine fundamentals with valuations that still look restrained using the 35 high quality undervalued stocks.
- If income is your priority, focus on businesses that pair higher yields with resilient cash flows by checking the 5 dividend fortresses.
- For those who care most about durability in tougher conditions, filter for companies that keep risk scores low with the help of the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com