


- Martin Marietta Materials reported third quarter 2026 sales of US$2.37b with net income of US$256m, and lifted full year revenue guidance to a range of US$7.75b to US$7.85b following the Lhoist North America acquisition.
- The combination with Lhoist North America has expanded Martin Marietta Materials into a leading lime and limestone producer, adding scale to its specialties platform. Quarterly earnings per share from continuing operations moved lower year on year despite record sales.
- We will now explore how Martin Marietta Materials' higher full year revenue guidance after the Lhoist deal could reshape its investment narrative.
Compare Martin Marietta Materials' latest move with a curated 41 power grid technology and infrastructure stocks that could also benefit from large scale infrastructure and construction spending.
Martin Marietta Materials Investment Narrative Recap
To own Martin Marietta Materials, you need to believe the SOAR 2030 portfolio shift and the enlarged aggregates and specialties platform can turn record sales into healthier profitability over time. The latest quarter delivered US$2.37b in sales with EPS from continuing operations lower year on year, so execution, not demand, is the near term focus.
The key short term catalyst remains integration of Lhoist North America and delivery of the targeted cost and cash flow improvements across recent deals. The biggest risk is that higher energy and diesel costs, plus acquisition complexity, keep margins under pressure and prevent the cash flow improvement that SOAR 2030 is targeting.
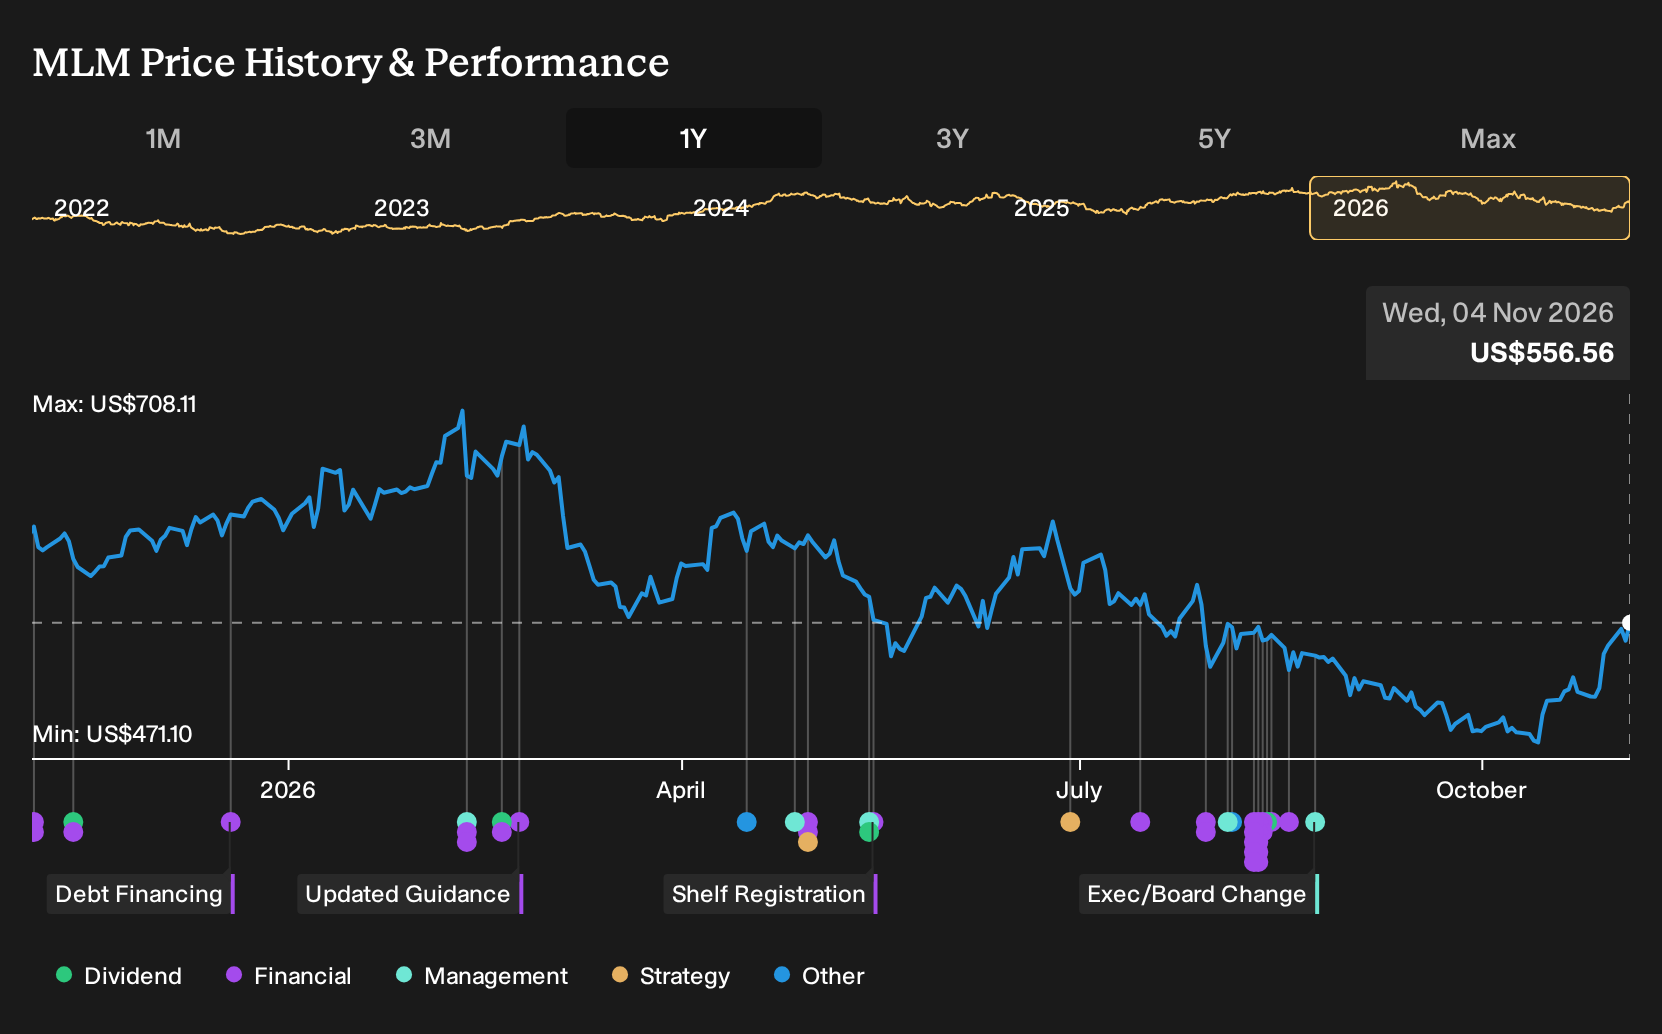
The most relevant update for this news is the third quarter 2026 earnings release. Martin Marietta Materials reported US$2.37b in revenue versus US$1.85b a year earlier, with net income at US$256m versus US$414m. EPS from continuing operations for the quarter was US$3.94, and management raised full year revenue guidance to a range of US$7.75b to US$7.85b.
This combination of record sales, softer quarterly profitability and higher full year revenue guidance puts the spotlight on integration, cost control and pricing power as the main catalysts. It also highlights the risk that energy costs, leverage and any shortfall in the planned US$350m run rate cash flow improvement or Lhoist synergies could hold back margin recovery even if demand for infrastructure and heavy nonresidential projects remains supportive.
Martin Marietta Materials' current analyst narrative points to forecast revenue of US$10.6b and earnings of US$1.8b by 2029, based on an assumed 16.5% yearly revenue growth rate and an earnings increase of about US$870m from the US$930.0m reported today.
Uncover why Martin Marietta Materials' fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One thing the more cautious analysts watch closely is energy costs. Before this latest Martin Marietta Materials update, the lowest forecasts were built around revenue of about US$10.4b and earnings of roughly US$1.6b by 2029. That is meaningfully lower than the consensus path and shows how sharply views can differ. You can use this new earnings and guidance shift as a prompt to compare those opposing narratives yourself.
Explore 3 other Martin Marietta Materials fair value estimates, including one that suggests as much as 13% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Martin Marietta Materials research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Martin Marietta Materials. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Martin Marietta Materials' overall financial health at a glance.
Looking For More Investment Ideas Beyond Martin Marietta Materials?
If this Martin Marietta Materials update has sharpened your thinking, use that momentum to scan a wider field of opportunities with the Simply Wall St Screener. You can filter for financial strength, income potential or valuation, then spot which businesses fit your own risk and return preferences.
- For investors who care most about capital preservation and steadier profiles, start with a 31 resilient stocks with low risk scores that aim to keep downside contained while still offering equity upside.
- If balance sheet resilience is your first filter, focus on companies in the list of solid balance sheet and fundamentals (24 results) to see which businesses pair financial strength with durable fundamentals.
- Income focused readers can zero in on cash return potential by reviewing a curated 5 dividend fortresses that offer yields of 5% or more.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com