


- Seaboard Corporation reported third quarter revenue of US$2.77b and net income of US$28 million, and its board declared a quarterly cash dividend of US$2.25 per share payable on November 23, 2026 to shareholders of record on November 13, 2026.
- The mix of higher year to date revenue of US$8.09b and net income of US$300 million alongside weaker quarterly earnings highlights how different parts of Seaboard's operations can pull performance in opposite directions over short periods.
- Next, the focus turns to how Seaboard's softer quarterly earnings alongside its affirmed dividend could shape the broader investment narrative.
Start lining up Seaboard's mixed earnings and dividend profile against other income and quality plays by scanning our hand picked 5 dividend fortresses for comparison.
What Is Seaboard's Investment Narrative?
To own Seaboard, you have to be comfortable with a real operating mix. This is a sprawling agricultural, energy, and marine logistics group where pork, grain trading, and shipping all move the needle. The latest quarter underlines that reality. Revenue of US$2.77b and net income of US$28 million sit alongside nine month earnings of US$300 million, so short term results can look lumpy as commodity prices, feed costs, and freight demand pull in different directions.
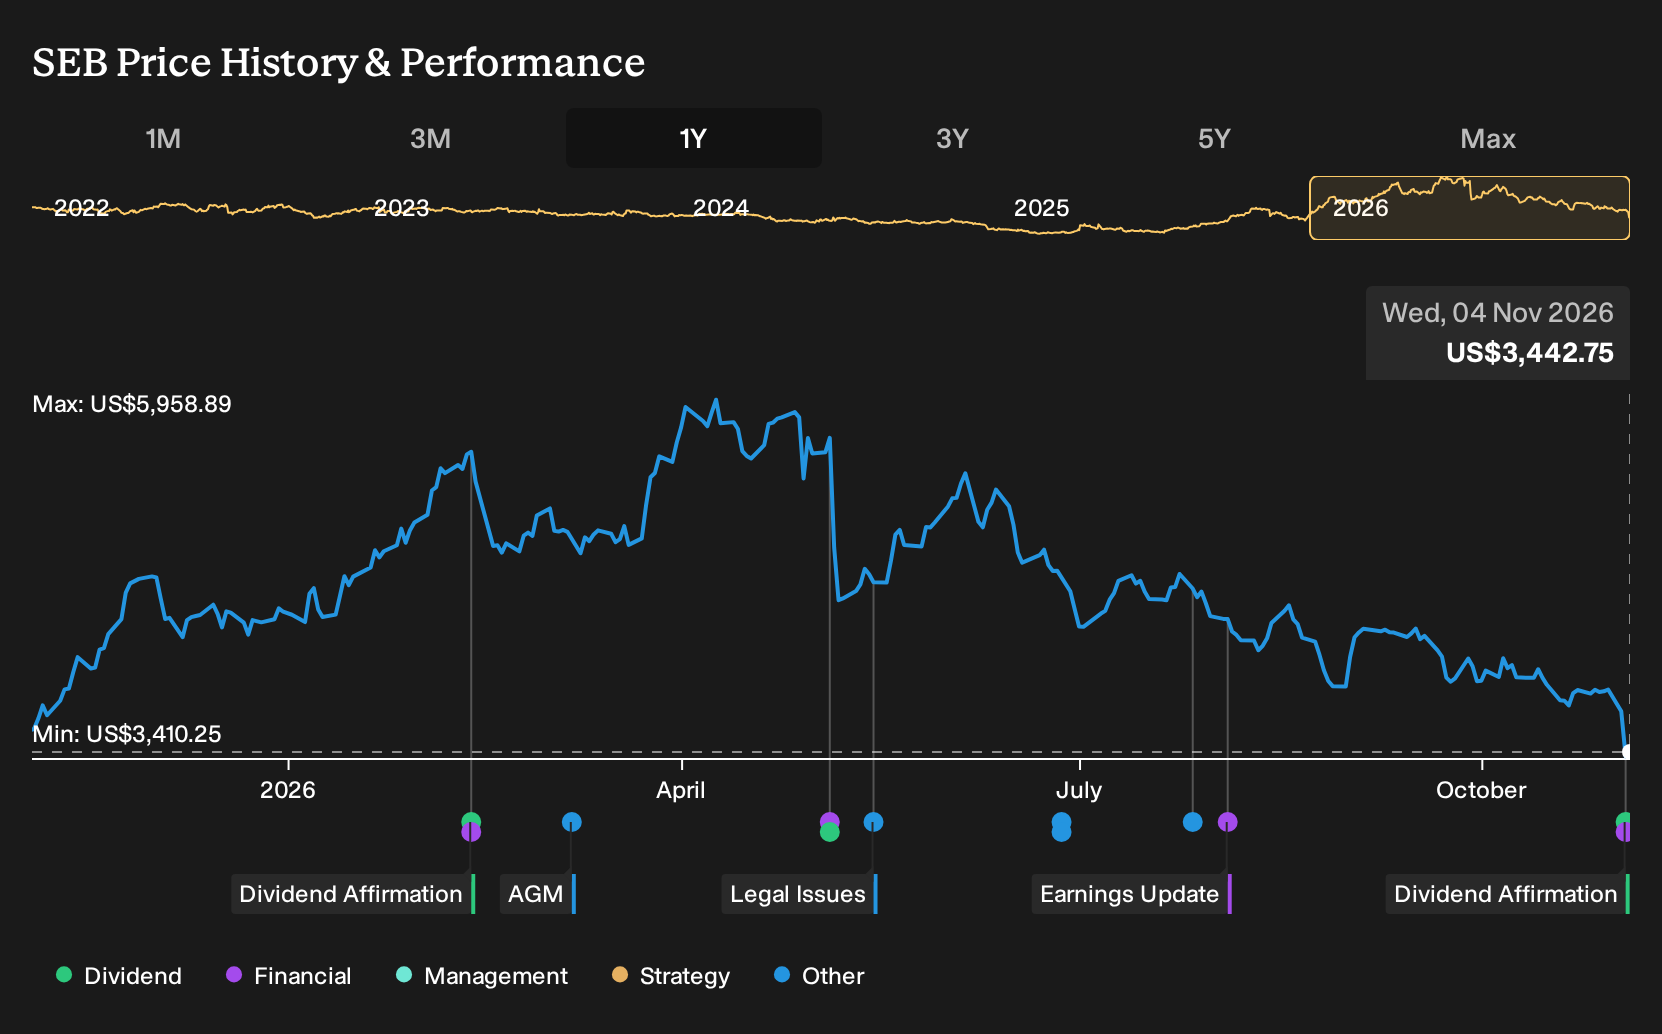
The affirmed US$2.25 quarterly dividend fits that pattern of accepting volatility in exchange for a broad, cash generative platform. In the near term, the key questions are whether weaker quarterly earnings hint at pressure on pork profitability, trading margins, or marine utilization, and how capital intensive segments absorb swings in demand and pricing after a share price that has fallen 22.2% year to date and 19.5% over 90 days.
Even so, there is one structural issue around Seaboard that does not show up fully in the latest dividend or headline earnings and ...
There's only one way to know the right time to buy, sell or hold Seaboard. Head to Simply Wall St's company report for the latest analysis of Seaboard's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Seaboard research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Seaboard. The report includes a comprehensive fundamental analysis summarized in a single visual known as the Snowflake, making it easy to evaluate Seaboard's overall financial health at a glance.
Looking For More Ideas Beyond Seaboard?
If Seaboard's mix of earnings volatility and steady dividends has you thinking about portfolio balance, it can help to line it up against other companies with different risk and income profiles. The Simply Wall St Screener lets you scan a wide field of stocks through focused lenses so you can spot businesses that better match your return goals and tolerance for swings in results.
- For investors who prize resilient balance sheets and dependable fundamentals, start by reviewing the list of solid balance sheet and fundamentals (24 results) to help anchor a more defensive core in your portfolio.
- If you are hunting for mispriced quality where fundamentals and valuation metrics look appealing side by side, sift through the 35 high quality undervalued stocks to see which companies might warrant a closer look.
- Those aiming to pair income with discipline on risk can scan the 31 resilient stocks with low risk scores and see which stocks combine measured volatility with more controlled financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com