


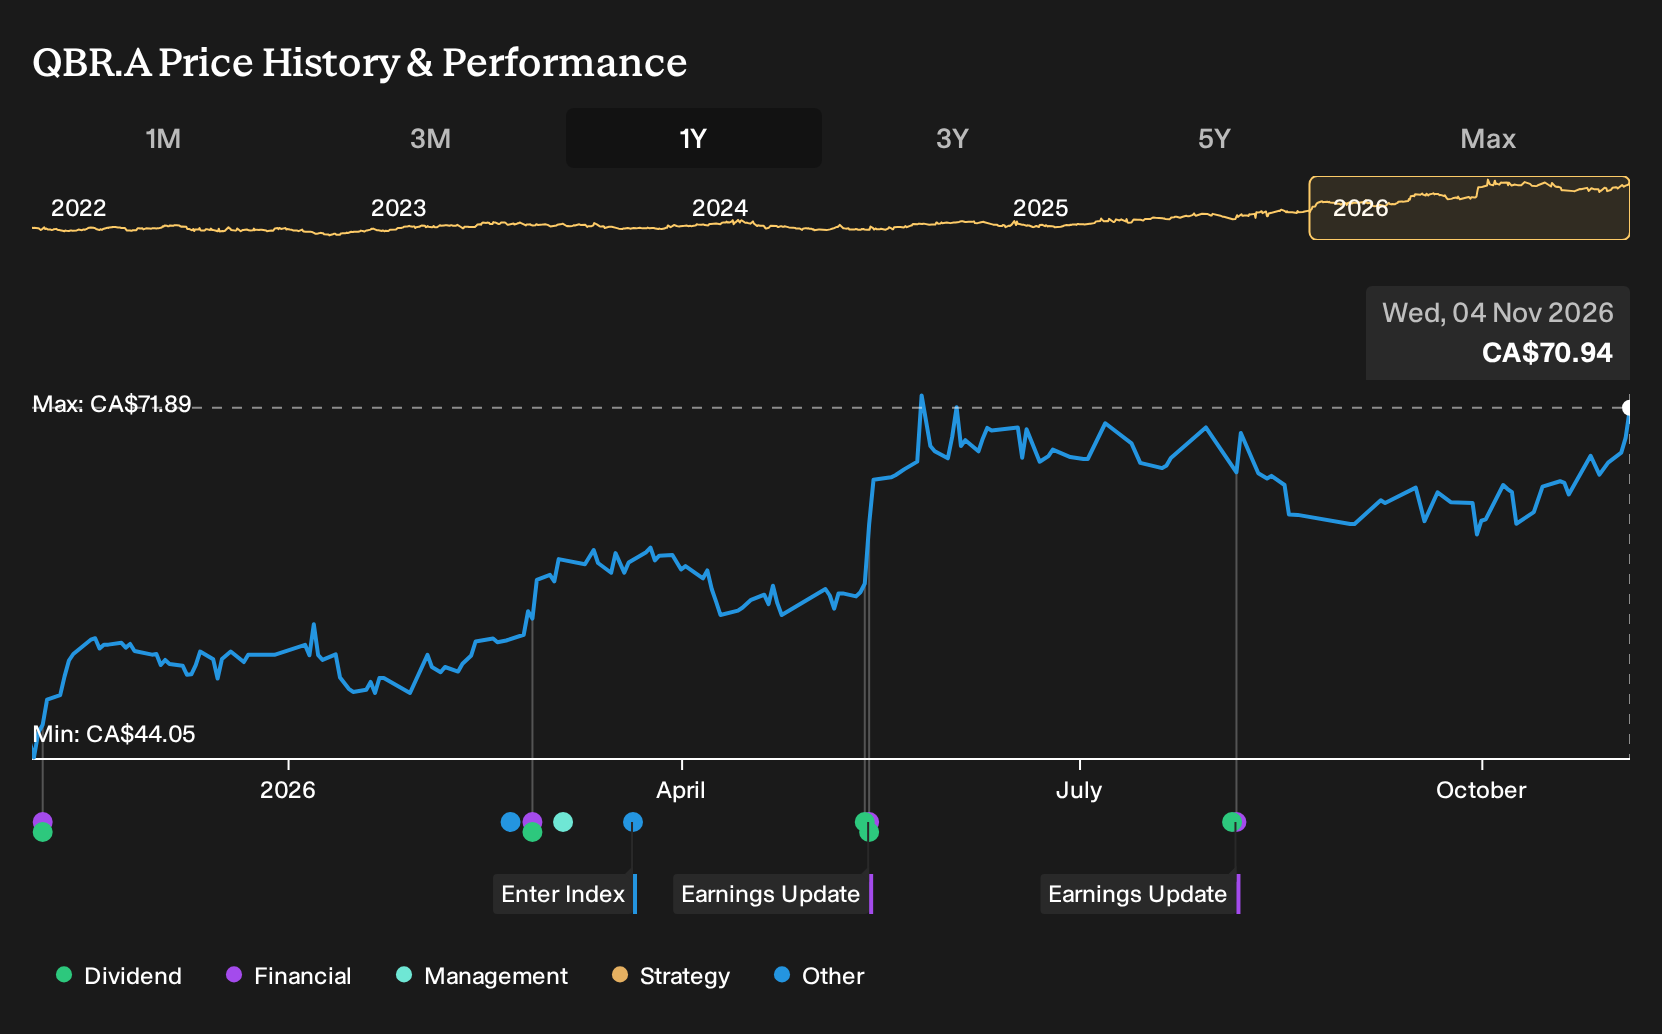
- Quebecor recently lifted its dividend by 12.5%, backed this with a renewed share buyback program, and highlighted strong free cash flow to support these capital returns ahead of its third quarter 2026 update.
- The combination of a higher payout and ongoing repurchases points to management confidence in Quebecor’s cash generation, which matters for investors focused on recurring income and disciplined balance sheet management.
- We will now look at how Quebecor’s investment narrative could be influenced by the larger dividend backed by strong free cash flow.
Scan Quebecor’s latest dividend move against a curated 3 dividend fortresses that also highlights recurring cash returns and balance sheet resilience.
What Is Quebecor's Investment Narrative?
For a shareholder to stay comfortable with Quebecor, the belief has to start with the cash engine. Telecom remains the backbone, at CA$4,952.1m of segment revenue, and it is both capital hungry and scale driven. The 12.5% dividend lift and renewed buyback only really make sense if you think that network investment, pricing, and subscriber churn can be managed tightly enough for free cash flow to cover richer payouts while still funding future upgrades.
In the short term, the key swing factors sit in execution around telecom operations, the pace of media and sports earnings, and how management handles its high debt load. The upcoming quarterly results call is where you will see how that capital return decision lines up with leverage, interest costs, and any shift in demand or pricing power for Quebecor’s services.
That said, sitting behind the stronger capital return story is a pressure point that could still unsettle the thesis if ...
There's only one way to know the right time to buy, sell or hold Quebecor. Head to Simply Wall St's company report for the latest analysis of Quebecor's Fair Value.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Quebecor research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Quebecor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Quebecor's overall financial health at a glance.
Looking for more investment ideas beyond Quebecor?
Quebecor may fit your income or cash flow preferences, but it rarely pays to anchor your whole portfolio on a single ticker. Use the Simply Wall St Screener to compare this stock against a wider field and see where the risk, quality, and income profile looks more aligned with your goals.
- If you care most about steady income with fewer surprises, start with a 9 resilient stocks with low risk scores to help balance financial resilience with measured return potential.
- For investors who enjoy hunting for underfollowed stories, widen your scope with a 8 high quality undiscovered gems that combine strong fundamentals with less crowded shareholder registers.
- When durability of the balance sheet matters most, especially in tougher conditions, filter for companies through a list of solid balance sheet and fundamentals (6 results) that emphasises prudent leverage and cash coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com