


Quanta Services (PWR) is back in focus after lifting its 2026 revenue outlook to a range of US$41.3b to US$41.6b, alongside reporting sharply higher quarterly sales and earnings.
Even with the raised 2026 revenue outlook and strong third quarter figures, Quanta Services’ share price has pulled back sharply in the short term, falling 11.65% on the day and 15.07% over 30 days. However, the year-to-date share price return of 32.01% and a very large 5 year total shareholder return signal that long term momentum has still been strong as investors weigh rapid operational progress against higher expectations and shifting risk perceptions.
Scan for other grid and infrastructure plays that are moving on similar earnings and guidance shifts by reviewing the hand picked 41 power grid technology and infrastructure stocks alongside Quanta Services.
The sharp pullback in Quanta Services after stronger guidance and earnings creates an obvious tension. Does this reset in the share price improve the risk reward, or is the bar now simply higher for future execution?
Most Popular Narrative: 6% Undervalued
Quanta Services last closed at $580.44, while the most followed valuation narrative pegs fair value at $620, implying a modest gap that keeps the recent pullback in perspective for long term holders.
Quanta turns utility and hyperscaler capex into energised megawatts, and Q3 showed how well that works: revenue +57% (+37% organic), adjusted EPS +82% to US$6.06, record FCF of US$1.2B and backlog of US$63.7B (+US$10B in a quarter). FY26 adjusted EPS guidance of US$17.90–18.30 already puts Quanta within reach of its 2030 target range (US$21.60–26.75) by 2027.
See why 0 investors see Quanta Services as 6% undervalued.
Result: Fair Value of $620 (UNDERVALUED)
Still, the Quanta Services story can break if hyperscaler data center spending pauses, or if copper and equipment constraints choke project timing and margins.
Find out about the key risks to this Quanta Services narrative.
Another View: Quanta Services Through The P/E Lens
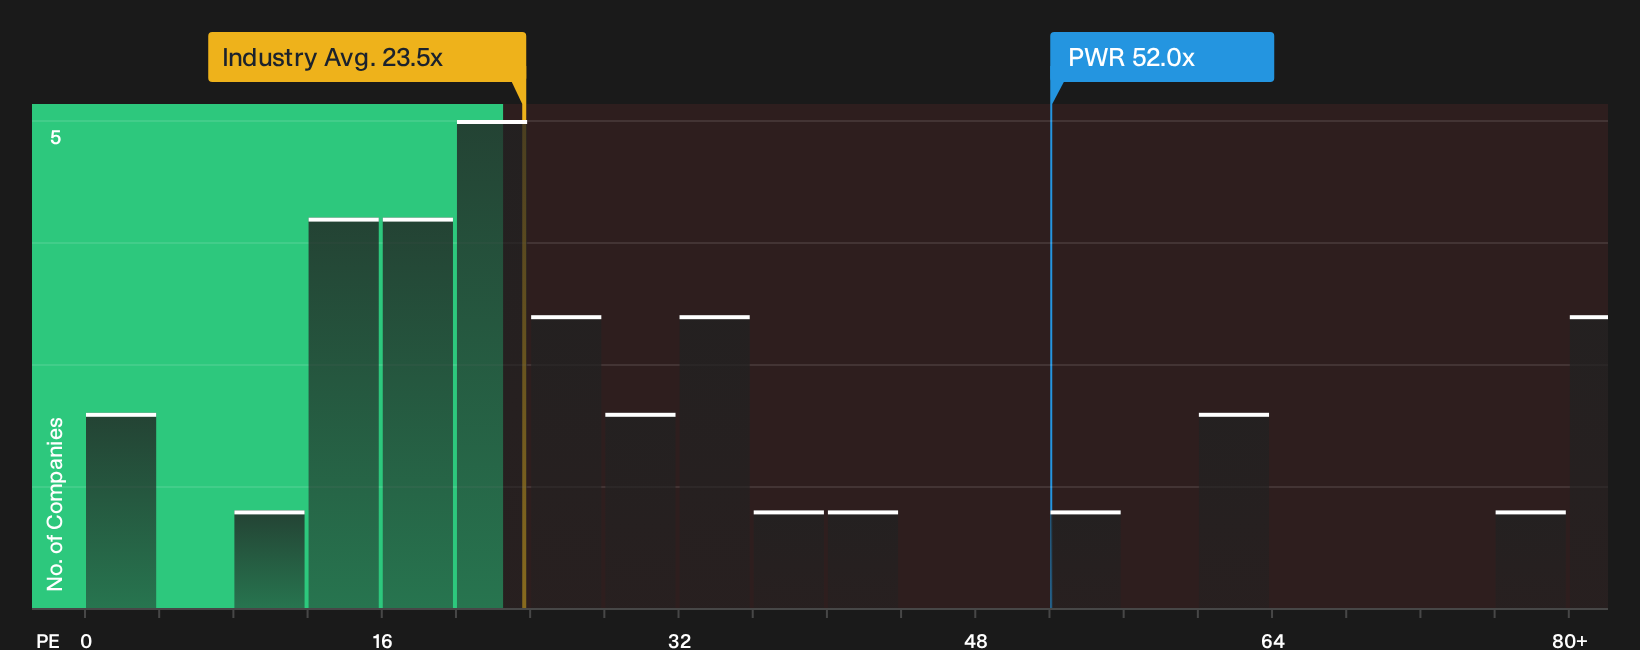
Quanta Services may look modestly undervalued against the US$620 fair value from the narrative, yet the simple P/E check tells a different story. The stock trades on 52x earnings, while the fair ratio sits at 38.4x and the US Construction industry and peer averages are 23.5x and 21.1x. That is a wide gap. The question for you is whether growth and execution justify paying well above where the market could eventually anchor the multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Quanta Services story so far. Move quickly, review the numbers yourself, and weigh both the upside and the red flags in the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Quanta Services?
If Quanta Services has sharpened your focus on quality, use this momentum to widen your watchlist with focused stock ideas built from disciplined, fundamentals-driven filters.
- Spot potential mispricings early by reviewing a curated 35 high quality undervalued stocks that screens for quality businesses trading below their implied worth.
- Strengthen your income stream by scanning a targeted 5 dividend fortresses built for investors who want yield without ignoring balance sheet reality.
- Prioritise resilience by working through a hand picked 31 resilient stocks with low risk scores that focuses on companies with steadier risk profiles and sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com