


Energizer Holdings (ENR) has drawn fresh attention after recent trading, with the stock closing at US$25.19 and posting double digit gains over the past month and past 3 months.
For context, Energizer Holdings now carries a year to date share price return of 26.39%, alongside a 1 year total shareholder return of 11.32%. Meanwhile, the 3 year and 5 year total shareholder returns show double digit declines, which points to momentum rebuilding in the short term after a tougher multi year stretch.
Scan how Energizer Holdings compares with other consumer-focused stocks showing fresh price momentum and solid fundamentals by reviewing the hand picked 35 high quality undervalued stocks.
Bulls argue Energizer Holdings is finally turning a corner after years of weaker long term returns. Bears point to the past declines and analyst targets below the current price. Which side do the numbers lean toward as valuation comes into focus?
Price-to-Earnings of 21.2x: Is it justified?
On the numbers, Energizer Holdings trades on a P/E of 21.2x, which sits below its peer group average of 25.4x but above the global household products benchmark of 17.5x. At a last close of $25.19, that mix of cheaper pricing versus direct peers and richer pricing versus the wider industry puts the spotlight squarely on whether the earnings outlook supports this middle ground.
The P/E ratio simply compares the current share price to earnings per share, so a higher multiple often signals that investors are willing to pay more for each dollar of profits. For a consumer products group like Energizer Holdings that earns most of its $2.99b in revenue from batteries, lights, and auto care consumables, that figure becomes a shorthand for how much faith the market has in future profitability relative to today.
Forecasts point to earnings growth of 17.74% per year alongside far slower expected top line expansion of 0.6% per year. This suggests the market is paying up primarily for margin and profit recovery rather than rapid sales gains. The fair P/E estimate sits at 18.8x, which is meaningfully below the current 21.2x, so the valuation runs ahead of the level the model indicates the market could move toward if expectations cool.
Explore the SWS fair ratio for Energizer Holdings.
Result: Price-to-Earnings of 21.2x (OVERVALUED).
Still, the recent share price strength sits against 3- and 5-year shareholder returns that show double-digit declines, and analyst targets remain below the current Energizer Holdings price.
Find out about the key risks to this Energizer Holdings narrative.
Another View: SWS DCF Model Paints A Different Picture
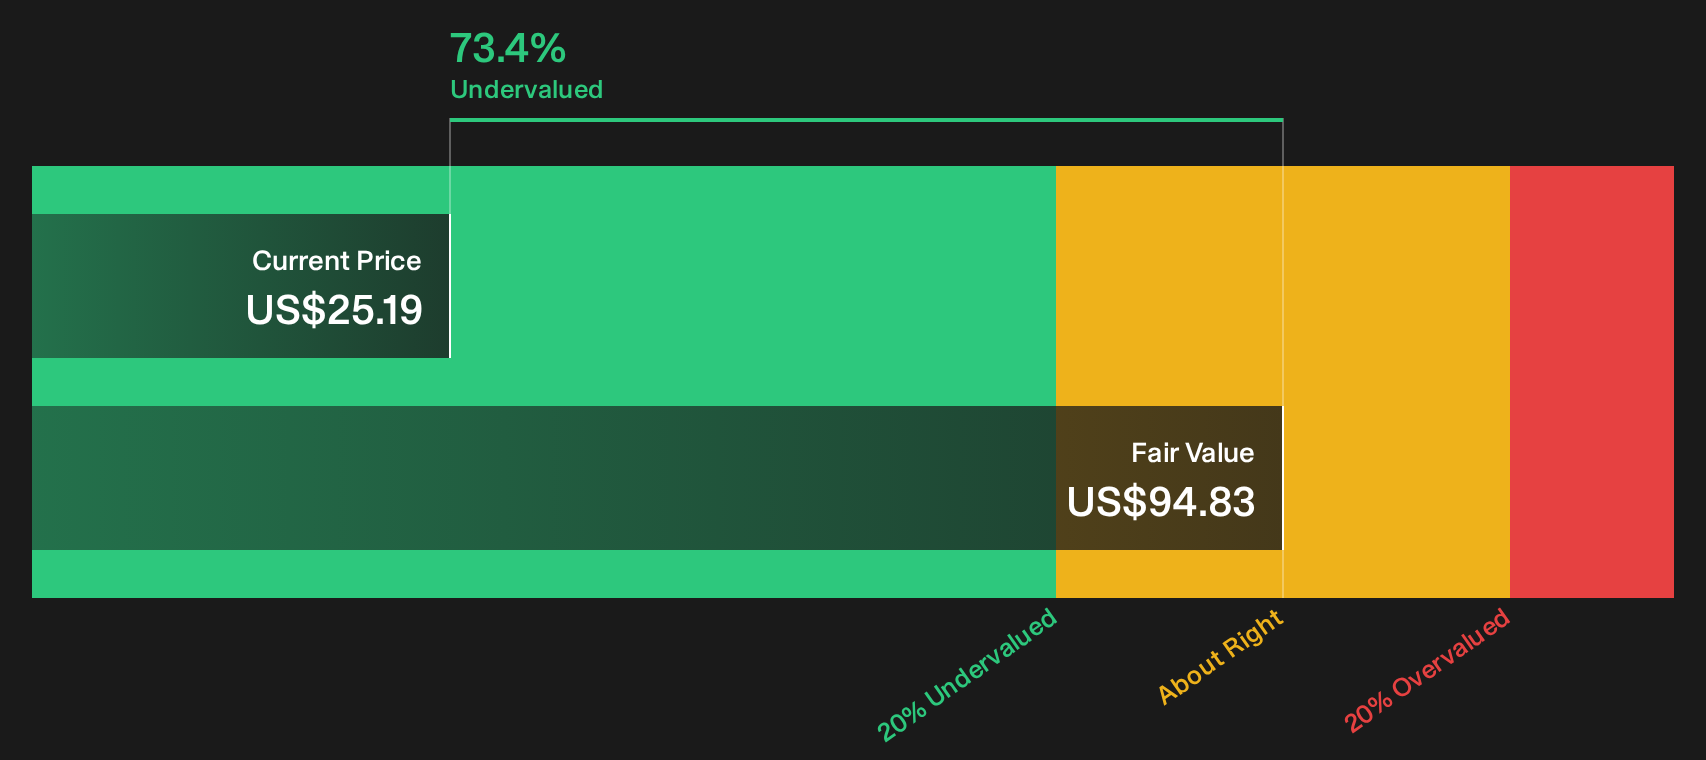
The earnings multiple flags Energizer Holdings as slightly expensive relative to its own fair ratio, yet the SWS DCF model points in the opposite direction. On that approach, ENR at $25.19 is trading about 73% below an estimated future cash flow value of $94.83, which frames the current price as heavily discounted instead of stretched.
Such a wide gap between an earnings based check and a cash flow model gives investors two very different stories to weigh. Does the P/E caution matter more to you than a model that values long term cash generation so generously?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Energizer Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment split between Energizer Holdings looking expensive on earnings and cheap on cash flows, the real edge comes from testing the numbers yourself and deciding quickly which side you trust more. To see both the risks investors worry about and the potential rewards they are watching, start with these 2 key rewards and 4 important warning signs.
Looking for more Energizer Holdings sized ideas?
If Energizer Holdings has you rethinking your watchlist, do not stop here. Broader opportunities sit just beyond this stock, and you risk missing them.
- Target resilient payouts and income stability by scanning companies built around durable dividends through the 5 dividend fortresses.
- Hunt for financially robust businesses by filtering for a list of solid balance sheet and fundamentals (24 results) that can better withstand shocks when conditions change.
- Unearth underfollowed opportunities by zeroing in on 19 high quality undiscovered gems before attention and capital rush in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com