


Weibo has seen a sharp share price slide over the past several years, which puts a fresh spotlight on a simple issue for investors. Is the current US$6.49 price tag adequately supported by the earnings the business generates today and is expected to produce in the future?
- The stock has fallen 79.6% over the past 5 years, which raises a clear question about how firmly its earnings now underpin the valuation.
- The business model depends heavily on turning user activity into advertising and related revenue, so any change in monetisation efficiency can feed directly into its profit base and therefore into what investors might reasonably be willing to pay for those earnings.
- There is a second opinion on Weibo worth weighing. See what analysts think Weibo's shares could be worth.
The issue now is whether the earnings that Weibo delivers are strong and reliable enough to make the current share price look well supported.
If you are weighing whether Weibo's earnings justify its current P/E, it can help to compare that question across a wider field of 35 high quality undervalued stocks.
Is Weibo a Bargain on Earnings?
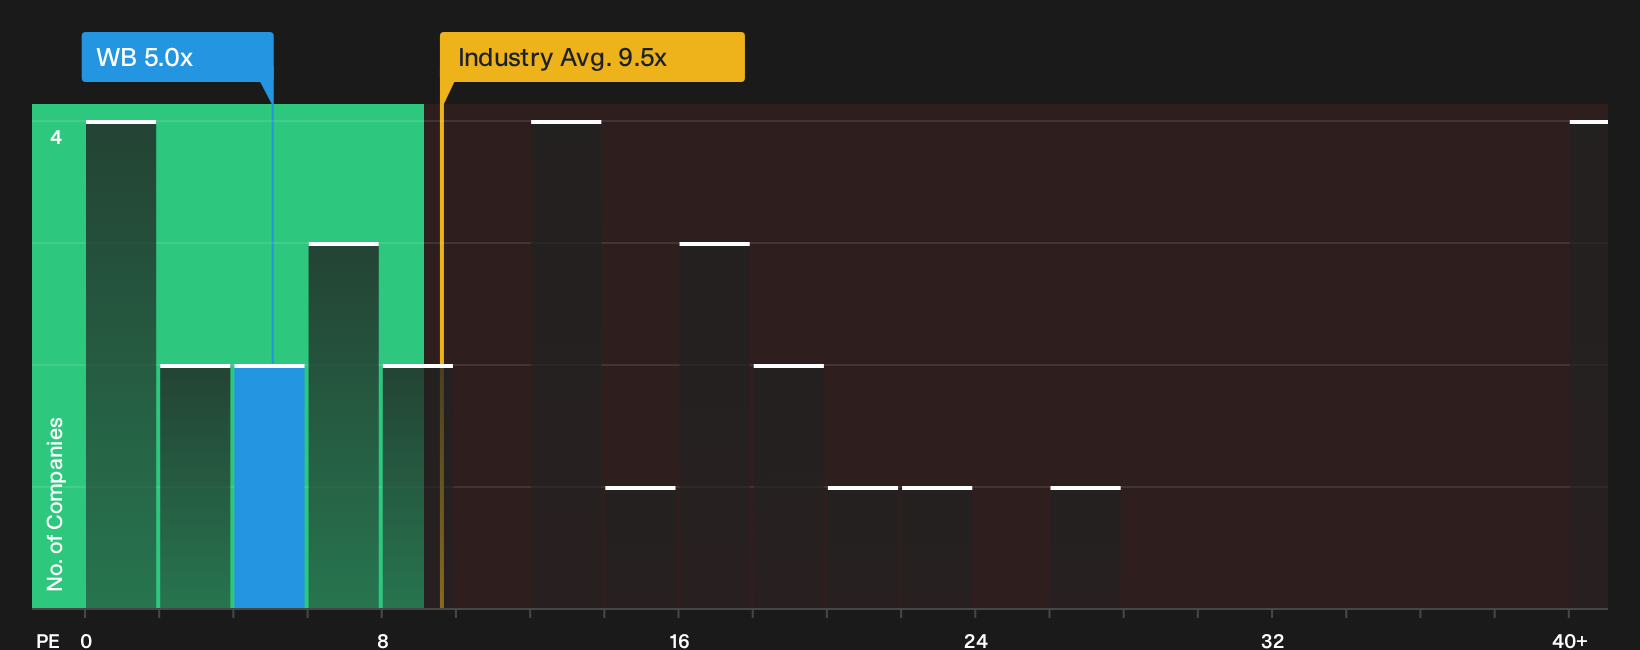
The P/E ratio suits Weibo because earnings remain the key anchor for how investors judge a mature social media platform. Right now, the stock trades at about 5.0x earnings, which is well below the Interactive Media and Services industry average of roughly 9.5x and the broader peer group at about 14.4x. For a reader, that gap signals that the market is putting a relatively low price on each dollar of profit that Weibo currently generates.
A tailored fair P/E multiple that blends Weibo's sector, business quality, scale and risk profile sits higher than where the shares trade today. That means the current 5.0x earnings level screens as undervalued against what this model suggests might be appropriate. As an investor, you would want to ask whether the concerns baked into the price fully reflect the earnings power you think Weibo can sustain. Explore the numbers behind Weibo's P/E valuation.
The Weibo Narrative: What Would Justify Today's Price?
Weibo's Simply Wall St Narratives pick up where the P/E puzzle leaves off. They spell out which paths for revenue growth, profitability and earnings would need to play out for today's valuation to look too low or too high, rather than leaving you with a single number and no context. Where a ratio or model gives one figure, these Narratives describe the future it rests on so you can check over time whether reality is tracking that script on the Community page.
One of the top community narratives on Weibo: 21% undervalued
"The numbers imply that Weibo’s share price reflects a very low multiple on its free cash flow, so the market is pricing the operating business conservatively..."
Discover why this Narrative puts Weibo at 21% undervalued.
One more thing about Weibo that is easy to overlook
Valuation only tells part of the story for Weibo, because the research here has also flagged specific risk checks that could change how you view the whole picture. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com