


Pennant Group (PNTG) just released third quarter 2026 results, giving investors fresh numbers on sales, earnings per share, and net income for both the quarter and the first nine months.
Pennant Group’s latest quarterly update lands after a strong run in the stock, with the share price up 9.28% over the past month and a 58.25% year to date share price return. The 1 year total shareholder return of 74.97% and 3 year total shareholder return of 249.25% point to momentum that has been building for some time.
Scan how Pennant Group’s earnings momentum compares with other healthcare operators by reviewing the hand-picked 38 healthcare AI stocks that are shaping the next phase of growth in tech-enabled care.
Pennant Group shares have already re-rated sharply on the latest quarter, so the key question now is whether most of the rerating is already earned or if the valuation still leaves room for more.
Most Popular Narrative: 6% Undervalued
The most followed narrative on Pennant Group pegs fair value at $46.67 using a 7.31% discount rate, compared with the latest $44.04 close. This frames the current rally against a valuation that still screens as modestly discounted.
The current valuation, including a forward P/E of 24.3x and an above-market beta of 1.29, suggests the share price already reflects meaningful ongoing execution and allows limited room for disappointment, even though this narrative describes Pennant Group as undervalued and positive on its prospects.
See why 6 investors see Pennant Group as 6% undervalued.
Result: Fair Value of $46.67 (UNDERVALUED)
Still, Pennant Group’s story could be knocked off course if Medicare reimbursement tightens further or if recent acquisitions fail to deliver the expected margins.
Find out about the key risks to this Pennant Group narrative.
Another View On Pennant Group’s Valuation
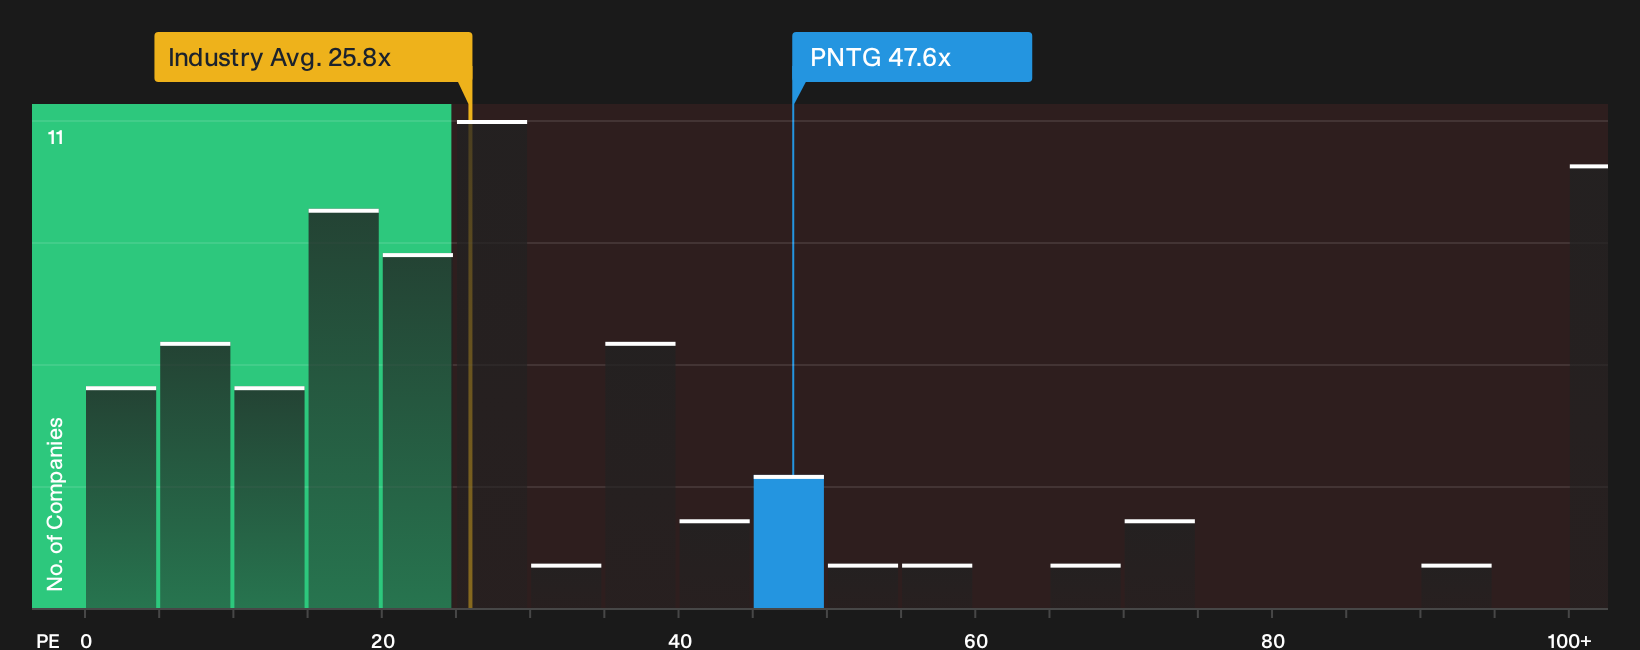
The first narrative presents Pennant Group as undervalued, yet the P/E of 47.6x suggests a more challenging picture. That figure is almost double the US Healthcare average of 24.8x and is well above a 29.4x level that some might consider fair. The stock even trades at a richer valuation than peers at 53.3x. Whether that premium reflects comfort or concentration risk depends on your own assessment.
To see how this pricing gap could close over time, and what the numbers imply for future returns, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals in Pennant Group’s story so far. For a clearer perspective, review the underlying data directly and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Pennant Group?
If Pennant Group has your attention, do not stop here. Broaden your watchlist with a few targeted angles that could surface your next opportunity.
- Spot potential mispricing early and scan a 35 high quality undervalued stocks to filter for quality businesses trading below their implied worth.
- Prioritise resilience and cash strength by using the list of solid balance sheet and fundamentals (24 results) to focus on companies with sturdier financial foundations.
- Hunt for lesser-known prospects and review the 19 high quality undiscovered gems before the wider market pays closer attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com