


CarMax has delivered a sharp mix of outcomes for shareholders, with the stock up solidly over the past year but still carrying a much weaker five year record. That split performance puts the spotlight on a simple question for anyone looking at the shares today: Is the current price properly explained by the earnings power of the business?
- The share price has fallen 63.7% over the past 5 years, which puts extra weight on whether the earnings profile now supports a different long term story than the one investors experienced over that period.
- The used vehicle retailer relies heavily on turning inventory efficiently and earning a spread on both car sales and associated financing. Any change in margins or credit performance can feed directly into how supportive its earnings base may be for the current valuation.
- Your read on CarMax is one view; the desks covering it have another. See what analysts think CarMax's shares could be worth.
The issue now is whether CarMax's earnings are strong and dependable enough to justify where the stock trades today.
To pressure test whether CarMax's earnings justify today's share price, it helps to compare it with other businesses that also screen for valuation appeal, including those in the 35 high quality undervalued stocks.
Has CarMax Run Too Far on Earnings?
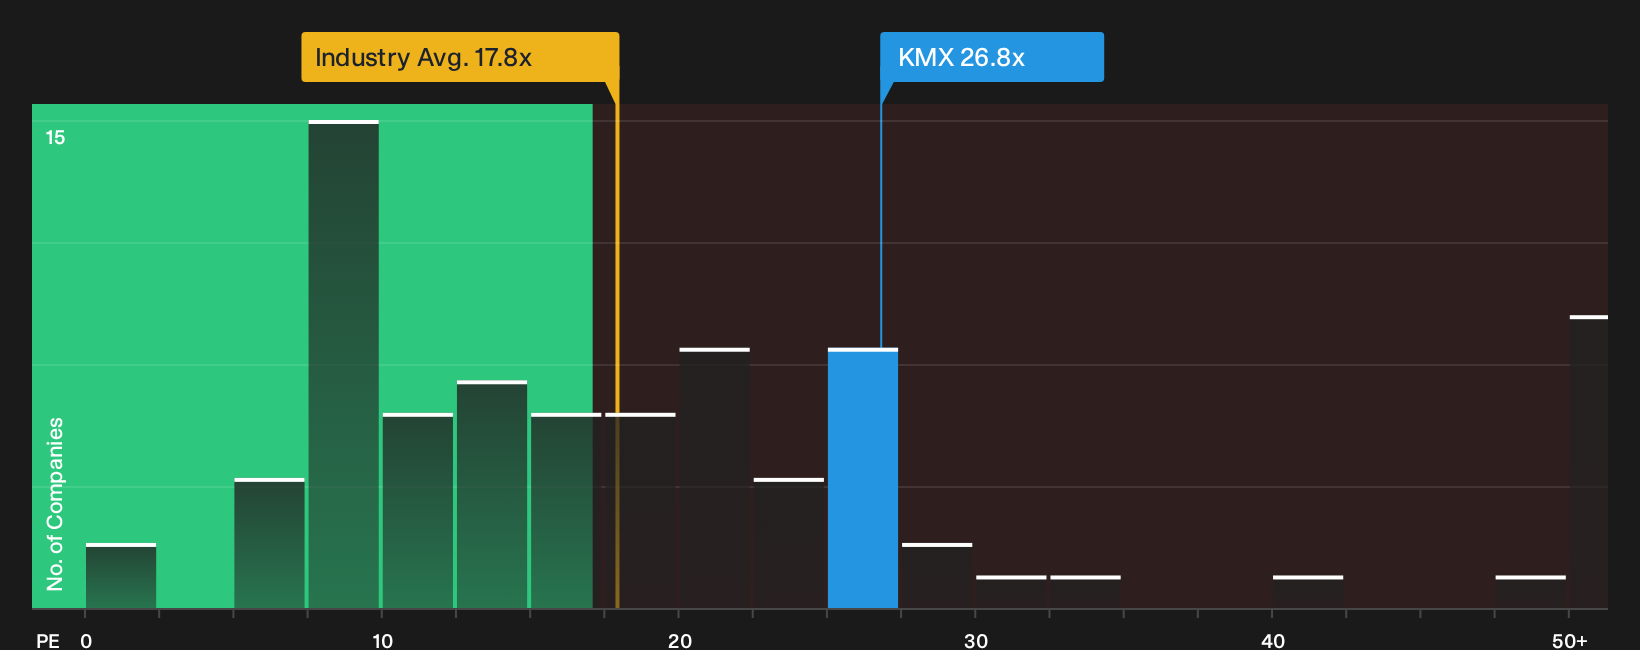
The P/E ratio is a useful lens for CarMax because earnings are a central yardstick for a retailer that depends on steady unit turnover and financing profit. On this measure, the stock trades on roughly 26.8x earnings, which is well above the specialty retail group at about 17.8x and ahead of a broader peer set closer to 11.5x. That kind of step up means buyers today are paying a richer price for each dollar of profit than they would for many comparable businesses.
The fair value model, which adjusts the P/E you might expect for CarMax given its margins, balance sheet risk and scale, points to a lower multiple than where the shares change hands now. The current P/E sitting above that tailored yardstick signals the stock screens as overvalued on this framework, and that the market is already baking in a relatively strong earnings profile. Explore the numbers behind CarMax's P/E valuation.
The CarMax Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the CarMax valuation puzzle leaves off and spell out what future growth, margins and earnings would need to look like for the stock to be worth materially more or less than it is today. Each one treats fair value as a thesis about CarMax's business that you can watch over time, rather than a one off snapshot, and they sit on the platform's Community page.
The Simply Wall St community is split on CarMax, with one group seeing more upside left in the story and another arguing most of the value is already reflected.
Bull case: 12% undervalued
"The current valuation implies the share price does not fully reflect the earnings impact of recent comp growth, higher protection plan margins, CAF contribution, SG&A savings, and expected benefits from greater price transparency..."
Discover why this Narrative puts CarMax at 12% undervalued.
Bear case: roughly fairly valued
"Used comps of 13% against an industry Keith Barr puts at “down 1% or flat to 1%” settle the claim that the business had “turned the corner"..."
Explore why this Narrative puts CarMax at roughly fairly valued.
One more CarMax question that only the future can answer
Everything so far has focused on what CarMax looks like today, yet analysts have built out detailed expectations for where the business might be a few years from now and how that lines up with the current price. Explore where analysts expect CarMax to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com