


AXT has gone from a relatively quiet semiconductor supplier to a stock with a very large three year gain, which now puts a sharper spotlight on whether its current share price lines up with the earnings the business is producing.
- Over the past three years, AXT has delivered a share price increase of about 2,163.8%, which raises the question of how much future profit is already reflected in that move.
- Recent reports of record revenue, stronger gross margins and a swing to net income suggest earnings power may be improving, which can reshape what looks reasonable to pay for each dollar of profit.
- The analysts covering AXT have run their own numbers. See what analysts think AXT's shares could be worth.
The issue now is whether AXT's current valuation is justified by its recent earnings performance and the profit stream investors expect it to generate over time.
If you are weighing whether AXT's recent swing in earnings justifies the run in its share price, it can help to compare it with a broader set of 53 AI infrastructure stocks.
Is AXT Getting Expensive on Earnings?
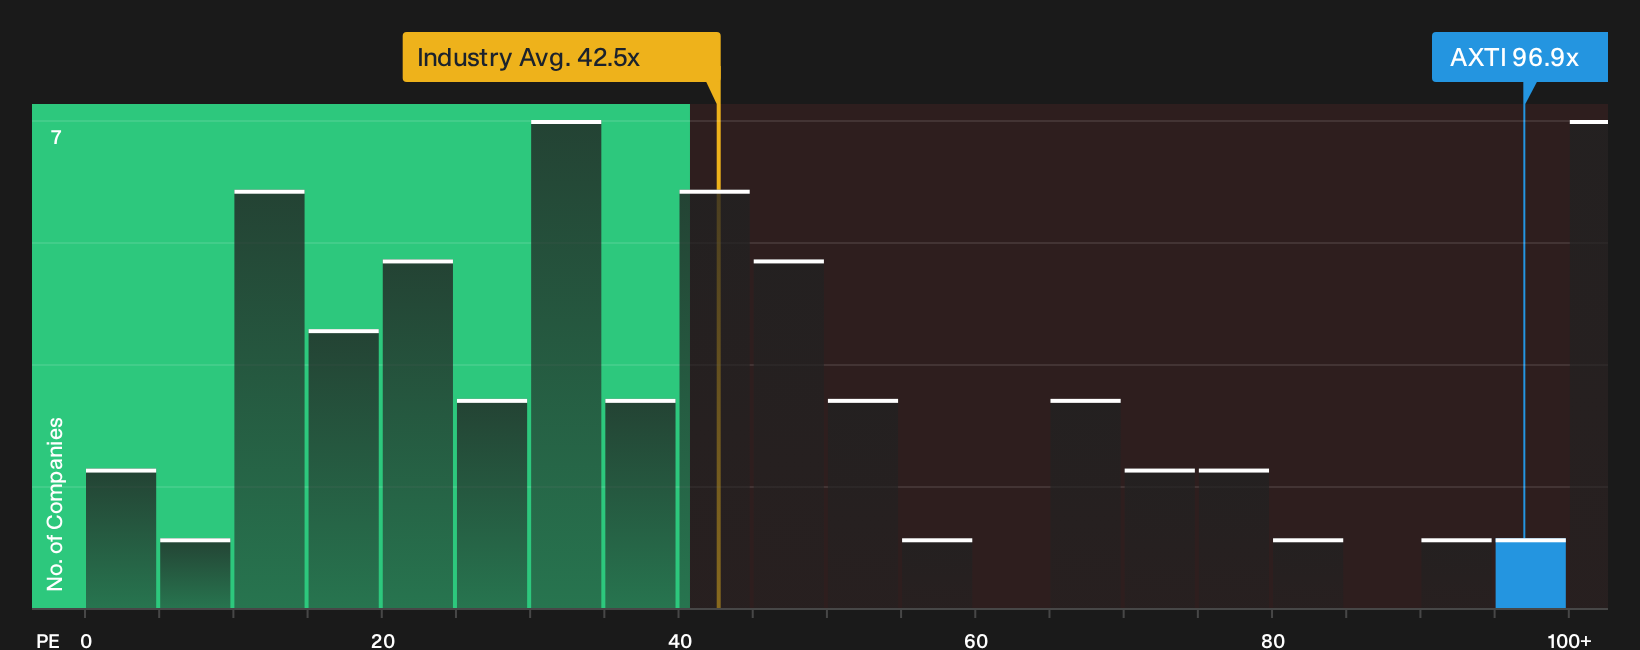
The P/E ratio is a useful way to gauge how much investors are willing to pay today for each dollar of AXT's current earnings. On this measure, AXT trades at about 96.9x earnings, which is more than double the Semiconductor sector average of roughly 42.5x and also above the peer group average of about 41.6x. That kind of gap suggests the market is attaching a premium to the stock's recent profitability and business profile.
Record 2026 revenue from indium phosphide and stronger margins have clearly reset expectations, yet the current P/E still comes in above the multiple implied by a tailored fair value framework that blends AXT's growth outlook, profitability, size and risk. Because of that, the shares screen as overvalued on this earnings yardstick even after the strong fundamental news. Recent headlines about capacity expansion funding and tight indium phosphide supply may help explain why investors are comfortable paying so much for each dollar of profit, but it also raises the bar for what future results need to deliver. Explore the numbers behind AXT's P/E valuation.
The AXT Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the AXT valuation puzzle leaves off. They spell out which paths for growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does now, and set out the assumptions behind each fair value view so you can compare those with AXT's reported numbers as new results come through on the Community page.
One of the top community narratives on AXT: 48% undervalued
"Leadership in high-quality substrate materials and easing export headwinds position AXT for strong revenue growth and higher margins..."
Discover why this Narrative puts AXT at 48% undervalued.
One more AXT signal worth checking before you move on
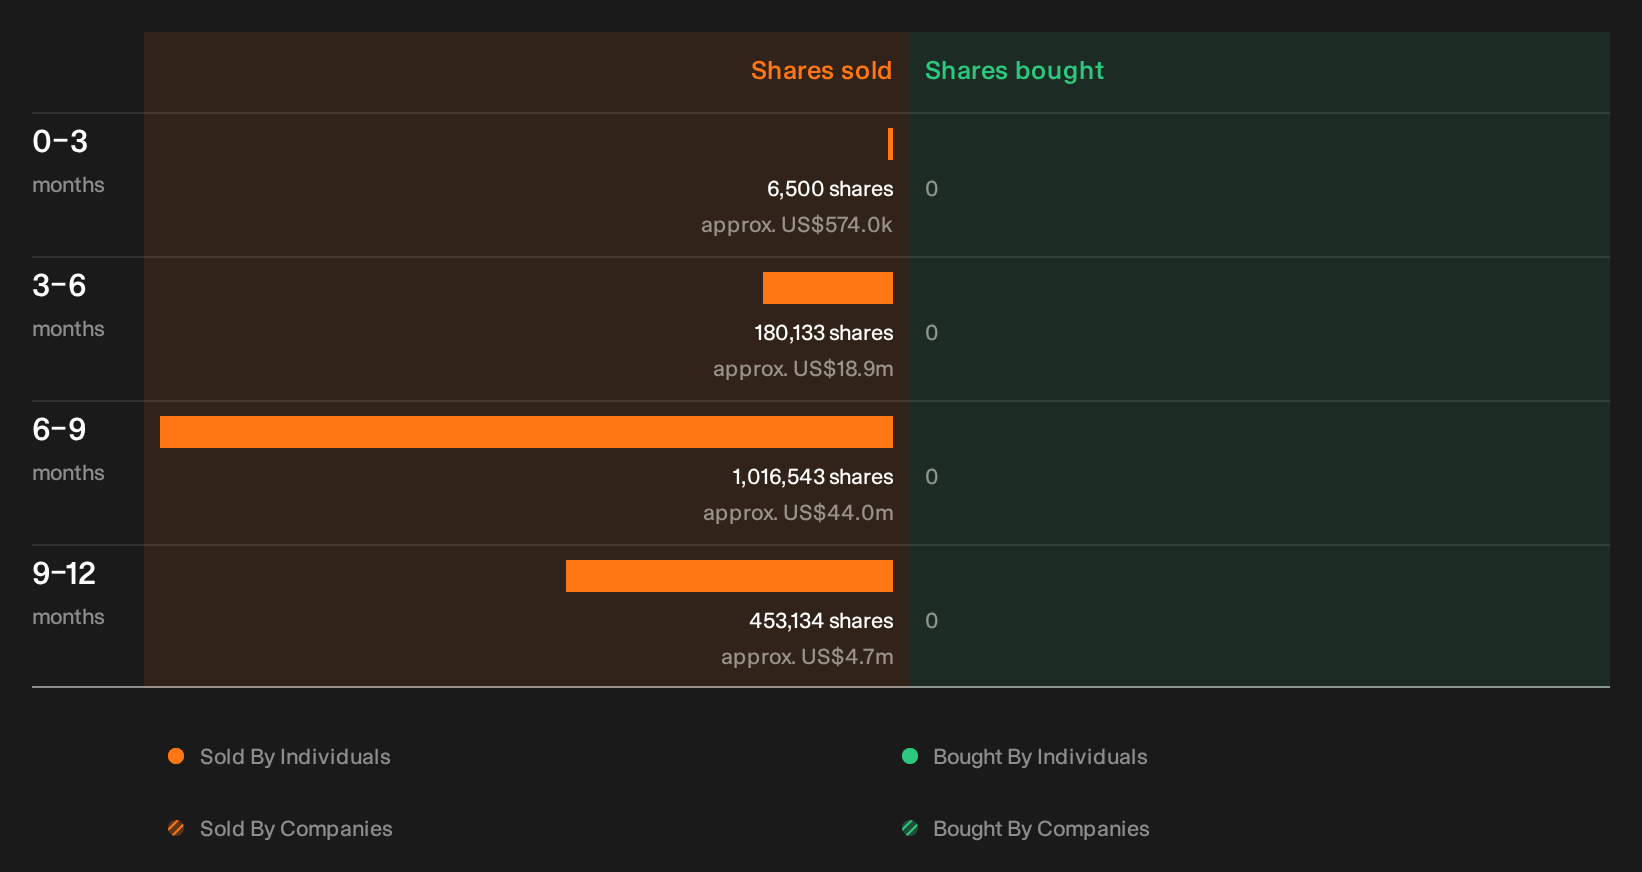
Before deciding what AXT's rich P/E and recent results mean for you, it is worth looking at what recent trades from people inside the business might be signaling about their own expectations. See the recent insider selling flagged for AXT.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com