


Freshpet has delivered a solid rebound for shareholders over the past year, and that recent strength puts a fresh spotlight on whether the current share price lines up with what its earnings can support. After a mixed stretch over the past few years, investors are again asking how much profit power is really baked into the stock at today’s levels.
- Over 5 years, Freshpet shares have declined 42.3%, which puts longer term buyers squarely focused on whether the business now earns enough to justify staying patient.
- Recent commentary around stronger sales growth and healthier gross margins suggests earnings could benefit from better scale and cost discipline, which may support a richer view of the company’s long term profit potential.
- The analysts covering Freshpet have run their own numbers. See what analysts think Freshpet's shares could be worth.
The stock's next move may depend on whether Freshpet's current price can be explained by the earnings the business is generating today and is realistically positioned to generate in the future.
If you are weighing Freshpet's rebound against its earnings support and want a broader starting point for research, a focused screen of other companies can help you benchmark expectations alongside the 35 high quality undervalued stocks.
Has Freshpet Run Too Far on Earnings?
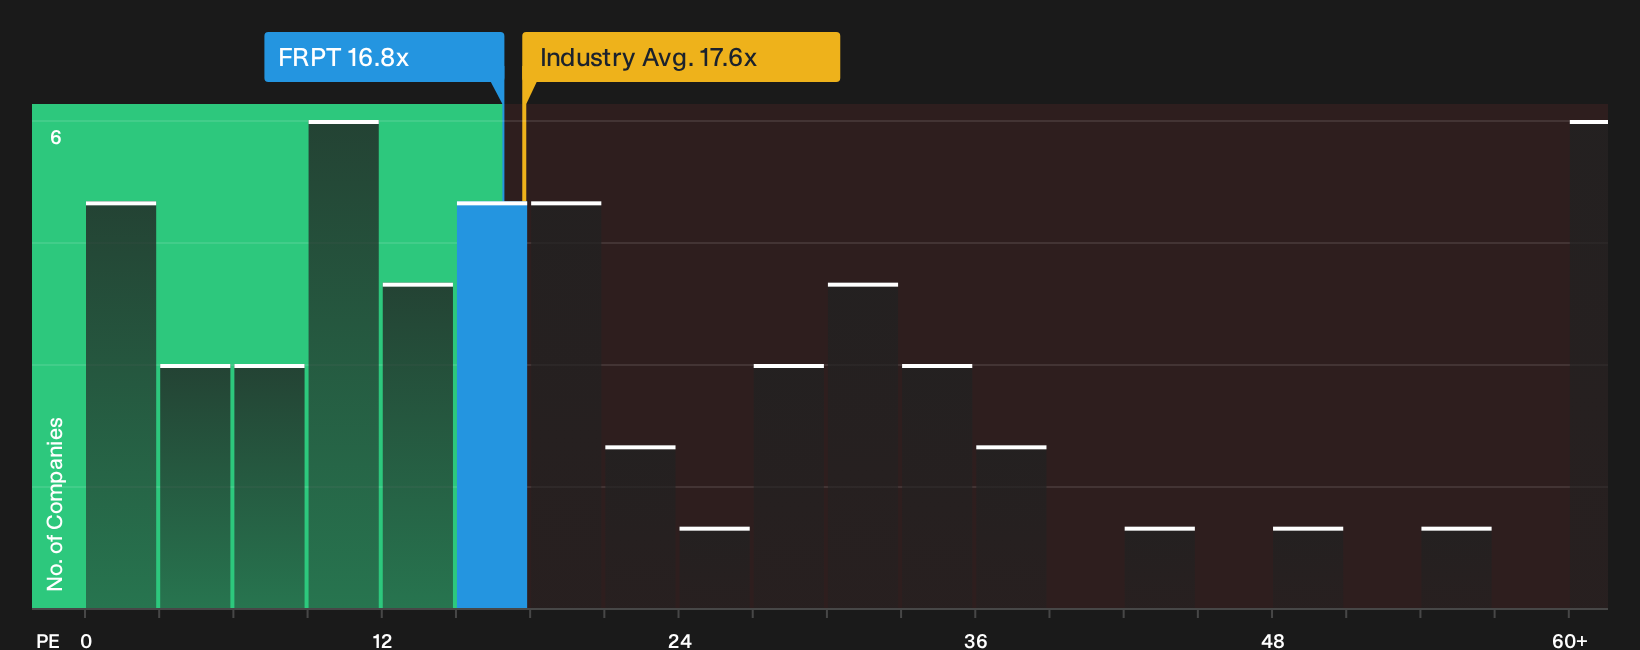
A P/E lens suits Freshpet because investors are focused on how much current earnings justify the share price after the rebound. Freshpet trades on a P/E of 16.8x, which is slightly below the food industry average of 17.6x and also below the peer group on roughly 22.6x. Against the tailored fair multiple that reflects Freshpet’s own growth profile and risk mix, the current ratio screens as overvalued rather than cheap on earnings power alone.
Because management recently reported higher gross margins and raised the 2026 profit outlook, the stock already embeds a lot of that improved narrative in the P/E. For anyone weighing Freshpet, the key judgment is whether that earnings trajectory and margin profile are strong enough to justify paying a premium to the modelled fair level, even though the headline P/E looks softer than peers. Explore the numbers behind Freshpet's P/E valuation.
The Freshpet Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Freshpet valuation puzzle leaves off by explaining which paths for growth, margins and earnings would need to occur for the shares to appear meaningfully stronger or weaker than today’s price. Each narrative connects its figures to a specific view of how Freshpet's expansion prospects, profitability and risk profile could change, giving you something concrete to revisit as new information appears on the Community page.
Freshpet believers and sceptics are looking at the same margin and household data and coming away with very different conclusions.
Bull case: 15% undervalued
"Freshpet’s expansion of digital channels that previously lifted online sales to 13% of revenue is now reinforced by digital orders representing 16.7% of sales and growing 41% year on year..."
Discover why this Narrative puts Freshpet at 15% undervalued.
Bear case: 6% overvalued
"Although Freshpet is benefiting from a shift toward fresh pet food and an expanded household base, rising logistics expense to 6.9% of net sales with an additional US$8 million expected in 2026 suggests distribution complexity can outpace scale benefits..."
Explore why this Narrative puts Freshpet at 6% overvalued.
One more Freshpet angle that can change the story
Price tags and profit ratios only go so far if the people steering Freshpet and the way they are rewarded pull the business in a different direction. See who runs Freshpet and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com