


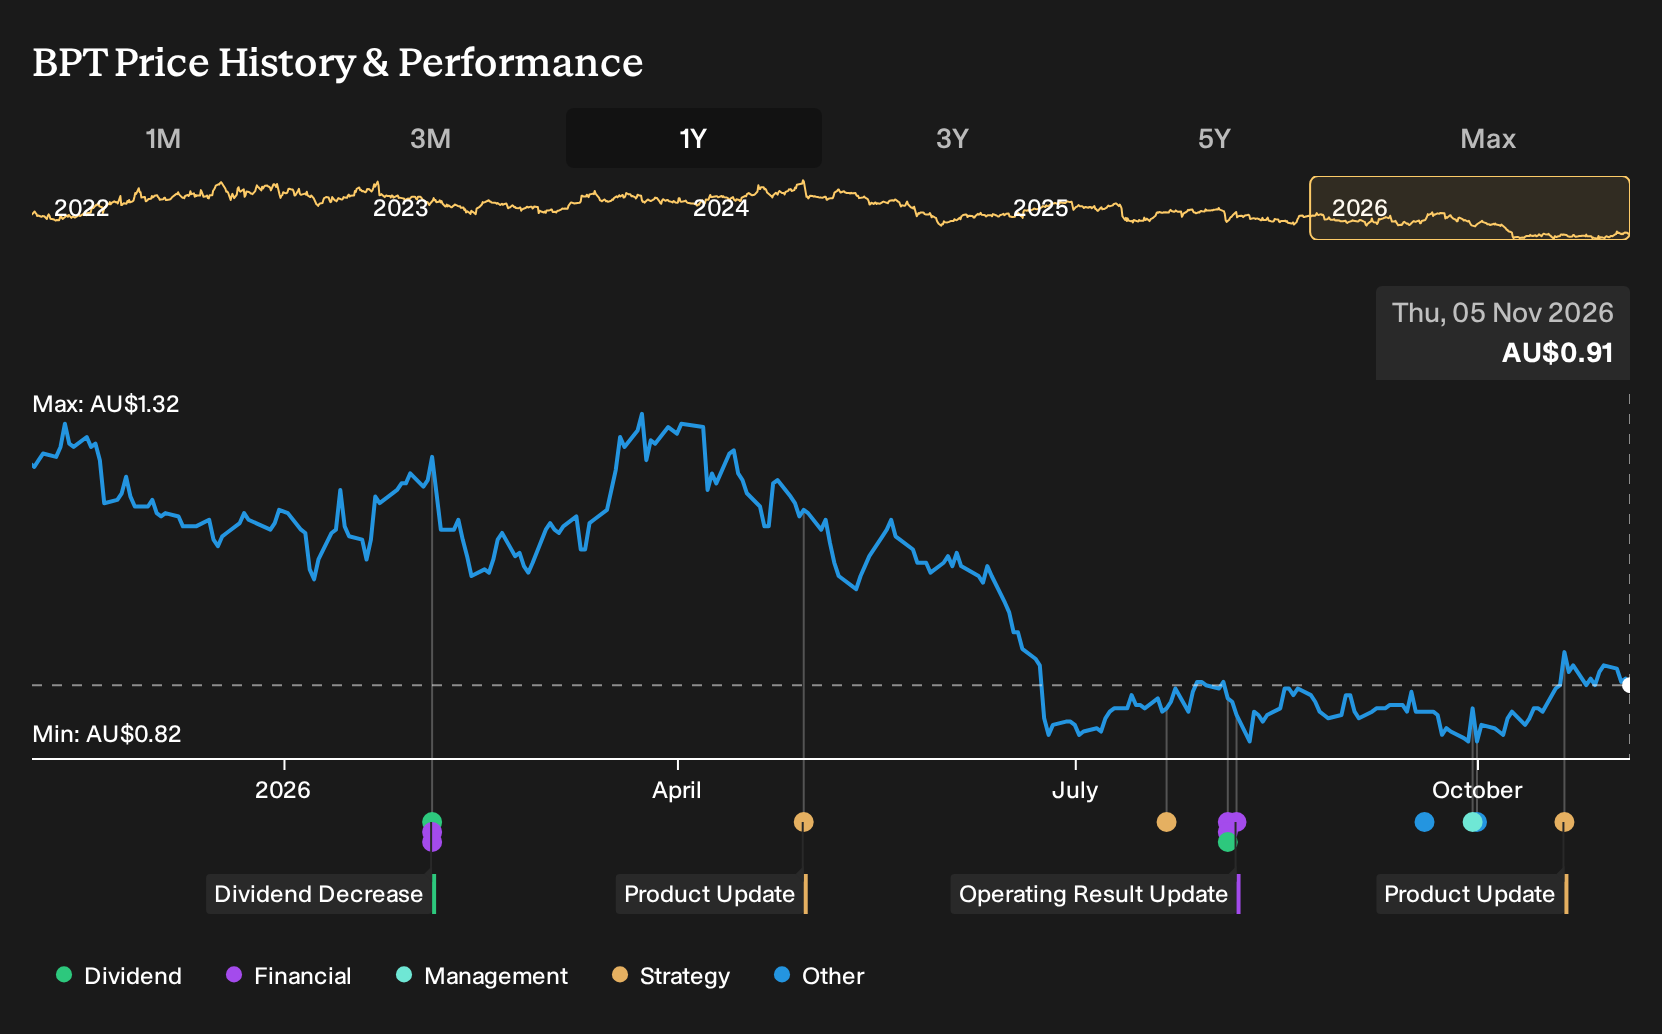
If you backed the consensus view that Beach Energy could use LNG exports and domestic gas re-contracting to steady the ship, the last year punished that optimism. For Beach Energy shareholders, the loss over the past year was 24.8%, including dividends. If you made that call in November 2025 on the bullish or bearish cases on record, which specific assumptions about reserves, Waitsia timing or net zero policy risk most clearly failed your own test?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Beach Energy has already moved. See which of 5 high quality undervalued stocks still trade below our estimates.
The Two Beach Energy Stories Investors Were Weighing
The shares cost A$1.24 at the start of the period, and anyone looking at Beach Energy then was really choosing between two stories that both sounded reasonable.
On the bullish side, the Simply Wall St Narrative put Fair Value at A$1.31 and leaned on Waitsia turning Beach into a meaningful LNG exporter, with higher margins expected as East Coast gas was re-contracted at prevailing prices.
The bearish case anchored Fair Value at A$0.95 and focused on global net zero policies eroding long term oil and gas demand, while a 2P reserve life of just over seven years raised the risk of falling production without new finds or deals.
What The Evidence Did To The Beach Energy Argument
Beach Energy swung from a loss of A$266.1m in H2 2025 to net income of A$131.2m in H2 2026, with net margin moving from a 25.0% loss to a 14.9% profit. That supported the bullish focus on margins and cash generation, even though revenue slipped from A$1,062.4m to A$881.2m, which kept the bearish growth worries alive. Overall, the evidence cut both ways.
The hinge assumption here was that Waitsia led LNG exposure and domestic gas pricing would outweigh reserve and regulatory pressure. When you look at another producer, check whether rising profitability is being achieved alongside stable or growing sales, rather than improved margins masking volume or reserve strain.
What Beach Energy’s Lower Price Asks You To Believe
Beach Energy trades at A$0.91 today, with the selected Narrative placing its Fair Value above that level based on the writer's own assumptions. The argument now leans on cost discipline, reserves and balance sheet flexibility rather than headline growth stories.
For the fall to be an opportunity rather than a warning, a buyer today would need confidence that Beach Energy can turn its lower cost base, drilling outcomes and freed up capital into reliable reserve replacement while handling domestic gas policy risk.
"The current valuation suggests the share price reflects concern that production growth, reserve rebuild, and project execution may not fully translate recent free cash flow, liquidity strength, and Waitsia progress into higher long-term equity value."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
After Beach Energy, What Else?
Beach Energy already puts you squarely in the gas conversation today.
Alongside it sits an unnamed group trying to rewire how hydrocarbons and electricity connect.
Its core idea is straightforward: keep backing lower cost, lower emission fields while building a power arm aiming for steadier cash.
That means hard choices around methane reduction, short cycle oil and gas projects, and which low carbon assets really earn their place.
If that balance tilts further toward resilient cash generation, this group’s role in global energy could quietly shift in surprising ways.
One Narrative has already put a figure on it. → Uncover the company trading 18% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com