


Pacira BioSciences has seen its share price move sharply over the past year, and a cash tender offer at US$36.50 per share has now put a concrete number in front of holders. With that offer on the table, the core question for investors is whether Pacira BioSciences' current price is adequately backed by its earnings profile.
- Pacira BioSciences has delivered a 66.6% return over the past year, which puts real pressure on the earnings story to justify where the stock trades today.
- Viatris' move to acquire Pacira BioSciences for US$36.50 per share in cash highlights how the buyer values the business, which can shape how investors think about the earnings power required to support that kind of price.
- The analysts covering Pacira BioSciences have run their own numbers. See what analysts think Pacira BioSciences's shares could be worth.
The issue now is whether Pacira BioSciences' current share price, in light of the recent offer and past returns, is supported by what its earnings can reasonably justify.
If you want a reference point for how other businesses are being priced on similar earnings questions, it is worth scanning 35 high quality undervalued stocks.
Is Pacira BioSciences Getting Expensive on Earnings?
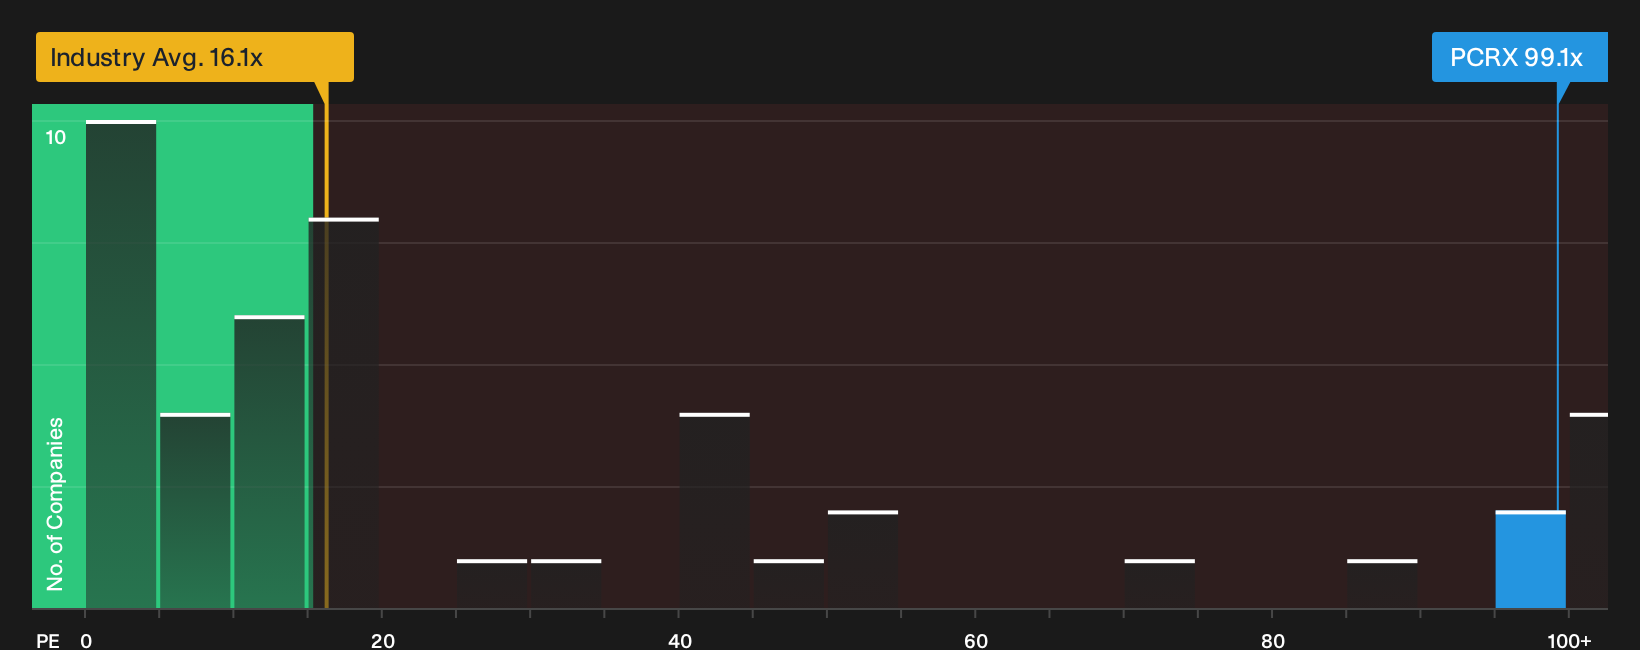
P/E is a useful yardstick for Pacira BioSciences because the tender offer pins down a clear share price against its reported earnings. On that measure, Pacira trades on a P/E of about 99.1x, compared with a pharmaceuticals industry average near 16.1x and a peer group around 12.6x. That is a steep premium, and the Fair Ratio model, which adjusts for the business profile, suggests a much lower multiple would usually be expected for a company with these characteristics.
The gap is large enough that the model is effectively flagging Pacira BioSciences as screening very expensively on earnings, rather than pointing to a tight fair value target. Because Viatris has set a fixed US$36.50 cash offer, the implied P/E here shows how much of that price rests on investors accepting a rich earnings multiple relative to sector norms. Explore the numbers behind Pacira BioSciences's P/E valuation.
The Pacira BioSciences Narrative: What Would Justify Today's Price?
Pacira BioSciences' high P/E and the Viatris offer raise a simple question for anyone holding the stock today. Narratives on Simply Wall St's Community page are meant to bridge that gap by explaining what kind of future for Pacira BioSciences' growth, margins and earnings would need to occur for the shares to be worth clearly more or clearly less than the current price. Where a single ratio or model gives one headline figure, these storylines set out the underlying expectations so you can watch over time whether those assumptions still look realistic.
Community views on Pacira BioSciences now split between one group that still sees more potential in the story and another that thinks most of the upside is already reflected in the Viatris offer.
Bull case: roughly fairly valued
"The recent step up in non GAAP gross margin to roughly 80% reflects a higher structural level that, if maintained on a smaller SG&A base after the Zimmer divestiture, could translate into a sharper improvement in operating margin and earnings than current models assume..."
Discover why this Narrative puts Pacira BioSciences at roughly fairly valued.
Bear case: 8% overvalued
"Pacira BioSciences remains heavily reliant on EXPAREL and on supportive reimbursement policies, and the scheduled expiry of NOPAIN Act reimbursement at the end of 2027 introduces the possibility that a shorter or less favorable extension could reduce reimbursement support and compress revenue, operating margins and net income from current levels..."
Explore why this Narrative puts Pacira BioSciences at 8% overvalued.
Pacira BioSciences' valuation is only part of the story
Pacira BioSciences has an earnings profile and offer price that attract attention, yet the research checks also highlight specific risk signals that could change how you view the whole picture. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com