


SatPort Infrastructure, backed by EQT (OM:EQT), has acquired Speedcast’s teleport infrastructure business, adding 12 teleports across five continents and expanding its carrier neutral satellite ground platform for operators, governments and enterprise clients.
EQT’s backing of SatPort lands at a time when momentum in the stock has recently picked up, with a 1 month share price return of 12.9% and a 7 day gain of 6.0%, even though the share price is still down 10.7% year to date. The 5 year total shareholder return has fallen 32.0% despite a 46.1% gain over three years.
Scan how EQT compares with other specialist infrastructure financiers by reviewing the hand picked 41 power grid technology and infrastructure stocks that are helping fund the backbone of global connectivity.
EQT now trades at a double digit discount to both analyst targets and an intrinsic estimate, even after the recent rebound in the share price. Is the market fairly cautious, or overly sceptical on the business it is backing?
Most Popular Narrative: 15% Undervalued
EQT closed at SEK319.9 against a narrative fair value of SEK375.32, which frames the current share price as meaningfully below that estimate while still within sight of analyst targets. That gap focuses attention on whether the group can turn its expanding private markets platform into the fee-related earnings that underpin this valuation view.
The main thing that has to go right is that EQT turns its enlarged platform, including Coller Capital, Stockbridge, AI infrastructure and evergreen products, into higher fee-related earnings and maintains progress toward its fee-related EBITDA margin target.
The current valuation implies the market is not fully pricing in this broader fee-paying AUM base and the growth plans in areas like AI infrastructure and insurance capital. It also implies the view in this narrative that EQT is undervalued and that the stock has bullish upside potential.
See why 29 investors see EQT as 15% undervalued.
Result: Fair Value of SEK375.32 (UNDERVALUED)
Still, if exit activity stays muted or fundraising toward the more than €140b cycle target slows, the EQT undervaluation story could quickly look less convincing.
Find out about the key risks to this EQT narrative.
Another View: What EQT’s P/E Is Telling You
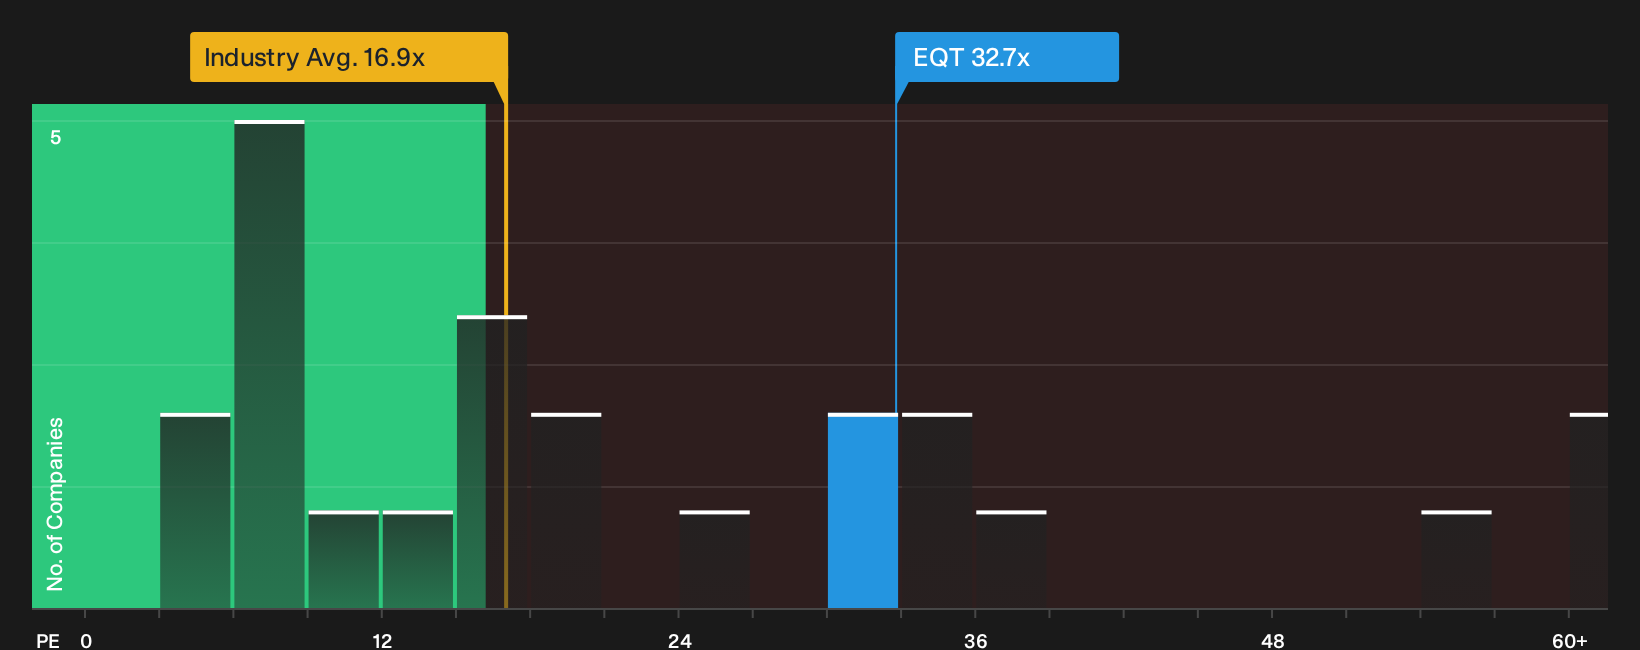
The first narrative leans on fair value and future cash flows. A second lens, the current P/E, paints a tougher picture for EQT. The stock trades on 32.7x earnings compared with a fair ratio of 25.1x, the Swedish Capital Markets average of 16.9x and a peer average of 17.8x.
That is a steep premium. It suggests investors are already paying up for EQT’s growth profile, which can amplify downside risk if expectations around exits, fundraising or margins slip. The question is whether you see this gap as justified quality, or rich pricing that leaves little room for error.
For a closer look at how this price stacks up against earnings power, review the valuation breakdown and what the numbers imply for future moves in the ratio with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the sentiment in this piece feels mixed, that is the point. The opportunity often sits between optimism and doubt. Move quickly and review the 3 key rewards.
Looking For More Investment Ideas Beyond EQT?
You have seen how EQT is being priced today. Do not stop there. Broaden your watchlist and let data driven ideas point you to the next opportunity.
- Zero in on quality at a discount by scanning our 194 high quality undervalued stocks that combine strong fundamentals with pricing that still looks appealing.
- Strengthen the defensive side of your portfolio by filtering for companies on the list of solid balance sheet and fundamentals (195 results) so short term shocks are less likely to catch you off guard.
- Get ahead of the crowd by reviewing the 589 high quality undiscovered gems before these under followed stories reach every investor’s radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com