


The Democratic sweep in the US midterms triggered a sharp rethink of AI spending, and Microsoft (MSFT) moved quickly into focus as investors reassessed how slower data center approvals might affect its existing cloud footprint.
Microsoft’s share price reaction shows how quickly sentiment has swung. The stock jumped 6.7% on the post election move and now trades around $555.80, with a year to date share price return of 17.52% and a 1 year total shareholder return of 12.73%. The 3 year and 5 year total shareholder returns of 57.70% and 74.21% point to momentum that has been building rather than fading as investors weigh fresh AI partnerships, heavy bond financed data center spending and new regulatory risks against the value of the company’s existing cloud infrastructure.
Scan how investors are repositioning around Microsoft’s AI data center story, then size up other potential beneficiaries with the 53 AI infrastructure stocks.
Microsoft now trades near record highs after the post election spike, leaving a simple question for investors sizing up the next leg: Does the current valuation still offer enough upside to justify the AI and data center risks?
Most Popular Narrative: 32% Overvalued
Based on the most followed narrative, Microsoft’s last close at $555.80 sits well above a fair value estimate of $419.91, which frames the recent post election rally as pricing in a lot of AI optimism already.
Microsoft rarely goes on sale, so it''s worth paying attention when the multiple compresses. At around $380, the stock trades at roughly 22 to 23x trailing earnings and ~14x EV/EBITDA, well below its own seven year historical range. This is the cheapest Microsoft has been in years, and the de-rating looks more like a capex cycle worry than a deterioration in the business.
See why 289 investors see Microsoft as 32% overvalued.
Result: Fair Value of $419.91 (OVERVALUED)
Still, this narrative could crack if AI driven capex keeps free cash flow under pressure, or if regulators slow the buildout that supports Microsoft’s premium.
Find out about the key risks to this Microsoft narrative.
Another View: Microsoft Through the Earnings Lens
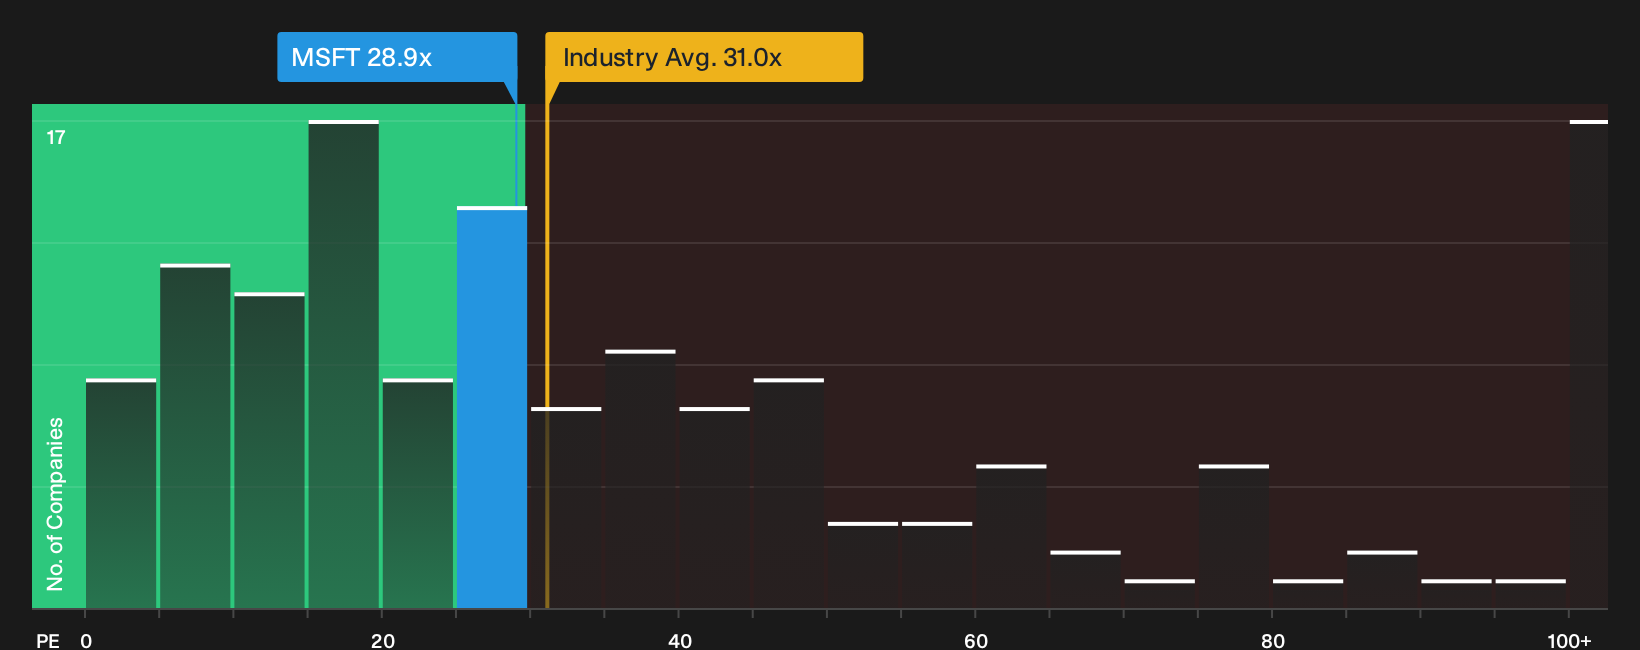
There is a very different story once the focus shifts from that $419.91 fair value narrative to how Microsoft actually trades on earnings. The stock changes hands at a P/E of 28.9x, below the US Software industry average of 31x, yet above a 23.8x peer average, which points to some premium risk but not an extreme one.
The fair ratio for Microsoft is estimated at 56.2x P/E, which is almost double the current level and suggests the market could move toward a much richer multiple over time, or that expectations embedded in that fair ratio prove too optimistic. Which side of that gap do you think is mispriced?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions are mixed on whether Microsoft is being overhyped or fairly rewarded for its AI initiatives and cash flows. Consider acting while sentiment remains divided and carefully evaluate the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Microsoft?
Microsoft’s story is only one angle. You can broaden your opportunity set now, before the next wave of winners is already crowded and harder to assess with a cool head.
- Target potential mispricing by checking companies that screen as quality yet overlooked through the 19 high quality undiscovered gems.
- Strengthen your downside protection by focusing on businesses that appear resilient on key risk checks using the 31 resilient stocks with low risk scores.
- Prioritise financial resilience and funding flexibility by sorting for companies with robust balance sheets through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com