


- Banco Santander reported earnings for the nine months to 30 September 2026, with net interest income of €35,304 million and net income of €12,405 million, alongside basic EPS of €0.83.
- The combination of higher net interest income and stronger earnings per share gives investors a clearer view of how Banco Santander is monetising its global banking platform.
- We will now look at how Banco Santander's net income reshapes the investment narrative investors have been using up to now.
Scan how Banco Santander's latest earnings compare with those of its peers and identify other banks with strong interest income trends using our curated 194 high quality undervalued stocks as a starting universe.
Banco Santander Investment Narrative Recap
To own Banco Santander, you need to be comfortable with a global retail and commercial bank that leans heavily on its ability to control costs, recycle risk weighted assets and grow fee based lines alongside interest income. The recent nine month results, with €35,304 million in net interest income and €12,405 million in net income, broadly reinforce that operating thesis rather than change it.
The near term swing factor still sits in credit quality and funding costs, especially in higher risk markets and competitive arenas such as the UK mortgage book. The main risk remains that elevated bad loans and a low 65% allowance for bad debts force higher provisions, which could blunt the benefit from cost efficiencies and technology projects.
The ruling from the Financial Ombudsman Service ordering Santander to compensate a customer with a gambling addiction does not change the earnings story, but it does put conduct and controls under the spotlight. For a large retail bank, that kind of case matters less for the cheque it writes and more for what it says about monitoring and escalation.
For you as a shareholder, the link to catalysts is around execution of the ONE Transformation and technology roll out. Stronger conduct supervision and faster account restrictions in edge cases like this may require process upgrades and more granular monitoring. Done well, that can support trust and customer retention, which sit quietly behind the cost and fee income targets management is pursuing.
Banco Santander's narrative projects €73.8b revenue and €20.5b earnings by 2029, based on analysts assuming 15.0% yearly revenue growth and an earnings increase of about €7.6b from €12.9b today.
Uncover how Banco Santander's fair value indicates a 28% potential upside to its current price before other investors close the gap.
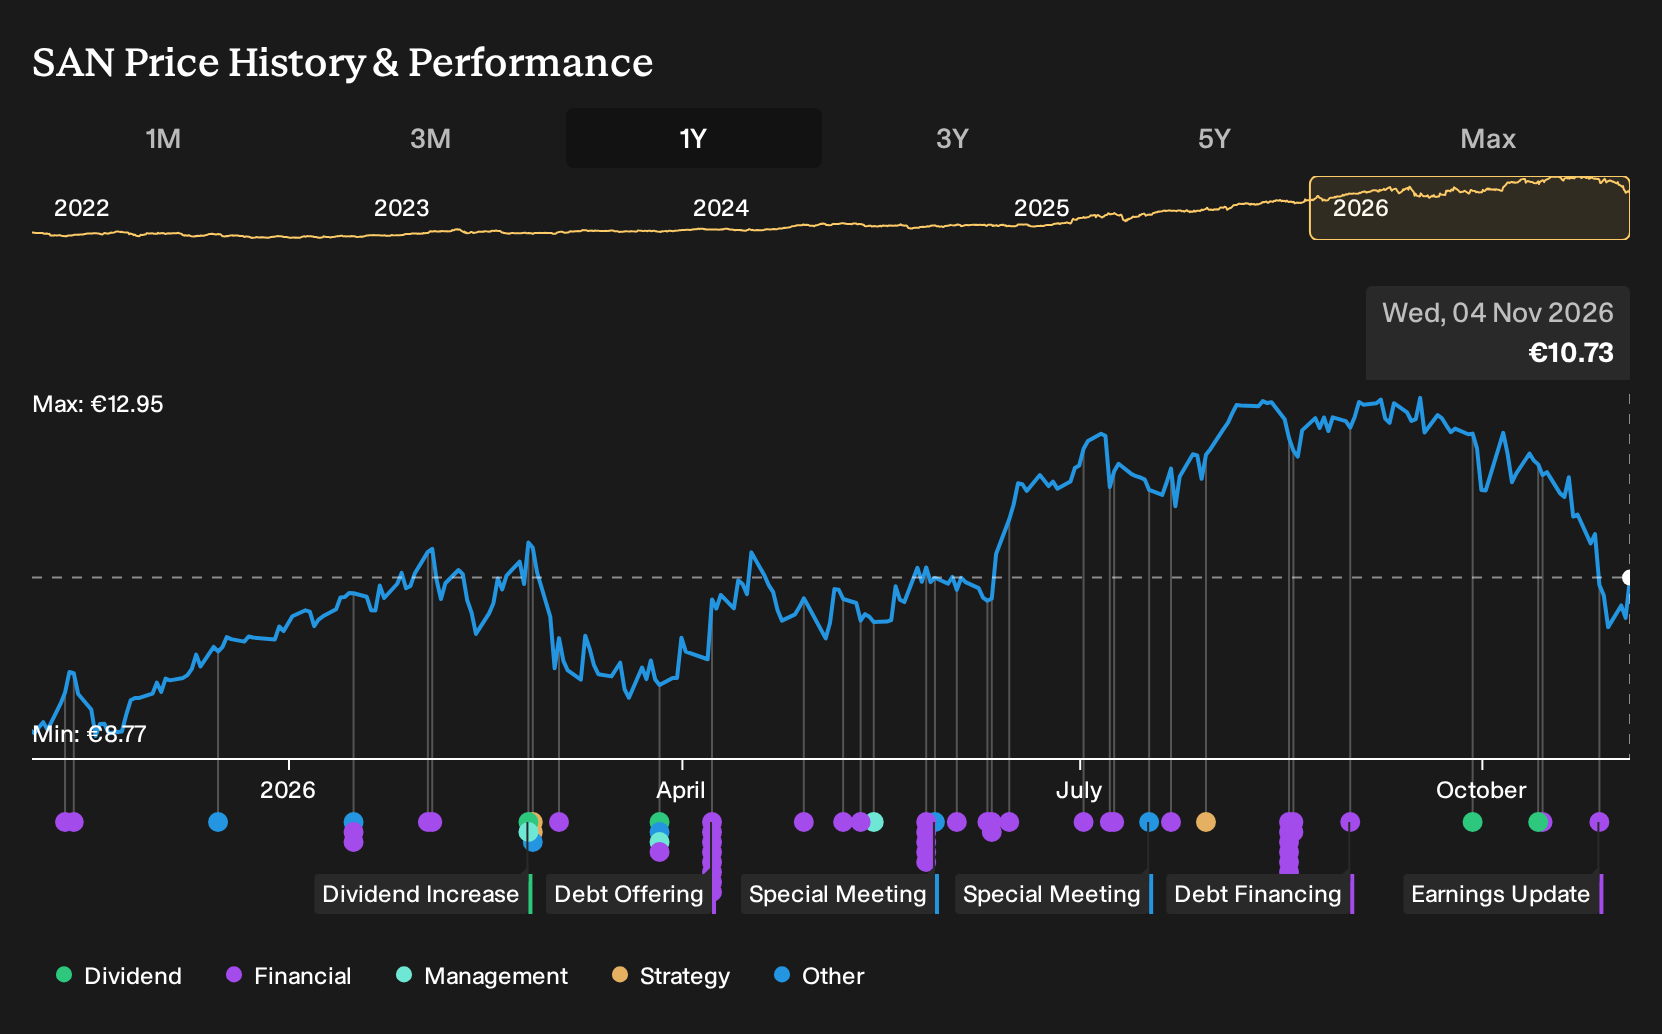
Exploring Other Perspectives
One bullish twist on Banco Santander focuses on conduct risk after the Ombudsman ruling. The most optimistic analysts were already pencilling in €81.4b of revenue and €24.5b of earnings by 2029, assuming cleaner conduct costs and tighter controls. You may now see those projections as too hopeful or as a starting point to test against fresh information.
Explore 5 other Banco Santander fair value estimates, including one that suggests as much as 76% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Banco Santander research is our analysis highlighting 5 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Banco Santander. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banco Santander's overall financial health at a glance.
Looking For More Investment Ideas Beyond Banco Santander?
If Banco Santander has sharpened your thinking about banks and financials, it can be useful to line it up against other companies with very different profiles. A focused screener helps you quickly filter for the traits you care about most, whether that is resilience, income or underappreciated potential.
- For investors who want quality on sale, use our tool built around 194 high quality undervalued stocks to find businesses where fundamentals and pricing are pulling in different directions.
- If capital preservation ranks high on your list, stress test your watchlist against our 217 resilient stocks with low risk scores and focus on companies with more resilient risk profiles.
- When you are hunting for future leaders before wider attention arrives, sort through our carefully curated 589 high quality undiscovered gems and look for stories the market may be underestimating.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com