


The Federal Reserve is wrestling with rapid corporate earnings growth and a hot economy, which keeps the outlook for interest rates higher for longer. Expensive money can punish slow movers yet reward technologies that promise more computing power for each dollar spent. That is where quantum computing companies come in. This article highlights three stocks from our quantum computing screener that show how this theme is taking shape right now.
The stocks covered below are a small sample of the quantum computing companies on the radar, and the full screen surfaced 22 more businesses with equally compelling stories that are not covered in this article. To identify where you want to focus your research next, analyze the Quantum Computing Stocks screener.
IonQ (IONQ)
Overview: IonQ develops trapped ion quantum computers and sells access to them through major cloud platforms along with quantum-focused services.
Operations: IonQ generates about $246 million from computer services, with revenue concentrated in the United States at roughly $145 million.
Market Cap: US$12.9b
IonQ matters for this screener because it builds the physical quantum machines and delivers them through cloud access that developers can use today.
"Physics Risk is Gone (The 99.99% Moat): IonQ announced it has achieved a world-record 99.99% "four-nines" two-qubit gate fidelity."
What happens to IonQ’s long-term economics if a single assumption about how quickly enterprises adopt this quantum-plus-security stack shifts?
If that adoption curve is the real hinge, read the full narrative for IonQ to see how IonQ’s moat, contract mix, and risk profile could be decoupling from the headline story.

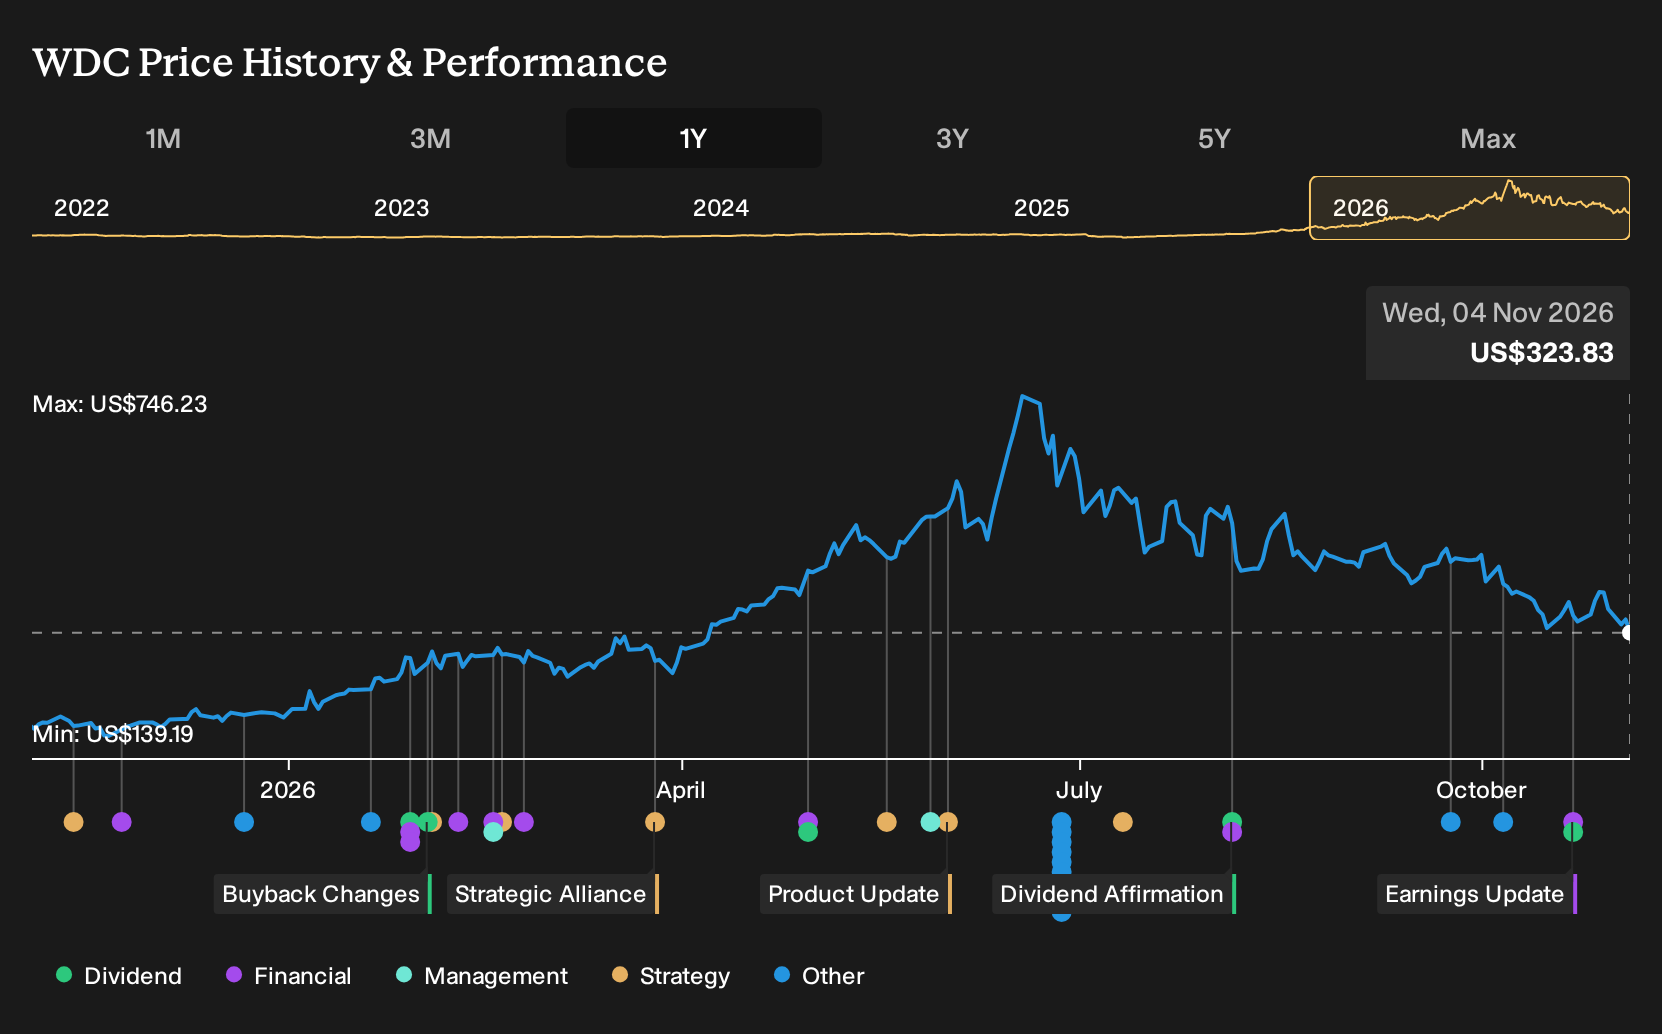
Western Digital (WDC)
Overview: Western Digital develops and sells hard disk drives and data storage systems worldwide, while also pursuing quantum error correction research partnerships.
Operations: Western Digital generates about US$14.5b from hard disk drives, with reported geographic revenue including US$2.2b from Europe, the Middle East and Africa.
Market Cap: US$130b
Western Digital matters for this quantum computing screen because its high capacity drives underpin AI and research data centers, while its Open Quantum Design collaboration targets error correction that could help future quantum hardware become reliable enough for commercial workloads.
"First, capacity. The whole thesis rests on the duopoly holding the line. The moment either player, or a cash-rich new entrant, decides to chase this demand with new plants, the shortage becomes a glut, as it always has in memory and storage."
For investors watching Western Digital, the key consideration is how long pricing power holds before one quiet shift resets expectations.
If you want to know how that quiet reset could play out, read the full narrative for Western Digital to see how Western Digital’s pricing story might be evolving beneath the surface.
TD SYNNEX (SNX)
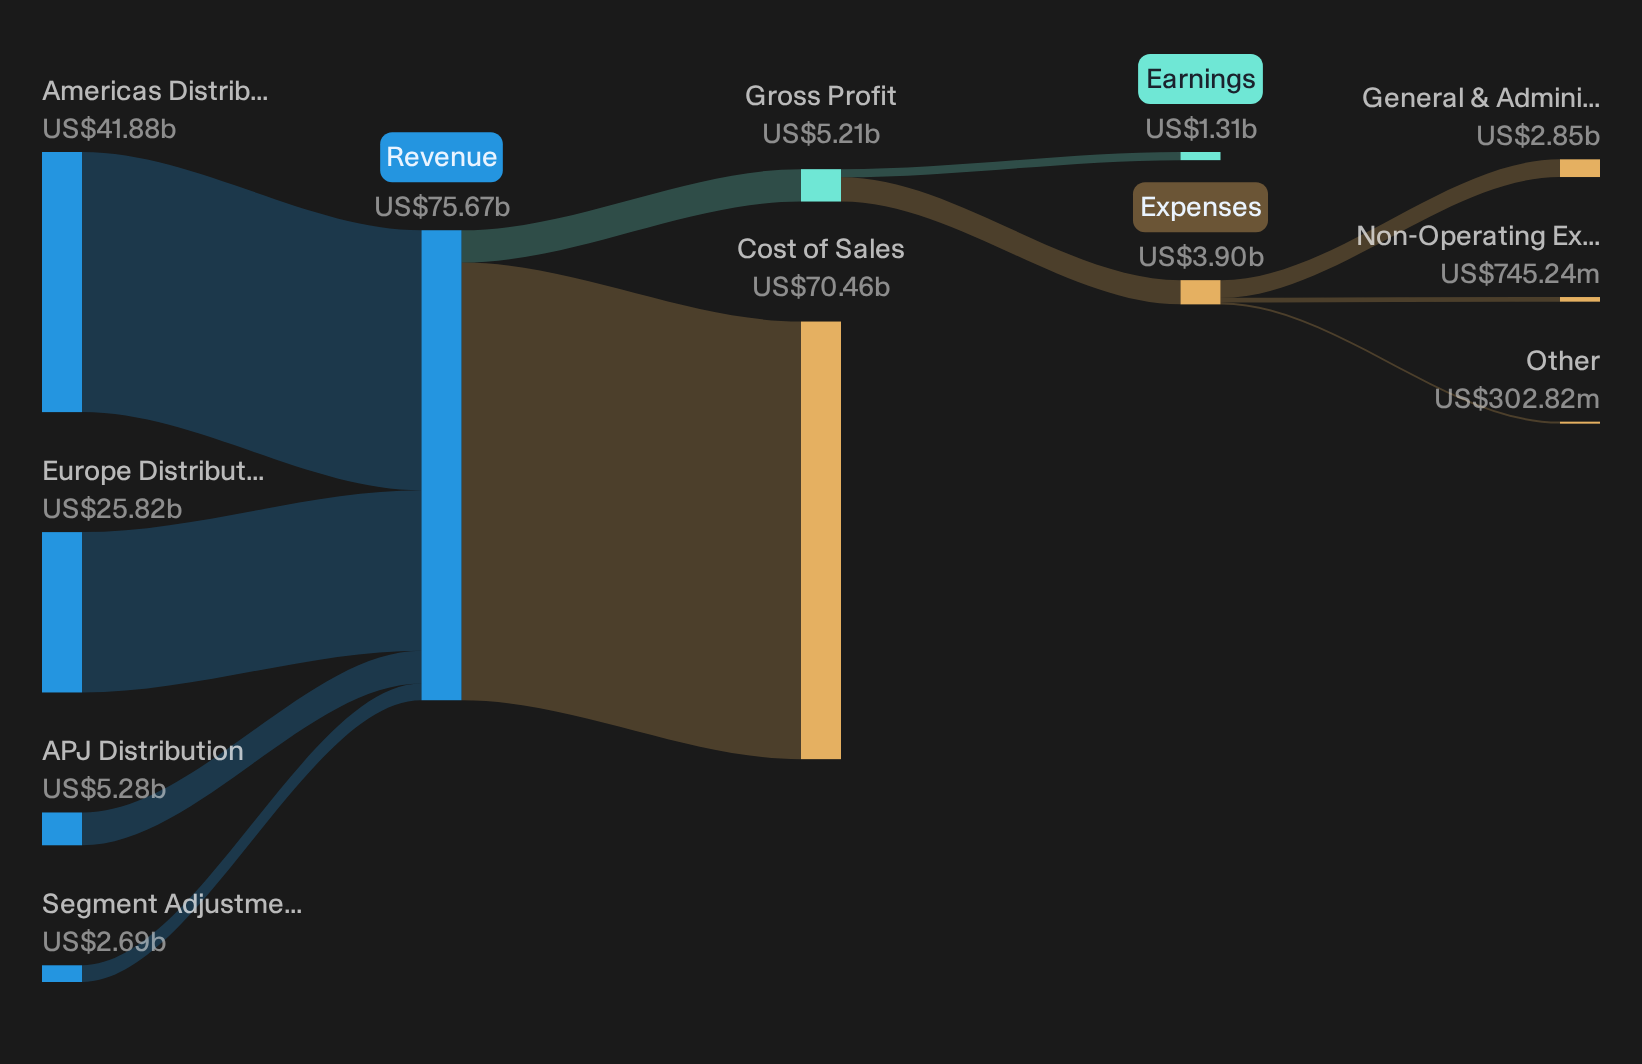
Overview: TD SYNNEX is a global IT distributor and solutions aggregator that connects vendors and customers across hardware, cloud, AI and post-quantum security services.
Operations: TD SYNNEX generates about US$52.0b from Americas and Asia-Pacific Japan distribution, plus roughly US$25.8b from Europe distribution.
Market Cap: US$18.2b
TD SYNNEX matters for this quantum computing screen because its EigenQ alliance gives enterprises a practical way to prepare today for post-quantum security, embedded within the same AI ready infrastructure and services they already buy.
"Hyve is currently absorbing very heavy working capital needs, with free cash flow in Q3 2026 about US$1b in the red and the cash conversion cycle extending to 22 days. If Hyve programs do not shift toward stronger cash generation as expected, TD SYNNEX could face prolonged pressure on liquidity and a weaker link between reported earnings and free cash flow."
What happens to TD SYNNEX’s quantum aligned opportunity if one quiet pressure on this AI infrastructure engine does not ease as planned?
If that pressure point has your attention, read the full narrative for TD SYNNEX to see whether TD SYNNEX’s post quantum story is quietly accelerating behind the cash flow strain.
Curious About Alternative Opportunities?
Fresh ideas move first. While attention chases what is already flying, early momentum often sits under the radar for now. Do not get caught reacting late, get in early.
- Identify income-oriented companies designed for staying power and scan the 5 dividend fortresses before the crowd pursues yield and reduces the most attractive payouts.
- Track cash-rich businesses quietly building momentum and review the 35 high quality undervalued stocks while these potential breakout stories are still only appearing in limited ways in the headlines.
- Consider infrastructure-focused opportunities and explore the 53 AI infrastructure stocks while capital is still rotating slowly and before pricing fully reflects the buildout.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com