


Valero Energy has delivered very strong long term share price gains, yet the recent pullback raises a straightforward question for investors who focus on earnings. After such a run, the issue is whether the current valuation still lines up with what the refinery operator earns today and may earn over time.
- Over the past 5 years, Valero Energy has returned about 4.5x, which puts a lot of weight on the idea that its earnings record can carry that kind of price tag.
- The planned US$320.5 million purchase and restart of the idled Houston refinery may support future profit and cash flow, but it also concentrates more capital into a single refining hub and extends the timeline before that investment fully feeds into earnings.
- There is a second opinion on Valero Energy worth weighing. See what analysts think Valero Energy's shares could be worth.
The stock's next move may depend on whether its current price still lines up with what investors are willing to pay for Valero Energy's earnings power.
If you want to test the same earnings question you are asking of Valero Energy across a wider set of businesses, you can start by scanning 35 high quality undervalued stocks.
Does Valero Energy Look Undervalued on Earnings?
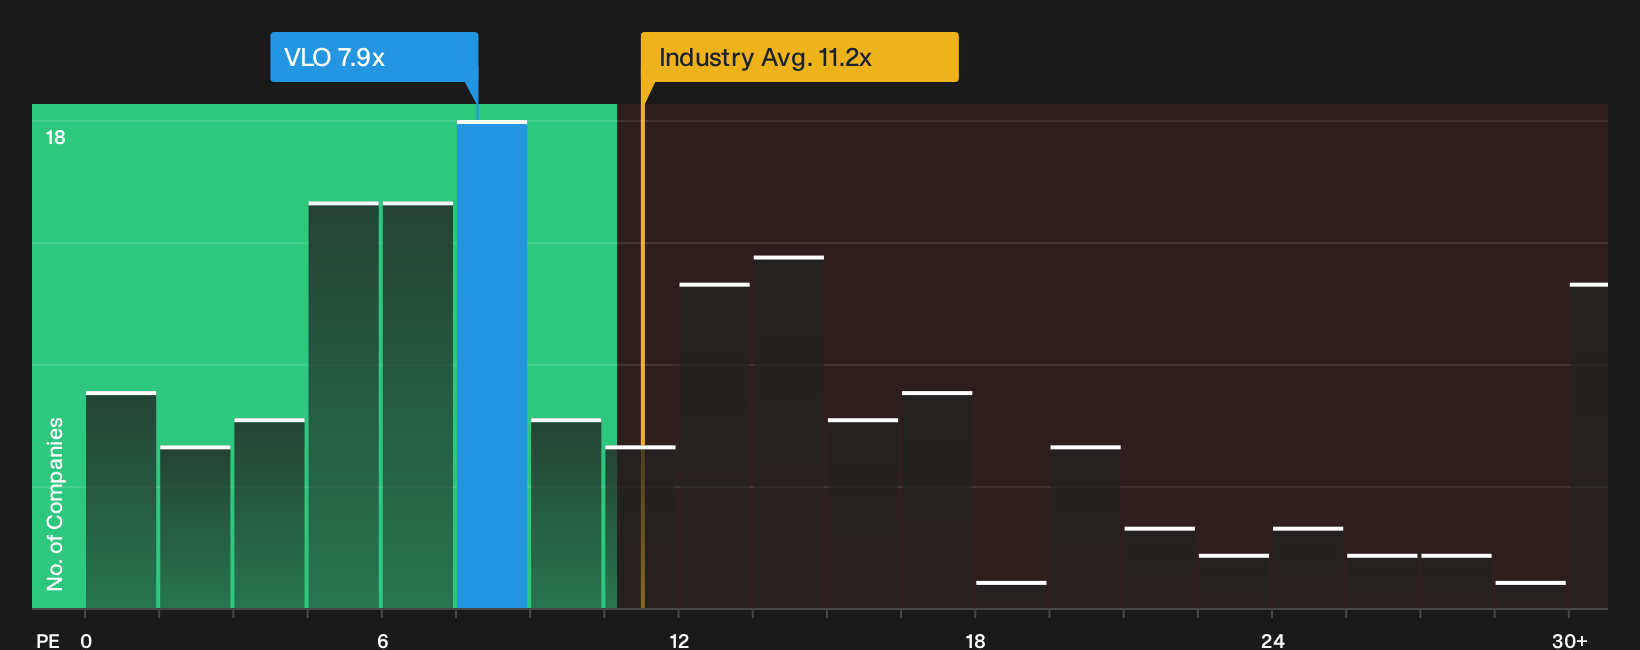
A P/E ratio is a useful shorthand for Valero Energy because refiner earnings tend to be the main anchor for what investors are willing to pay. Valero Energy currently trades on a P/E of about 7.9x. That sits above the peer average of roughly 6.0x, yet below the wider Oil and Gas industry average of about 11.2x. The modelled fair multiple, which blends the company’s growth outlook, profitability, size and risk profile, points to a higher figure than where the shares change hands today, so the stock screens as undervalued on this lens.
Because the Houston refinery acquisition concentrates more capital into the Gulf Coast system, investors who focus on earnings need to judge whether that planned expansion justifies even a modest premium to close peers. Despite that added project risk, the current P/E still reflects a discount to what the tailored fair multiple suggests Valero Energy might support over time, which may appeal to readers who anchor their view mainly on earnings power. Explore the numbers behind Valero Energy's P/E valuation.
The Valero Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off for Valero Energy by spelling out which paths for future growth, margins and earnings would need to hold for the refinery operator to be worth meaningfully more or less than today’s share price. Each narrative ties a fair value to a particular mix of potential catalysts and risks, so you can watch over time which version of Valero Energy's story appears to be taking shape.
Community views on Valero Energy are now split between those who think current refining strength still leaves room on the upside and those who see the good news already priced in.
Bull case: 14% undervalued
"Very low net debt at around 11% of capital, cash balances above the stated US$4b to US$5b target range and payout ratios of 59% through dividends and buybacks indicate that a significant portion of free cash flow is already being directed to shareholders..."
Discover why this Narrative puts Valero Energy at 14% undervalued.
Bear case: 30% overvalued
"Record refining throughput at 3.1 million barrels per day and 98% utilization, if treated as a new normal, could leave limited headroom to grow volumes further and expose revenue to any pullback in utilization or demand..."
Explore why this Narrative puts Valero Energy at 30% overvalued.
Before You Decide On Valero Energy, There Is One More Piece To Check
Valero Energy may look appealing on earnings, yet the research screen has also flagged specific risk checks that deserve a closer look before you lean on the valuation alone. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com